What does a credit card EMI really cost once GST and fees are added?
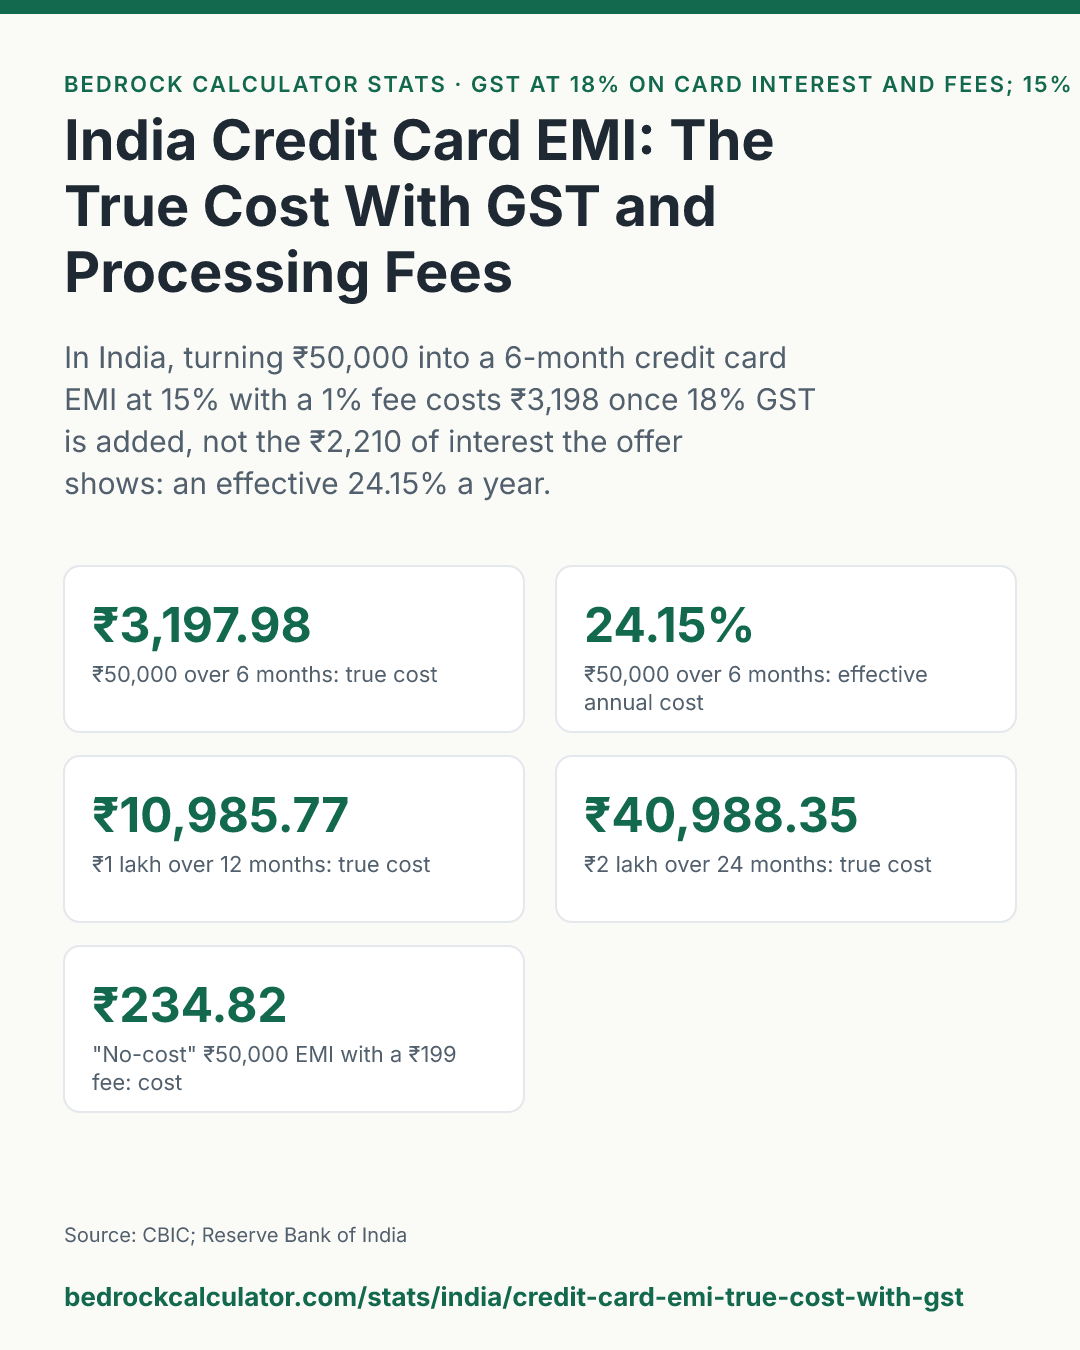
Converting ₹50,000 on an Indian credit card into a 6-month EMI at 15% a year, with a 1% processing fee, costs ₹3,197.98 in total. The offer shows ₹2,210.14 of interest. The other ₹987.84 is the fee plus 18% GST on both the interest and the fee, which adds 44.7% on top of the interest.
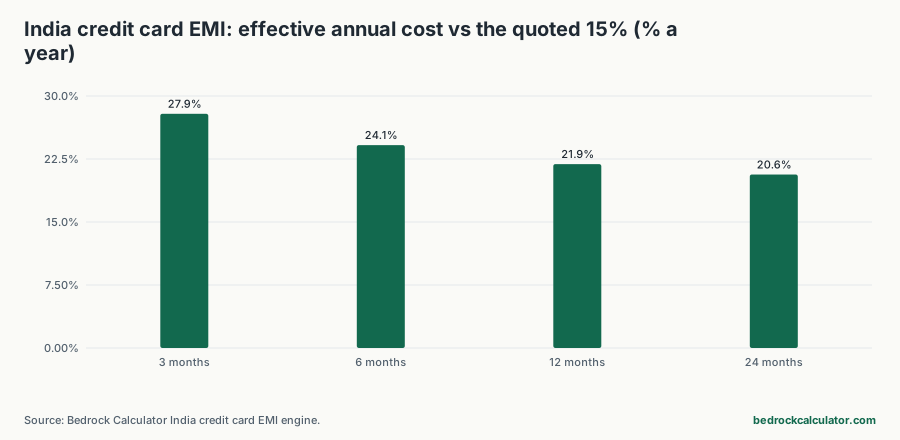
Counting everything, that EMI costs an effective 24.15% a year, against the 15% on the offer.
How we worked out these numbers
We ran each amount and tenure through the credit card EMI calculator on this site. It uses:
- A reducing-balance EMI at 15% a year, the way card issuers calculate EMI plans
- GST at 18% on the interest in every instalment, added to that month's bill
- A processing fee of 1% of the amount, plus 18% GST on it, billed with the first EMI
- An effective annual cost: the yearly compound rate at which the amount you converted equals everything you pay back
The 15% rate and 1% fee are illustrative. Issuers set their own, so check your card's offer.
Why GST at all? Interest on ordinary loans is exempt from GST in India, but the exemption specifically leaves out interest involved in credit card services. So card EMI interest is taxed at the standard 18% rate for services, and so is the processing fee. The GST calculator shows the same rate applied to any amount.
The true cost of a card EMI at common amounts and tenures
Amounts in rupees. Click a column heading to sort.
India credit card EMI: true cost at 15% with a 1% fee and 18% GST (₹)
Download CSVReducing-balance EMI; GST on each month's interest and on the fee; fee billed with the first EMI. Rupees.
| ₹25,000 | 3 | ₹8,543 | ₹628 | ₹250 | ₹158 | ₹1,036 | 27.88 |
| ₹25,000 | 6 | ₹4,351 | ₹1,105 | ₹250 | ₹244 | ₹1,599 | 24.15 |
| ₹50,000 | 3 | ₹17,085 | ₹1,255 | ₹500 | ₹316 | ₹2,071 | 27.88 |
| ₹25,000 | 12 | ₹2,256 | ₹2,077 | ₹250 | ₹419 | ₹2,746 | 21.89 |
| ₹50,000 | 6 | ₹8,702 | ₹2,210 | ₹500 | ₹488 | ₹3,198 | 24.15 |
| ₹1,00,000 | 3 | ₹34,170 | ₹2,510 | ₹1,000 | ₹632 | ₹4,142 | 27.88 |
| ₹25,000 | 24 | ₹1,212 | ₹4,092 | ₹250 | ₹782 | ₹5,124 | 20.65 |
| ₹50,000 | 12 | ₹4,513 | ₹4,155 | ₹500 | ₹838 | ₹5,493 | 21.89 |
| ₹1,00,000 | 6 | ₹17,403 | ₹4,420 | ₹1,000 | ₹976 | ₹6,396 | 24.15 |
| ₹2,00,000 | 3 | ₹68,340 | ₹5,021 | ₹2,000 | ₹1,264 | ₹8,284 | 27.88 |
| ₹50,000 | 24 | ₹2,424 | ₹8,184 | ₹500 | ₹1,563 | ₹10,247 | 20.65 |
| ₹1,00,000 | 12 | ₹9,026 | ₹8,310 | ₹1,000 | ₹1,676 | ₹10,986 | 21.89 |
| ₹2,00,000 | 6 | ₹34,807 | ₹8,841 | ₹2,000 | ₹1,951 | ₹12,792 | 24.15 |
| ₹1,00,000 | 24 | ₹4,849 | ₹16,368 | ₹1,000 | ₹3,126 | ₹20,494 | 20.65 |
| ₹2,00,000 | 12 | ₹18,052 | ₹16,620 | ₹2,000 | ₹3,352 | ₹21,972 | 21.89 |
| ₹2,00,000 | 24 | ₹9,697 | ₹32,736 | ₹2,000 | ₹6,252 | ₹40,988 | 20.65 |
Because the fee is a percentage and GST is a percentage, every cost here scales with the amount. ₹2 lakh costs eight times what ₹25,000 does on the same terms, and the effective annual cost is identical for every amount at a given tenure. Tenure is what changes the picture.
Shorter is cheaper in rupees, dearer per year
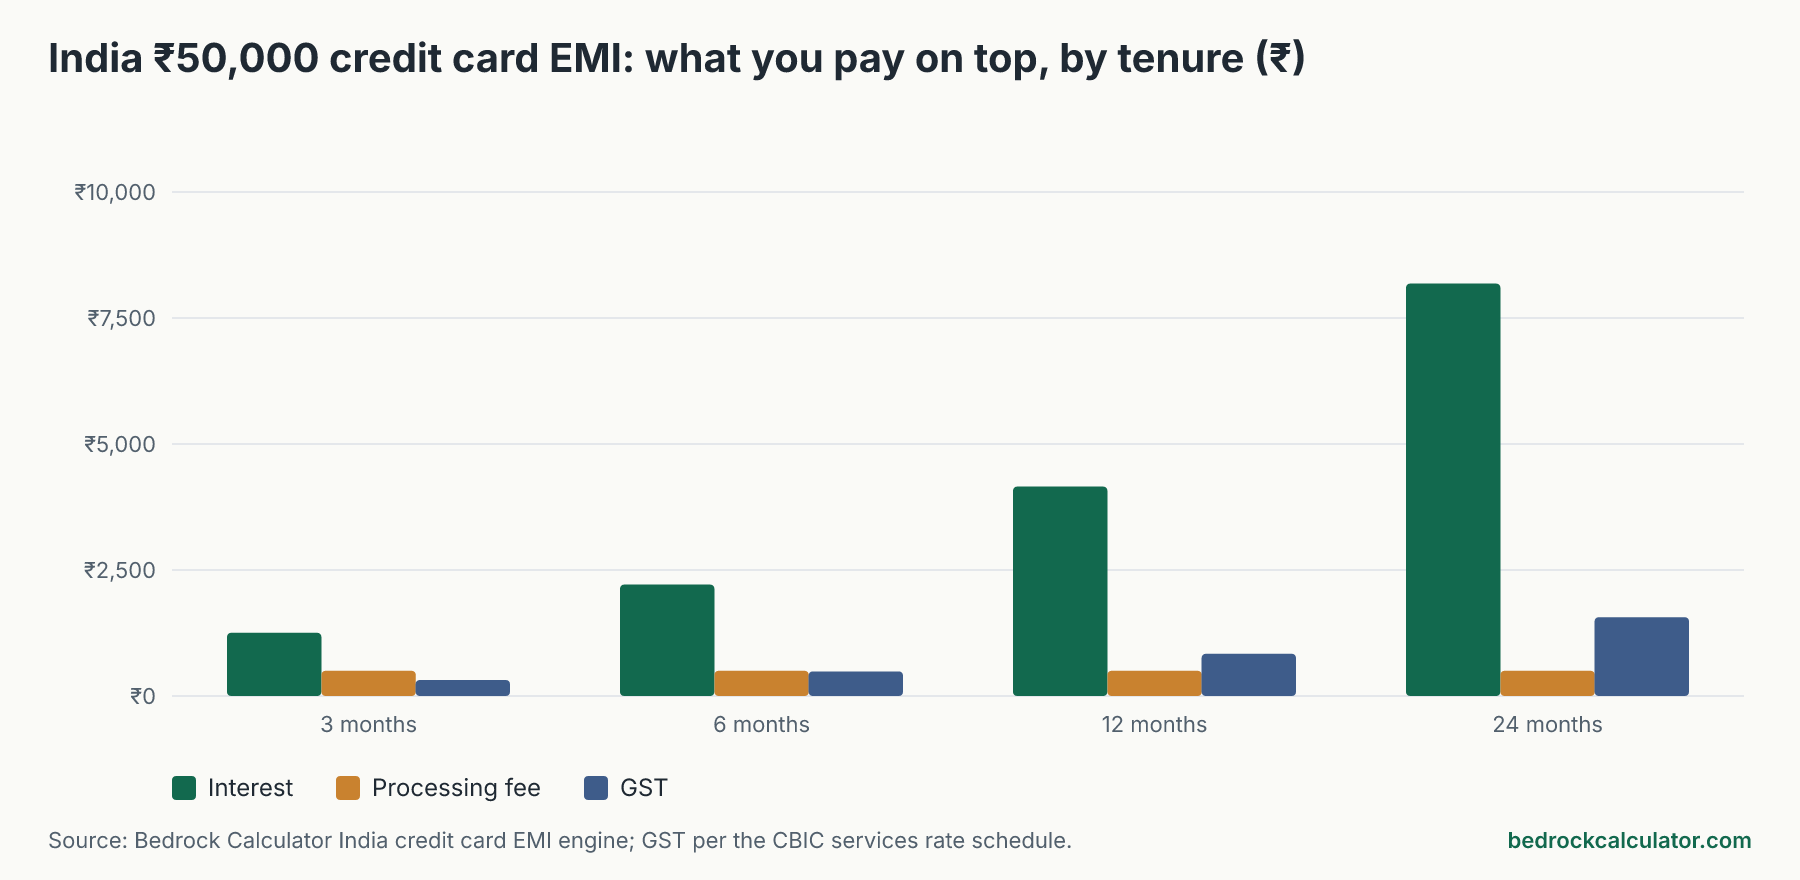
On ₹50,000, the true cost rises with the tenure: ₹2,071.12 over 3 months, ₹3,197.98 over 6, ₹5,492.87 over 12 and ₹10,247.12 over 24. That is just more months of interest.
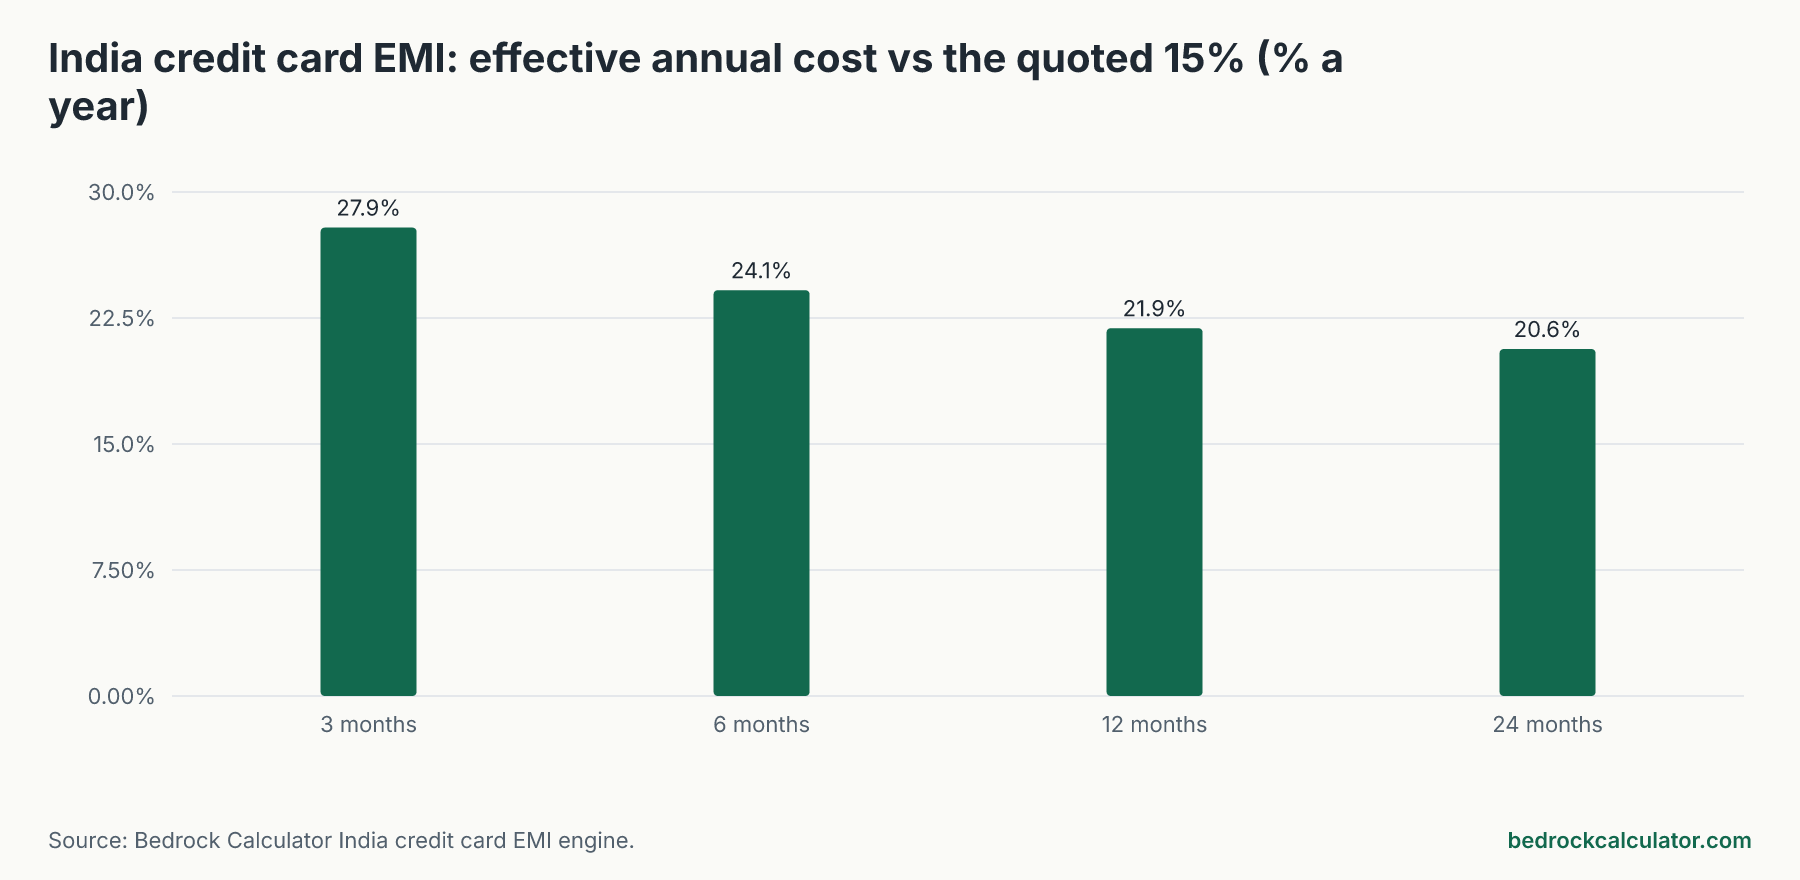
The effective annual cost runs the other way: 27.88% over 3 months, falling to 20.65% over 24. The processing fee is a one-off charge paid at the start, so on a short plan it is spread over very little borrowing time. That doesn't make a long plan a good idea. It means a 3-month EMI with a fee is an expensive way to borrow for 3 months.
Either way, every one of these effective rates is well above the 15% printed on the offer.
What the first bill looks like
The first statement after conversion is the biggest. On ₹50,000 over 6 months it is ₹9,404.19: the EMI of ₹8,701.69, GST on the first month's interest, the processing fee and the GST on that fee. After that each bill is the EMI plus a shrinking amount of GST, because the interest falls as you repay.
The RBI's card rules require the issuer to show the principal, interest and any upfront discount before you convert, and to show them separately on your statement. They also stop issuers charging interest on unpaid charges and taxes, so GST you have not yet paid does not itself attract interest.
Is a no-cost EMI really free?
Close, but not quite. A ₹50,000 "no-cost" EMI with no interest and a ₹199 processing fee still costs ₹234.82 once GST on the fee is added, an effective 1.63% a year. That's cheap, but it isn't free, and the GST on the fee is the part the offer leaves out.
Just check your statement: on some no-cost plans the issuer does charge interest and the seller offsets it with a discount, and GST on that interest can still show up on your bill.
Card EMI vs other options
- Pay the full bill. If you can clear the statement by its due date, the card charges no interest at all. That beats every row in the table.
- A card EMI vs revolving the balance. If the alternative is carrying an unpaid balance, compare the effective cost here with the finance charge your card applies to a revolving balance, which its terms and statement show. Converting can be the cheaper of the two.
- A personal loan. Compare its rate and fee against the effective cost here, not against the EMI plan's headline rate.
What these figures leave out
- Pre-closure charges if you end the plan early
- Late payment fees and finance charges if you miss an EMI
- Statement-date timing, which can move the first bill
- Fee caps or flat fees, which some issuers use instead of a percentage
Working out your own card EMI cost
Open the credit card EMI calculator, enter the amount, the rate and fee from your issuer's offer and the tenure. It shows the true cost, the first bill and the effective annual rate, with a month-by-month schedule. If you are weighing a big purchase on EMI against a bigger loan, the home loan EMI calculator uses the same reducing-balance method without the GST.