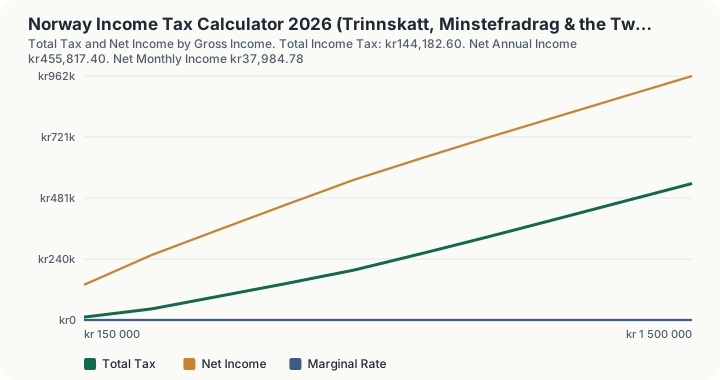
Quick Answer: On a gross wage of 600,000 kr for income year 2026, total Norwegian income tax is 144,182.60 kr. That is 85,747.20 kr of tax on alminnelig inntekt at 22%, plus 12,835.40 kr of trinnskatt and 45,600 kr of trygdeavgift, both charged on the undiminished gross. Net income is 455,817.40 kr, or 37,984.78 kr a month, an effective rate of 24.03% against a marginal rate of 33.60%.
What does this calculator do?
Norway does not tax you once. It taxes the same person on two different bases in the same year, and almost every confusion about Norwegian payslips comes from mixing them up.
The first base is alminnelig inntekt (general income). It is gross income less the minstefradrag, less the personfradrag, less any other deductions you claim. It is taxed at a flat 22%.
The second base is personinntekt (personal income). It is your gross wage or pension with no deductions taken off at all. Trinnskatt (the bracket tax) and trygdeavgift (the national insurance contribution) are both charged on this figure.
Two consequences follow that no single "effective rate" number can show you, and this calculator computes both rather than merely mentioning them.
First, a deduction is worth exactly 22 øre in the krone, never your marginal rate. Union dues, commuting costs and the parental deduction touch only the first base. A person on 1,500,000 kr and a person on 350,000 kr get identical value from the same 10,000 kr deduction. That is the reverse of how most progressive systems behave, and it is why the calculator reports the value of a krone of extra deduction as a separate output.
Second, the minstefradrag is 46% of wage income only until it hits its cap of 95,700 kr. Below the cap, every extra krone you earn also enlarges the deduction, so only 54 øre of it ever reaches the 22% base. Above the cap the whole krone does. Crossing the cap therefore raises the marginal rate by 0.46 x 22% = 10.12 percentage points in a single step, at a gross income of 95,700 / 0.46 = 208,043.48 kr. That kink sits far below the first meaningful trinnskatt threshold, so it lands on part-time and lower-paid full-time workers rather than on high earners, and it appears nowhere in the published bracket table.
How is this calculated?
The engine computes three separate taxes and adds them:
Total tax = 0.22 × max(0, G − M − P − D) + Trinnskatt (G) + Trygdeavgift (G)
where $G$ is gross income, $M$ the minstefradrag, $P$ the personfradrag of 114,540 kr and $D$ your other deductions.
Step 1: Compute the minstefradrag. For wage income it is 46% of gross, capped at 95,700 kr. For pension income the rate is 40% and the cap 75,400 kr.
Step 2: Compute alminnelig inntekt. Gross, less the minstefradrag, less the personfradrag of 114,540 kr, less other deductions, floored at zero.
Step 3: Tax alminnelig inntekt at the flat 22%.
Step 4: Compute trinnskatt on gross personinntekt. The 2026 scale is applied progressively to gross income with no deduction of any kind: 0% to 226,100 kr, then 1.7%, 4.0% from 318,300 kr, 13.7% from 725,050 kr, 16.8% from 980,100 kr and 17.8% from 1,467,200 kr.
Step 5: Compute trygdeavgift on the same gross figure. Zero at or below the lower threshold of 99,650 kr. Above it, the smaller of the flat rate (7.6% of gross for wage income, 5.1% for pension) and 25% of the amount by which gross exceeds 99,650 kr. That second limb is the "25-prosentregelen", and it is what stops a raise across the threshold from cutting take-home pay.
Step 6: Add the three taxes, and subtract from gross for net income. Net monthly income is the annual net divided by twelve.
The marginal rate the calculator reports is the sum of three parts: 22% if alminnelig inntekt is positive, plus the trinnskatt rate of the bracket you are standing in, plus the trygdeavgift rate if gross exceeds 99,650 kr.
Worked Example
A wage earner on 600,000 kr with no other deductions, income year 2026.
Step 1: Minstefradrag: 46% of gross, capped. 0.46 x 600,000 = 276,000, which exceeds the cap, so the deduction is 95,700 kr
Step 2: Alminnelig inntekt. 600,000 - 95,700 - 114,540 = 389,760 kr
Step 3: Tax on general income at 22%. 389,760 x 0.22 = 85,747.20 kr
Step 4a: Trinnskatt, step 1 (226,100 to 318,300 at 1.7%). 92,200 x 0.017 = 1,567.40 kr
Step 4b: Trinnskatt, step 2 (318,300 to 600,000 at 4.0%). 281,700 x 0.04 = 11,268.00 kr
Step 4c: Total trinnskatt. 1,567.40 + 11,268.00 = 12,835.40 kr
Step 5a: Trygdeavgift at the flat wage rate. 600,000 x 0.076 = 45,600.00 kr
Step 5b: The 25% relief cap, for comparison. (600,000 - 99,650) x 0.25 = 125,087.50 kr
Step 5c: Take the smaller of the two. min(45,600.00, 125,087.50) = 45,600.00 kr, so the flat rate applies in full
Step 6: Total tax. 85,747.20 + 12,835.40 + 45,600.00 = 144,182.60 kr
Step 7: Net income. 600,000 - 144,182.60 = 455,817.40 kr
Step 8: Net monthly. 455,817.40 / 12 = 37,984.78 kr
Effective rate: 144,182.60 / 600,000 = 24.03%. Marginal rate: 22% + 4% + 7.6% = 33.60%.
What does this calculator not account for?
Skatteetaten's English pages were serving stale 2025 figures. As at the verification date, skatteetaten.no/en/rates/ still returned a personfradrag of 108,550 kr and minstefradrag caps of 92,000 / 73,150 kr, while the Norwegian pages with an explicit ?year=2026 returned the 114,540 kr and 95,700 / 75,400 kr figures used here. If you check this calculator against the English site you will see a mismatch. It is the site's, not the arithmetic's. Read the Norwegian pages, or select 2026 explicitly.
Only two income types exist here: wage and pension. The 10.8% trygdeavgift rate for other self-employment income (naeringsinntekt) is defined in the underlying module but is not selectable from this calculator, so a sole trader's contribution will be understated.
No wealth tax (formuesskatt). Nothing about assets, debt or valuation discounts enters this figure.
No capital or share income. Dividends and share gains carry the 1.72 oppjusteringsfaktor and are taxed separately; they are not part of this calculation.
Other deductions are treated as a single lump sum against alminnelig inntekt only. The calculator does not test whether a claim qualifies, apply the reisefradrag's own floor and per-kilometre rates, or model the BSU credit, which is a credit against tax rather than a deduction from income.
No municipal variation and no Finnmark or Nord-Troms adjustment. The 22% general rate here is the standard national one.
Nothing is withheld or reconciled. This is an annual liability, not a skattekort simulation, so it takes no account of your withholding table, the half-tax month in December or your resulting refund or bill.
What mistakes do people make with this?
Assuming a deduction saves you your marginal rate. It saves you 22%, always. At 600,000 kr your marginal rate is 33.60%, but a 10,000 kr deduction is worth 2,200 kr, not 3,360 kr.
Reading the trinnskatt table as though it applied after deductions. It does not. Trinnskatt and trygdeavgift are charged on gross personinntekt, so your minstefradrag has no effect on either of them.
Thinking the personfradrag ends the tax-free zone. It does not. The calculator reports the highest income with no tax at all as 99,650 kr, the trygdeavgift threshold, because trygdeavgift starts biting well before the allowances are exhausted.
Treating the 25-prosentregelen as a rate. It is a ceiling, not a rate. It binds only just above 99,650 kr; by 600,000 kr the flat 7.6% is far below it and the cap is irrelevant.
Applying the wage minstefradrag to a pension. Pension income uses 40% capped at 75,400 kr and a 5.1% trygdeavgift rate, but exactly the same trinnskatt scale.
Frequently Asked Questions
How much tax do I pay on 600,000 kr in Norway in 2026?
What is the marginal tax rate on a 600,000 kr salary?
At what income does Norwegian tax start?
Why does my marginal rate jump at around 208,000 kr?
Is a 10,000 kr union subscription worth more to a high earner?
How is a pension taxed differently?
Sources
- Skatteetaten, personfradrag 2026 (114,540 kr): skatteetaten.no/satser/personfradrag
- Skatteetaten, minstefradrag 2026 (46% capped at 95,700 kr for wage; 40% capped at 75,400 kr for pension): skatteetaten.no/satser/minstefradrag
- Skatteetaten, trygdeavgift 2026 (7.6% wage, 5.1% pension, lower threshold 99,650 kr, never more than 25% of income above the threshold): skatteetaten.no/satser/trygdeavgift
- Skatteetaten, bracket tax (trinnskatt) 2026: skatteetaten.no/en/rates/bracket-tax
- Skatteetaten, Forskuddsutskrivingen 2026: skatteetaten.no/en/rettskilder/type/uttalelser/uttalelser/forskuddsutskrivingen-2026