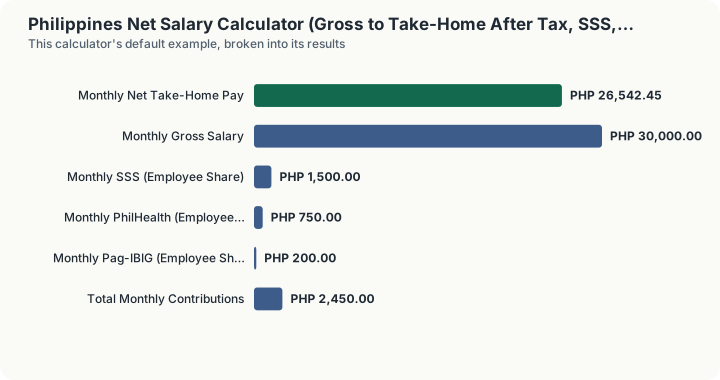
Quick Answer: On a monthly gross salary of PHP 30,000 with no other benefits, your net take-home pay is PHP 26,542.45 a month. That is PHP 2,450 of mandatory contributions (PHP 1,500 SSS, PHP 750 PhilHealth, PHP 200 Pag-IBIG) and PHP 1,007.55 of withholding tax. Across a full year you also receive PHP 30,000 of 13th month pay tax free, for annual net pay of PHP 348,510.00.
What does this calculator do?
A Philippine payslip subtracts four things from gross pay, and they come off in a fixed order that matters. Three of them are mandatory social contributions: SSS, PhilHealth and Pag-IBIG. The fourth is the BIR withholding tax. The contributions are deducted first, and only what remains is exposed to tax. That ordering is worth understanding, because it means every peso of contribution costs you less than a peso of take-home: it also shrinks your tax base.
This calculator runs the whole chain from one figure. Enter your monthly gross salary and it derives each contribution from its own published schedule, subtracts them, reads the remainder against the BIR withholding table, and reports what actually lands in your account.
It then does something a simple payslip calculator does not: it reconciles the month against the year. Your employer withholds tax monthly using a table built on the assumption that your current salary runs for all twelve months. Your actual liability is settled annually on the graduated TRAIN Law schedule. When those two disagree, and they almost always disagree slightly, the difference surfaces in December as a refund or an extra deduction. This page shows both numbers and the gap between them.
The 13th month pay is folded in as well, because it is the single largest reason Philippine annual take-home is higher than twelve times monthly take-home. Presidential Decree No. 851 makes it mandatory, and the first PHP 90,000 of it and your other bonuses combined is excluded from income tax entirely.
How is this calculated?
1. Compute each mandatory contribution from its own schedule. The three run on unrelated rules. SSS assigns your pay to a Monthly Salary Credit rounded to the nearest PHP 500 band and clamped between PHP 5,000 and PHP 35,000, splits that credit at PHP 20,000 between the regular programme and the Mandatory Provident Fund, and charges the employee 5% of both parts. PhilHealth clamps your salary between an income floor and ceiling and charges 5%, split evenly with your employer. Pag-IBIG caps your pay at the PHP 10,000 Maximum Fund Salary and charges 2% above a PHP 1,500 fund salary.
Contributions = SSS_ee + PhilHealth_ee + Pag-IBIG_ee
2. Subtract contributions and non-taxable benefits to reach the tax base.
Monthly Taxable = max(Gross − Contributions − Non-Taxable Benefits, 0)
3. Read that figure against the BIR monthly withholding table. RR 11-2018 Annex "E" gives each bracket a prescribed tax at its floor plus a marginal rate on the excess above it.
Withholding = Base Tax + (Monthly Taxable − Bracket Floor) × Marginal Rate
4. Net monthly pay is gross less contributions less withholding. Non-taxable benefits do not appear here: they reduced the tax base in step 2, but this calculator does not add them to your gross salary.
Monthly Net = Gross − Contributions − Withholding
5. Compute the 13th month pay and split the benefit pot. Under PD 851 the benefit is one twelfth of basic salary earned in the calendar year, so a partial year produces a proportionally smaller benefit. That amount plus your other bonuses is then measured against the PHP 90,000 exclusion ceiling.
13th Month = (Monthly Gross × Months Worked)/12
Taxable Excess = max(13th Month + Other Bonuses − 90,000, 0)
6. Build annual taxable income and apply the graduated schedule. The monthly tax base is scaled by the months actually worked, and the taxable excess of your benefits is added on top.
Annual Taxable = Monthly Taxable × Months Worked + Taxable Excess
The TRAIN Law schedule in NIRC Sec. 24(A)(2)(a) then applies in the same base-plus-marginal shape as the withholding table, but on annual figures.
7. Reconcile the year against what was withheld.
Adjustment = Withholding × Months Worked − Annual Tax Due
A positive adjustment means you were over-withheld and are owed a refund. Annual net pay is annual gross, less annual contributions, less the annual tax actually due.
Worked Example
Scenario: PHP 30,000 a month, twelve months, no bonuses.
Step 1: Compute the three contributions.
SSS assigns a Monthly Salary Credit of PHP 30,000, which splits into PHP 20,000 of regular credit and PHP 10,000 of Mandatory Provident Fund credit. The employee pays 5% of each:
20,000 × 5% = 1,000; 10,000 × 5% = 500
PhilHealth: PHP 30,000 sits inside the income floor and ceiling, so 5% of it is PHP 1,500, halved with the employer to PHP 750. Pag-IBIG: the fund salary is capped at PHP 10,000, and 2% of that is PHP 200.
Total monthly contributions: PHP 2,450.00
Step 2: Reach the monthly tax base.
30,000 − 2,450 − 0 = 27,550
Monthly taxable compensation: PHP 27,550.00
Step 3: Apply the BIR monthly withholding table.
PHP 27,550 falls in the column running from PHP 20,833 to PHP 33,332, which carries no base tax and a 15% marginal rate.
(27,550 − 20,833) × 15% = 6,717 × 15% = 1,007.55
Monthly withholding tax: PHP 1,007.55
Step 4: Net monthly pay.
30,000 − 2,450 − 1,007.55 = 26,542.45
Monthly net take-home: PHP 26,542.45
Step 5: The 13th month pay.
Basic salary earned in the year is PHP 360,000, so the benefit is PHP 30,000. That is well under the PHP 90,000 ceiling, so all of it is tax free and the taxable excess is zero.
Step 6: Annual taxable income and the tax actually due.
27,550 × 12 + 0 = 330,600
That falls in the graduated bracket running from PHP 250,000 to PHP 400,000, which carries no base tax and a 15% rate on the excess:
(330,600 − 250,000) × 15% = 80,600 × 15% = 12,090.00
Annual income tax due: PHP 12,090.00
Step 7: Reconcile, and total up the year.
Withheld across the year: PHP 1,007.55 x 12 = PHP 12,090.60. Against PHP 12,090.00 actually due, that is PHP 0.60 over-withheld. The gap is not a rounding artifact in this calculator: the monthly table's PHP 20,833 exempt threshold annualizes to PHP 249,996, four pesos short of the statutory PHP 250,000, and 15% of those four pesos is exactly PHP 0.60.
Annual gross is PHP 360,000 of salary plus PHP 30,000 of 13th month pay, or PHP 390,000. Annual contributions are PHP 29,400.
390,000 − 29,400 − 12,090 = 348,510
Annual net pay: PHP 348,510.00
What does this calculator not account for?
- The PhilHealth premium rate for 2026 and later. This is the most consequential limitation on this page. PhilHealth Circular No. 2019-0009 published a year by year premium ramp whose final band is labelled "2024 to 2025": a 5.00% rate, a PHP 10,000 income floor and a PHP 100,000 income ceiling. No PhilHealth circular extending or replacing that schedule for calendar year 2026 could be retrieved when this page was built. The figures used here are the last published values, not a confirmed current schedule. Note also that the ramp was suspended once before, staying at 4% through 2023 despite the published table showing 4.5%, so a published schedule is not a guarantee of what is collected.
- The Pag-IBIG schedule was not read from the issuing agency. HDMF Circular No. 460 sets the 1%/2% employee rates and the PHP 10,000 Maximum Fund Salary used here, but pagibigfund.gov.ph sat behind a browser verification interstitial when this page was built, so the circular text was read from a hosted scan of the signed document rather than from HDMF directly.
- The distinction between basic salary and gross pay. This calculator applies one salary figure to everything. In a real payroll, PhilHealth and the 13th month pay are computed on basic salary, while other elements may run on a broader gross. If your allowances are substantial, the two bases diverge.
- Allowances, overtime, night differential and holiday premiums. Variable pay is not modelled. Overtime and holiday premium pay are taxable compensation and would raise both the withholding and the annual tax, but they do not enter the 13th month pay computation, which runs on basic salary only.
- The de minimis benefit limits. The non-taxable benefits field accepts whatever you enter. It does not check your figure against the per-item ceilings the BIR prescribes for rice subsidy, uniform allowance, medical assistance and the rest. Amounts above those ceilings spill into the PHP 90,000 benefit pot rather than being excluded outright.
- Substituted filing and multiple employers. The annual figures assume a single employer for the whole period. If you changed jobs during the year, your new employer must consolidate your previous employer's BIR Form 2316 to annualize correctly, and you may fall outside substituted filing.
- Semi-monthly and other payroll frequencies. This page uses the monthly Annex "E" table. If you are paid twice a month, the withholding tax calculator applies the semi-monthly table instead.
- Voluntary deductions. Salary loans, company HMO share, union dues and Pag-IBIG MP2 savings are real reductions in take-home pay and none of them are modelled here.
What mistakes do people make with this?
- Multiplying monthly net pay by twelve. This understates annual take-home, usually by close to a full month of pay, because it ignores the 13th month benefit and the exclusion that makes it tax free.
- Expecting monthly withholding to equal the annual tax. It does not, and it is not supposed to. The monthly table is an estimate built on an assumption of level pay all year. Anyone who joined mid-year, left mid-year, received a raise, or earned a bonus will see a December adjustment.
- Assuming a mid-year hire is taxed on their monthly rate. Six months at PHP 30,000 produces PHP 165,300 of annual taxable income, below the PHP 250,000 exempt threshold, so the entire PHP 6,045.30 withheld across those six months is refundable. The monthly table cannot know this while it is running.
- Treating the PHP 90,000 ceiling as applying to 13th month pay alone. It is a single combined ceiling covering your 13th month pay and other benefits together. A modest 13th month plus a large performance bonus can breach it easily.
- Forgetting that contributions cut the tax base. People often add contributions and tax together as though both were fixed costs. Raising a contribution reduces taxable pay, so its net cost to take-home is less than its face value.
- Reading contribution ceilings as proportional. All three contributions cap out. Above a PHP 35,000 salary credit, a PHP 100,000 PhilHealth ceiling and a PHP 10,000 Pag-IBIG fund salary, the peso amounts stop growing, so contributions fall as a share of pay as salary rises.
Frequently Asked Questions
How do I compute net salary in the Philippines?
Are SSS, PhilHealth and Pag-IBIG deducted before income tax?
Why is my December pay different?
Is 13th month pay taxable?
What salary is tax free in the Philippines?
Do bonuses change my monthly take-home?
How much is deducted from a PHP 30,000 salary?
Sources
- Republic Act No. 10963, the Tax Reform for Acceleration and Inclusion (TRAIN) Act, amending NIRC Sec. 24(A)(2)(a) to set the graduated individual income tax schedule effective 1 January 2023 and onwards, and amending Sec. 32(B)(7)(e) to set the PHP 90,000 exclusion ceiling for 13th month pay and other benefits. (read 31 August 2026) lawphil.net/statutes/repacts/ra2017/ra_10963_2017.html
- Bureau of Internal Revenue, Revenue Regulations No. 11-2018, Annex "E", "Revised Withholding Tax Table", effective 1 January 2023 and onwards. The monthly table columns used here were transcribed from the BIR document. bir-cdn.bir.gov.ph/local/pdf/Annex%20E%20RR%2011-2018.pdf (read 31 August 2026)
- Social Security System Circular No. 2024-006, "Schedule of SSS Contributions Effective January 2025", issued under Republic Act No. 11199 (Social Security Act of 2018). Sets the 15% contribution rate with a 10%/5% employer/employee split, a PHP 5,000 minimum and PHP 35,000 maximum Monthly Salary Credit, and the PHP 20,000 regular programme cap above which contributions fund the Mandatory Provident Fund. sss.gov.ph/wp-content/uploads/2024/12/CI-2024-006-Publication.pdf (read 31 August 2026)
- PhilHealth Circular No. 2019-0009, "Premium Contribution Schedule in the National Health Insurance Program Pursuant to R.A. No. 11223 (Universal Health Care Act)". The published schedule's final band is "2024 to 2025" at a 5.00% rate, a PHP 10,000 income floor and a PHP 100,000 income ceiling. It does not extend to calendar year 2026. philhealth.gov.ph/partners/employers/ContributionTable_v2.pdf (read 31 August 2026)
Also consulted: Presidential Decree No. 851 (1975), requiring 13th month pay of one twelfth of basic salary earned within a calendar year, payable not later than 24 December. The original PHP 1,000 monthly salary ceiling was removed by Memorandum Order No. 28 (1986), extending the benefit to all rank-and-file employees. (read 31 August 2026); HDMF Circular No. 460, setting Pag-IBIG employee rates of 1.0% at a fund salary of PHP 1,500 and below and 2.0% above it, with a Maximum Fund Salary of PHP 10,000 under Section 7 of Republic Act No. 9679. Sourcing caveat: pagibigfund.gov.ph was behind a browser verification interstitial on 31 August 2026 and the circular text was read from a hosted scan of the signed document rather than from the issuing agency.