How much is the RAP student loan payment at each income?
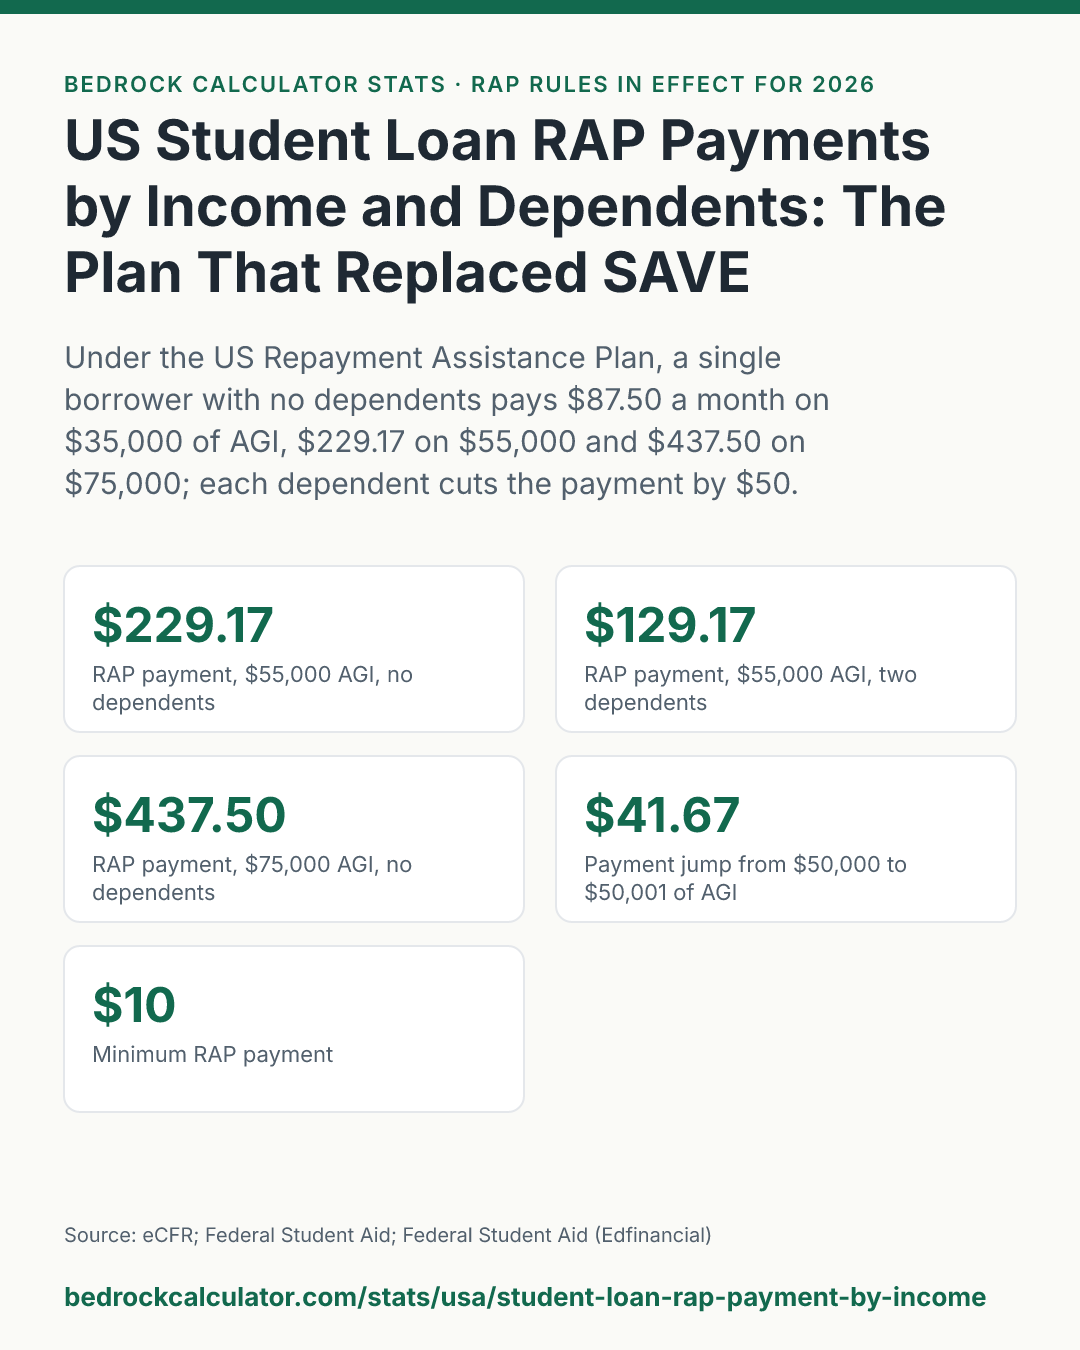
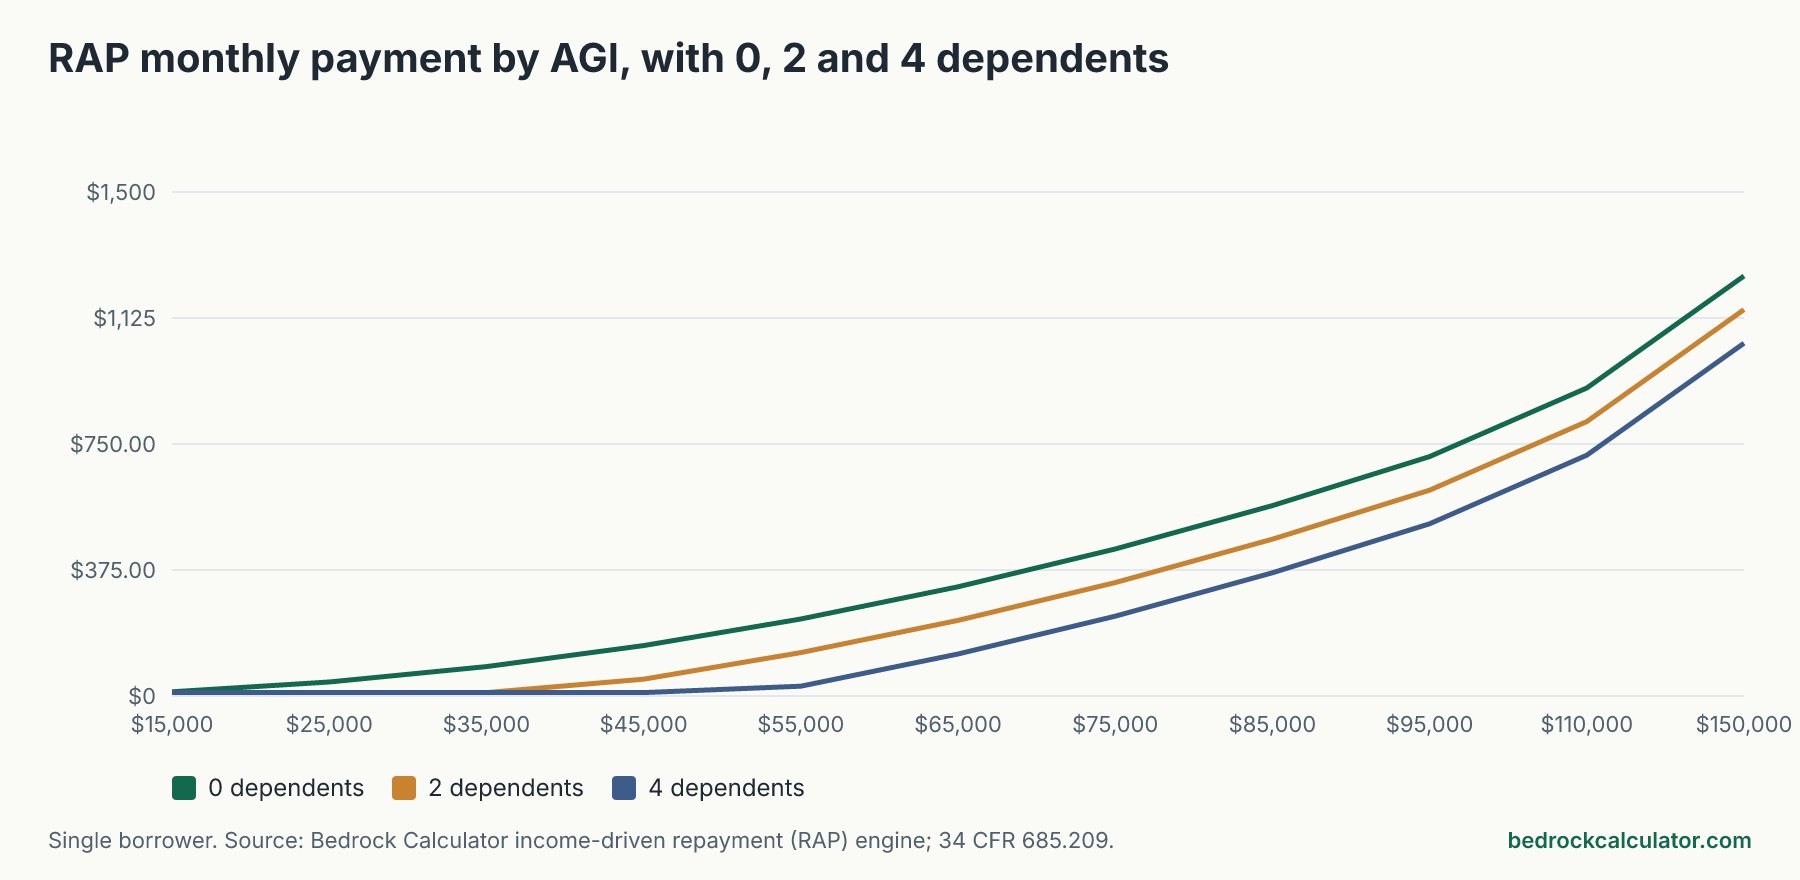
The Repayment Assistance Plan, or RAP, is the US federal income-driven plan that launched in July 2026 after the SAVE plan ended. A single borrower with no dependents pays $87.50 a month on $35,000 of adjusted gross income, $229.17 on $55,000, $437.50 on $75,000 and $1,250.00 on $150,000.
Each dependent you claim on your tax return takes $50 off the monthly payment, and nobody pays less than $10. At $55,000 of AGI, two dependents bring the payment down to $129.17.
What happened to SAVE
Federal Student Aid says a court order ended the SAVE plan and that anyone who was on it has to pick a different repayment plan. If you don't choose, you'll be placed in a fixed-payment plan. For most borrowers the choice now comes down to RAP or the older Income-Based Repayment plan, plus the standard fixed plans.
If you've bookmarked an old SAVE calculator, its figures no longer apply to anything you can sign up for. The income-driven repayment calculator on this site now computes RAP, and every figure on this page comes from it.
How RAP works out your payment
RAP is simpler than the plans it replaces. There's no poverty-line deduction and no family-size table. The federal regulation sets it up in three steps:
- Find your band. Your AGI decides the share. It's 1.0% of AGI in the first band, from just over $10,000 up to $20,000, rising one point for every extra $10,000, up to 10.0% of AGI above $100,000. At $10,000 or less the yearly base payment is a flat amount that works out to $10 a month.
- Divide by 12. That share of your whole AGI, divided by 12, is your base monthly payment.
- Take off $50 per dependent, but never go below $10 a month.
If you're married and file jointly, your spouse's income counts too. File separately and only your own AGI is used.
Payments at every income and family size
Sort by any column. The share column is the band your AGI falls in. The last column is explained further down.
RAP monthly student loan payment by AGI and number of dependents (US, 2026)
Download CSVPayment from the income-driven repayment calculator. Interest waived is for a $40,000 balance at 6.5% with no dependents.
| $15,000 | 1.0% | $12.50 | $10.00 | $10.00 | $10.00 | $10.00 | $204.17 |
| $25,000 | 2.0% | $41.67 | $10.00 | $10.00 | $10.00 | $10.00 | $175.00 |
| $35,000 | 3.0% | $87.50 | $37.50 | $10.00 | $10.00 | $10.00 | $129.17 |
| $45,000 | 4.0% | $150.00 | $100.00 | $50.00 | $10.00 | $10.00 | $66.67 |
| $55,000 | 5.0% | $229.17 | $179.17 | $129.17 | $79.17 | $29.17 | $0.00 |
| $65,000 | 6.0% | $325.00 | $275.00 | $225.00 | $175.00 | $125.00 | $0.00 |
| $75,000 | 7.0% | $437.50 | $387.50 | $337.50 | $287.50 | $237.50 | $0.00 |
| $85,000 | 8.0% | $566.67 | $516.67 | $466.67 | $416.67 | $366.67 | $0.00 |
| $95,000 | 9.0% | $712.50 | $662.50 | $612.50 | $562.50 | $512.50 | $0.00 |
| $110,000 | 10.0% | $916.67 | $866.67 | $816.67 | $766.67 | $716.67 | $0.00 |
| $150,000 | 10.0% | $1,250.00 | $1,200.00 | $1,150.00 | $1,100.00 | $1,050.00 | $0.00 |
The dependent deduction matters most at low and middle incomes. At $35,000 of AGI, one dependent cuts the payment from $87.50 to $37.50, and two hit the $10 floor. At $150,000 the same two dependents only take it from $1,250.00 to $1,150.00. In our grid, 13 of the combinations land on the $10 minimum.
The band edges are cliffs
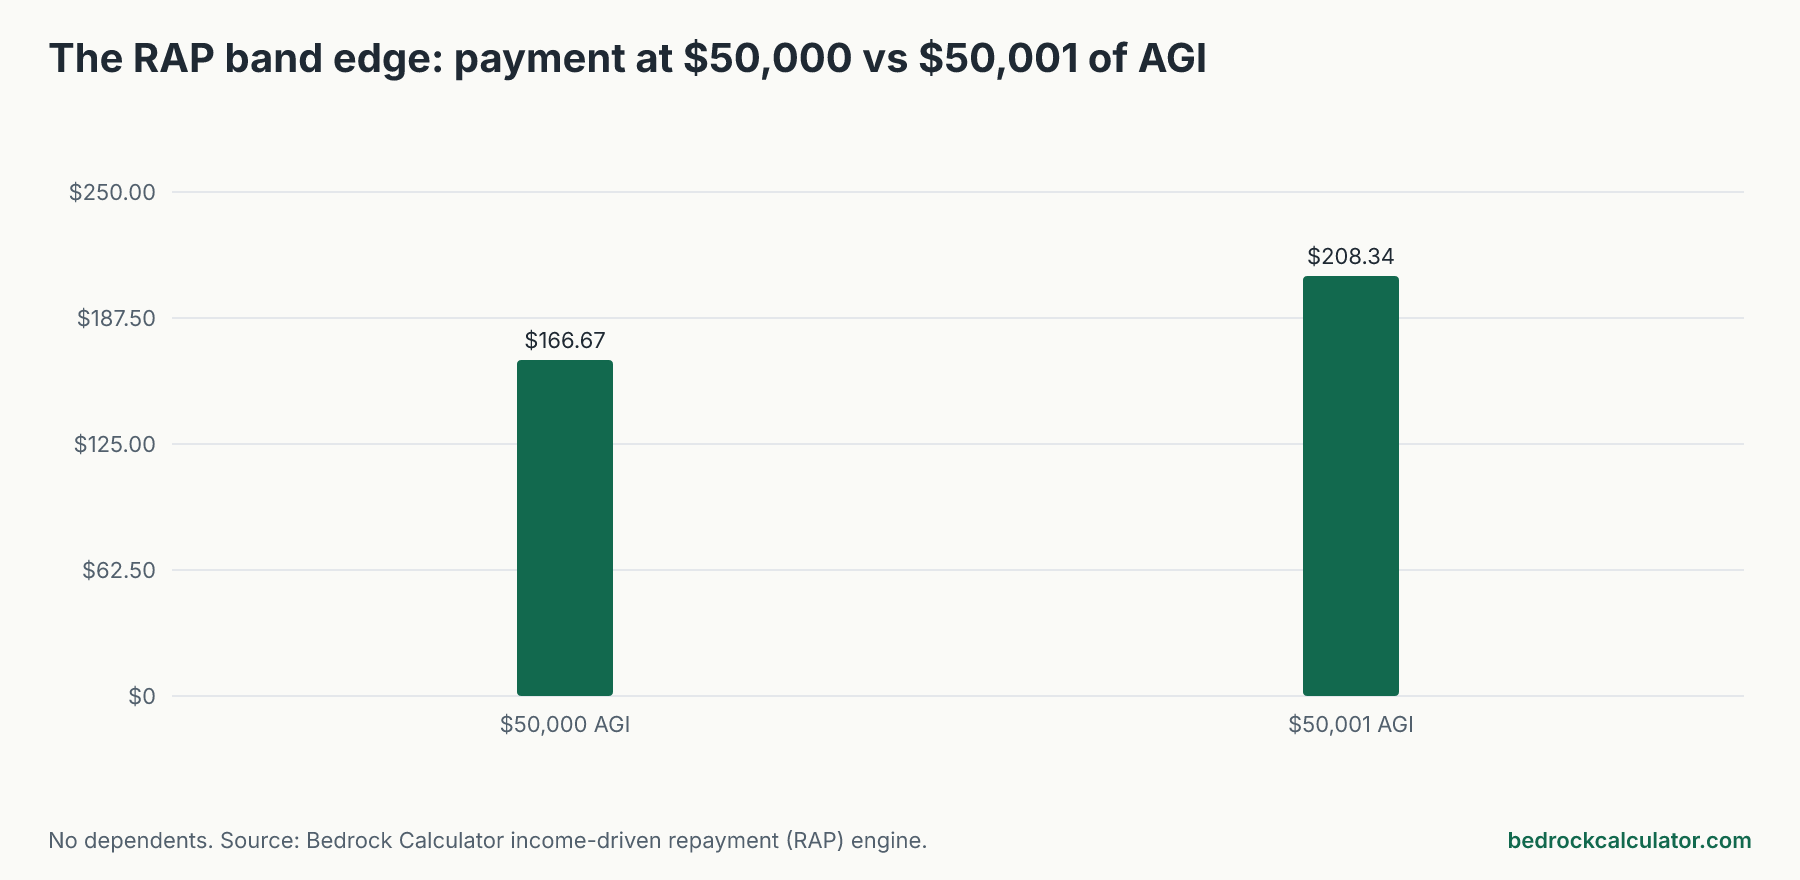
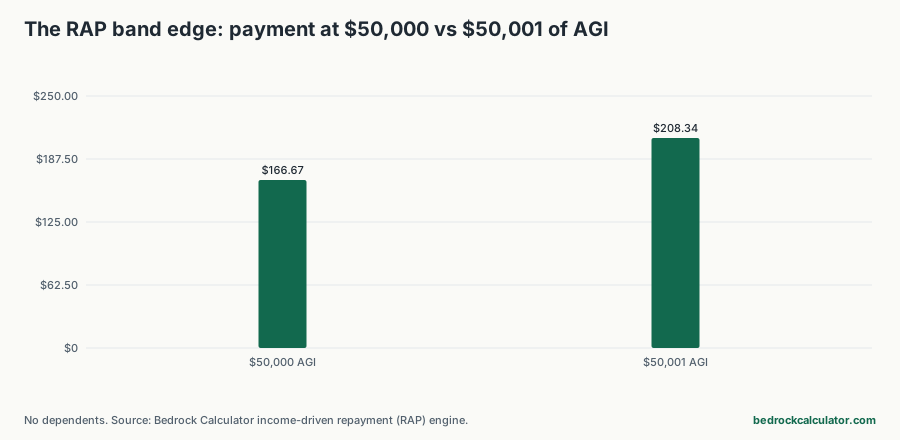
RAP doesn't phase in its percentages the way tax brackets do. When your AGI crosses into a new band, the higher share applies to every dollar, not just the dollars above the line. At exactly $50,000 of AGI you're in the 4.0% band and pay $166.67 a month with no dependents. One dollar more puts you in the 5.0% band and the payment becomes $208.34, a jump of $41.67 a month or $500.04 over a year.
If your AGI sits just above a band edge, a pre-tax contribution to a 401(k), 403(b) or traditional IRA lowers AGI and can drop you back a band. The payment is recalculated each year from your latest return, so the effect shows up when you recertify.
Your balance doesn't grow from unpaid interest
RAP has two protections worth knowing about. First, if your on-time payment doesn't cover the month's interest, the rest isn't charged to you. Take a $40,000 balance at 6.5%: about $216.67 of interest builds up each month. A borrower with no dependents at $45,000 of AGI pays $150.00, so $66.67 of that interest is waived every month. By $55,000 of AGI the payment covers it all, which is what the last column of the table shows.
Second, the regulation says that when an on-time payment cuts your principal by less than a set monthly amount, the government makes up the difference, capped at the size of your payment. The calculator doesn't model that match, so in practice your balance falls a little faster than a plain interest calculation suggests. RAP forgives whatever is left after 360 qualifying monthly payments, which is 30 years.
How we worked out these numbers
We ran the income-driven repayment calculator at eleven AGIs from $15,000 to $150,000, with zero to four dependents, filing single. For the interest column we used a $40,000 balance at 6.5%, inputs we chose to show the waiver, not a typical borrower. We checked the calculator's formula against the Department of Education's regulation, 34 CFR 685.209, which sets the AGI bands, the $50 dependent reduction, the $10 minimum and the interest rule.
What the calculator leaves out:
- Eligibility. Not every federal loan qualifies. Parent PLUS loans, and consolidation loans that repaid one, can't use RAP. The calculator doesn't check your loans.
- Income-Based Repayment. IBR uses a different formula based on income above a poverty-line threshold. Borrowers whose loans were all made before July 1, 2026 may have both options and should compare.
- Married couples who both have loans. The payment is split between spouses' loans when joint income is used. That adjustment isn't modeled.
- Forgiveness timing and the principal match, as described above.
- Changes over time. The payment is fixed at today's AGI and family. A raise, a new child or a change in filing status changes it at your next recertification.
What about Public Service Loan Forgiveness?
If you work for a government or nonprofit employer, check whether your payments count toward PSLF with your servicer. The PSLF calculator projects what's left after 120 qualifying payments, but it lets the balance grow when the payment falls short of interest, which is how some older plans worked.
Under RAP that interest is waived instead, so for a RAP borrower its forgiven-balance figure will run high.
Run your own numbers
Enter your AGI, dependents, balance and rate in the income-driven repayment calculator to get your RAP payment and how much interest it covers. To see what a standard fixed plan would cost instead, use the student loan calculator. Federal Student Aid's Repayment Calculator at StudentAid.gov compares the plans you qualify for using your actual loans.