How much of a US mortgage payment is interest each year?
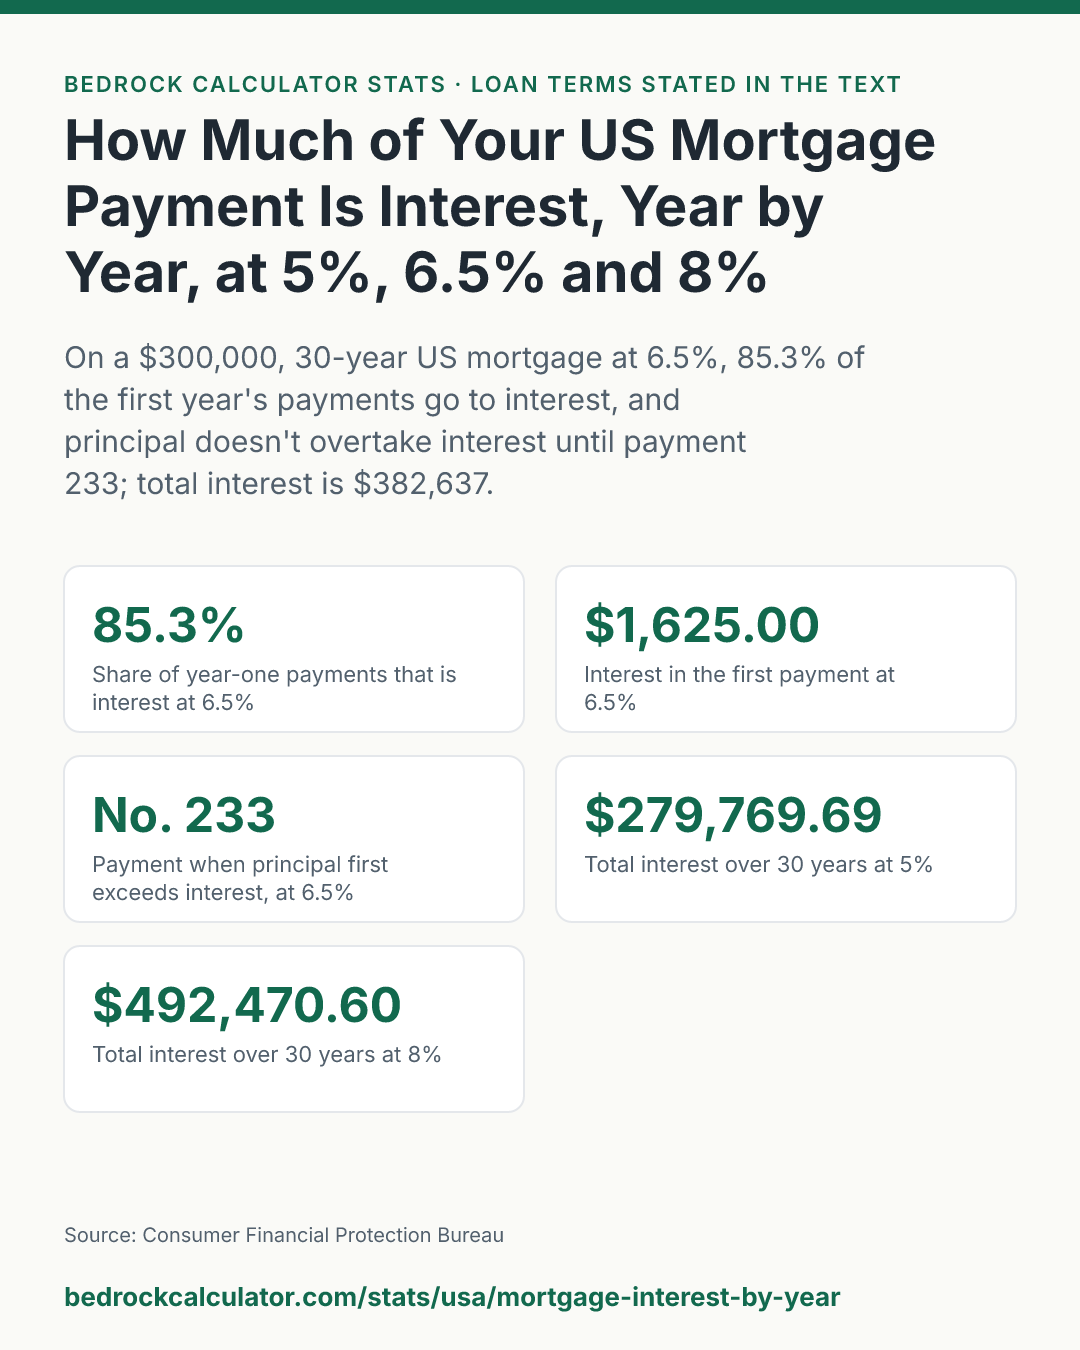
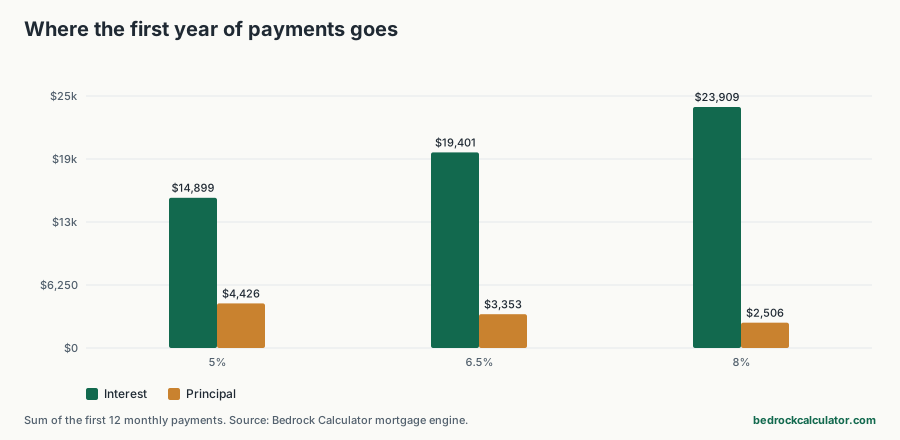
On a $300,000, 30-year fixed US mortgage at 6.5%, 85.3% of everything you pay in the first year is interest. Your first payment of $1,896.20 includes $1,625.00 of interest and just $271.20 of principal. Principal doesn't take the larger share of a payment until payment 233, well into year 20.
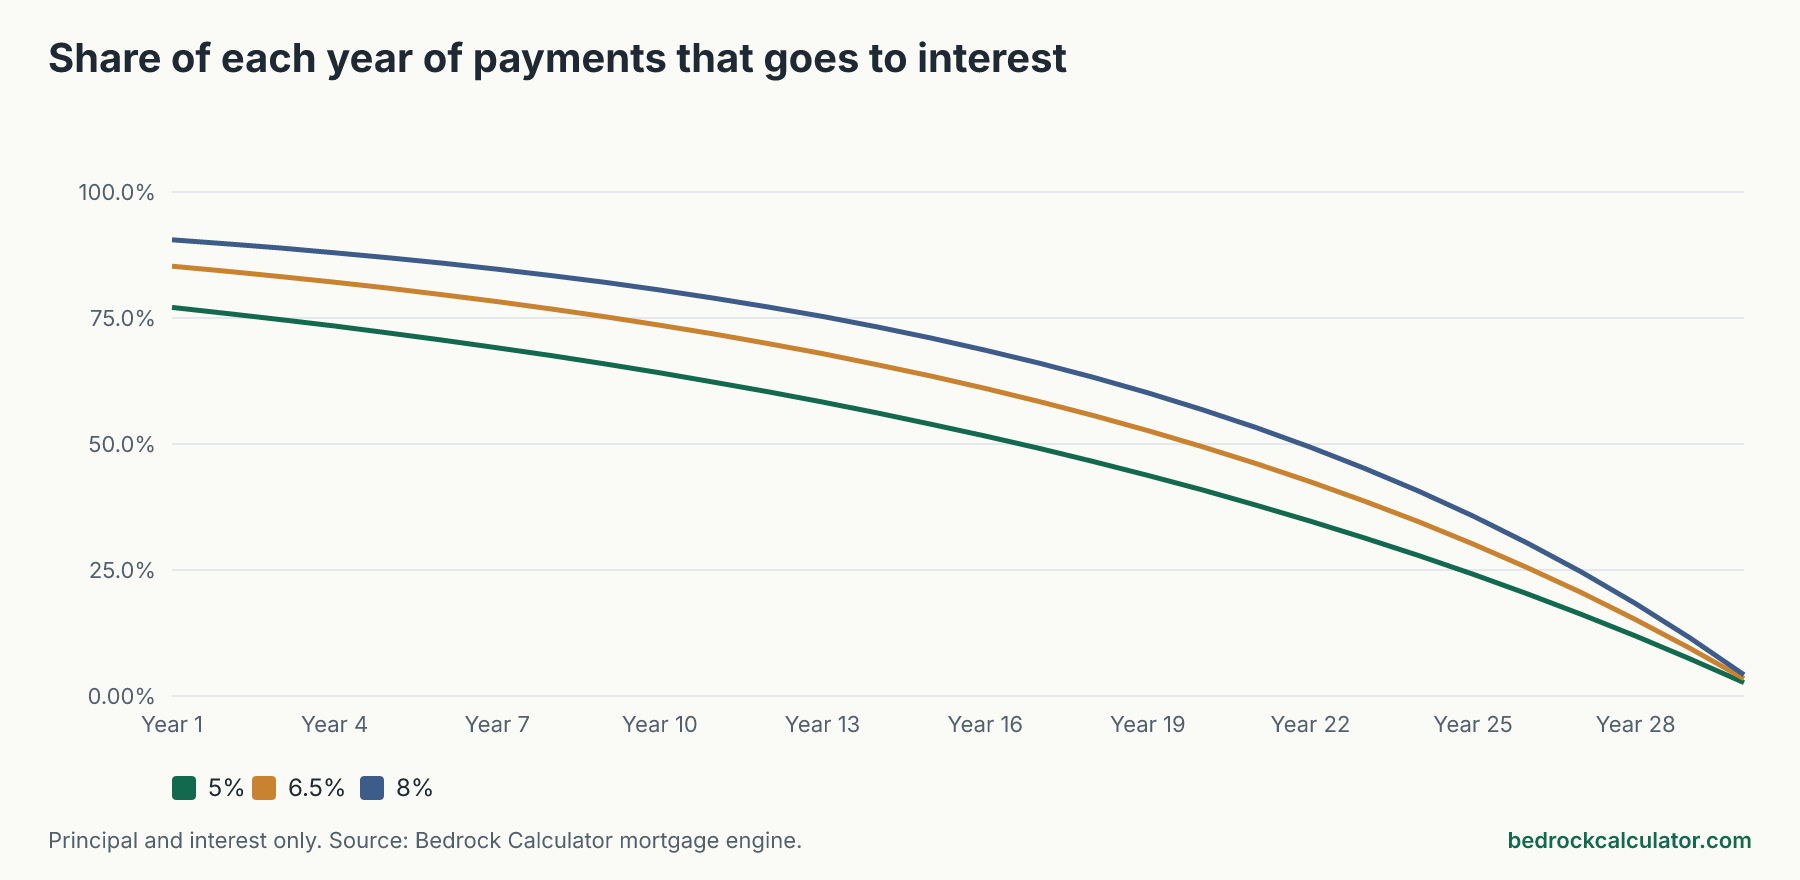
The rate changes the picture a lot. At 5% the first-year interest share is 77.1%; at 8% it's 90.5%. Over the full term, the 8% loan costs $212,700.91 more in interest than the 5% one.
How we worked out these numbers
We ran the mortgage calculator on this site three times, once at each rate: 5%, 6.5% and 8%. Each run uses a $375,000 home with 20% down, so the loan is exactly $300,000 and no mortgage insurance applies. The term is 30 years and there is no extra principal.
The calculator builds the full payment schedule month by month. Each month, interest is the remaining balance times one twelfth of the annual rate, rounded to the cent, and whatever is left of the fixed payment reduces the balance. We added up the 12 payments in each loan year to get the yearly totals.
Everything here is principal and interest only. Property tax, homeowners insurance and HOA dues are often paid along with the mortgage, but none of them reduce what you owe, so they're left out of the split.
Why the early years are mostly interest
The interest on each payment depends on how much you still owe. In month one you owe the full $300,000, so interest is at its highest. The payment is fixed, so the more that goes to interest, the less is left to pay down the loan.
As the balance falls, interest shrinks a little each month and principal grows by the same amount. The change is slow at first because the balance barely moves. That's why the lines in the chart above start nearly flat and then bend downward faster in the later years. Our guide on why early loan payments are mostly interest walks through the math step by step.
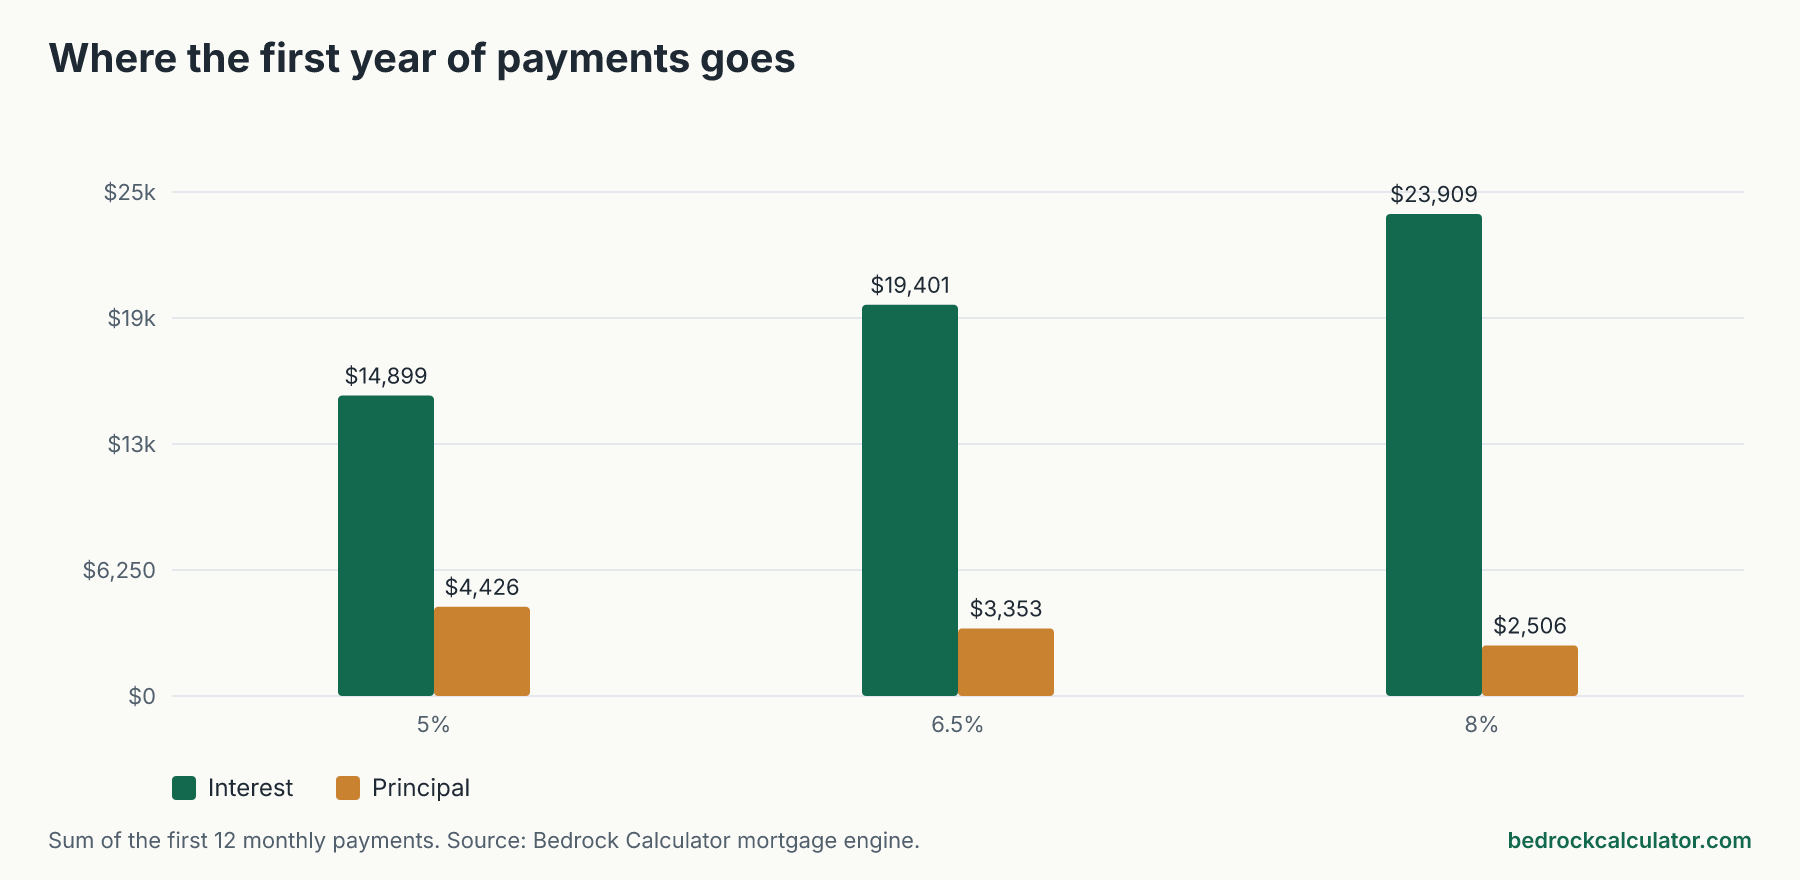
In the first year at 6.5% you pay $19,401.28 in interest and $3,353.12 in principal. At 8% the split is $23,909.45 to $2,506.03. A higher rate doesn't just raise the payment; it also slows how fast you build equity.
Year by year, all three rates
Sort by any column. The share columns are the percent of that year's principal and interest that went to the lender as interest.
Interest paid each year on a $300,000, 30-year mortgage
Download CSVPrincipal and interest only. Sums of the 12 monthly payments in each loan year, from the mortgage calculator schedule.
| 1 | $14,899.49 | 77.1% | $19,401.28 | 85.3% | $23,909.45 | 90.5% | $296,646.88 |
| 2 | $14,673.04 | 75.9% | $19,176.72 | 84.3% | $23,701.43 | 89.7% | $293,069.20 |
| 3 | $14,435.00 | 74.7% | $18,937.11 | 83.2% | $23,476.18 | 88.9% | $289,251.91 |
| 4 | $14,184.80 | 73.4% | $18,681.46 | 82.1% | $23,232.22 | 87.9% | $285,178.97 |
| 5 | $13,921.80 | 72.0% | $18,408.69 | 80.9% | $22,968.01 | 86.9% | $280,833.26 |
| 6 | $13,645.31 | 70.6% | $18,117.65 | 79.6% | $22,681.87 | 85.9% | $276,196.51 |
| 7 | $13,354.73 | 69.1% | $17,807.10 | 78.3% | $22,371.98 | 84.7% | $271,249.21 |
| 8 | $13,049.23 | 67.5% | $17,475.78 | 76.8% | $22,036.39 | 83.4% | $265,970.59 |
| 9 | $12,728.14 | 65.9% | $17,122.27 | 75.2% | $21,672.90 | 82.0% | $260,338.46 |
| 10 | $12,390.60 | 64.1% | $16,745.08 | 73.6% | $21,279.27 | 80.6% | $254,329.14 |
| 11 | $12,035.80 | 62.3% | $16,342.61 | 71.8% | $20,852.98 | 78.9% | $247,917.35 |
| 12 | $11,662.84 | 60.3% | $15,913.22 | 69.9% | $20,391.29 | 77.2% | $241,076.17 |
| 13 | $11,270.81 | 58.3% | $15,455.04 | 67.9% | $19,891.27 | 75.3% | $233,776.81 |
| 14 | $10,858.71 | 56.2% | $14,966.20 | 65.8% | $19,349.79 | 73.3% | $225,988.61 |
| 15 | $10,425.53 | 53.9% | $14,444.56 | 63.5% | $18,763.33 | 71.0% | $217,678.77 |
| 16 | $9,970.19 | 51.6% | $13,888.07 | 61.0% | $18,128.20 | 68.6% | $208,812.44 |
| 17 | $9,491.55 | 49.1% | $13,294.28 | 58.4% | $17,440.38 | 66.0% | $199,352.32 |
| 18 | $8,988.43 | 46.5% | $12,660.70 | 55.6% | $16,695.42 | 63.2% | $189,258.62 |
| 19 | $8,459.57 | 43.8% | $11,984.71 | 52.7% | $15,888.67 | 60.1% | $178,488.93 |
| 20 | $7,903.64 | 40.9% | $11,263.45 | 49.5% | $15,014.96 | 56.8% | $166,997.98 |
| 21 | $7,319.28 | 37.9% | $10,493.87 | 46.1% | $14,068.71 | 53.3% | $154,737.45 |
| 22 | $6,705.00 | 34.7% | $9,672.76 | 42.5% | $13,043.94 | 49.4% | $141,655.81 |
| 23 | $6,059.33 | 31.4% | $8,796.67 | 38.7% | $11,934.11 | 45.2% | $127,698.08 |
| 24 | $5,380.59 | 27.8% | $7,861.89 | 34.6% | $10,732.16 | 40.6% | $112,805.57 |
| 25 | $4,667.15 | 24.2% | $6,864.51 | 30.2% | $9,430.44 | 35.7% | $96,915.68 |
| 26 | $3,917.20 | 20.3% | $5,800.35 | 25.5% | $8,020.70 | 30.4% | $79,961.63 |
| 27 | $3,128.90 | 16.2% | $4,664.91 | 20.5% | $6,493.94 | 24.6% | $61,872.14 |
| 28 | $2,300.25 | 11.9% | $3,453.41 | 15.2% | $4,840.46 | 18.3% | $42,571.15 |
| 29 | $1,429.19 | 7.4% | $2,160.76 | 9.5% | $3,049.74 | 11.5% | $21,977.51 |
| 30 | $513.59 | 2.7% | $781.60 | 3.4% | $1,110.41 | 4.2% | $0.00 |
A few points from the table that surprise many borrowers:
- After five years, you've barely dented the loan. At 6.5%, five years of payments total $94,605.26 in interest and only $19,166.74 in principal.
- After ten years, the balance is still high. At 6.5% you'd owe $254,329.14, having repaid $45,670.86 of the original $300,000.
- The last year is almost all principal. In year 30 the interest share falls to 3.4% at 6.5%.
The three loans at a glance
The three loans at a glance
Download CSV| 5% | $1,610.46 | $1,250.00 | 195 | $55,973.06 | $279,769.69 |
| 6.5% | $1,896.20 | $1,625.00 | 233 | $45,670.86 | $382,636.71 |
| 8% | $2,201.29 | $2,000.00 | 257 | $36,825.10 | $492,470.60 |
Total interest over the full term is $279,769.69 at 5%, $382,636.71 at 6.5% and $492,470.60 at 8%. At 6.5% that's 127.5% of the amount borrowed, and at 8% it's 164.2%. The monthly payment difference between 5% and 8% is $590.83, and it adds up over 360 payments.
What this means if you're buying or refinancing
If you plan to move within a few years, most of what you'll have paid is interest, not equity. That matters when you compare the costs of buying against renting. Our rent vs buy break-even analysis looks at that directly.
If you're thinking about extra payments, the early years are where they do the most good. Every extra dollar of principal in year one stops interest from being charged on it for the rest of the loan. See what extra principal each month saves on a 30-year loan.
If you're comparing loan terms, a 15-year loan flips this picture, with far more of each payment going to principal from the start. See 15-year vs 30-year mortgages compared.
What this leaves out
These are fixed-rate loans paid exactly on schedule. The figures don't cover adjustable-rate mortgages, which reset on their own schedule, or interest-only periods. They ignore any mortgage interest tax deduction, which only helps if you itemize. And because the calculator rounds each month's payment and interest to the cent, the final payment is slightly different from the others; our guide on why your final loan payment is different explains that.
Run your own numbers
Put your own loan amount, rate and term into the mortgage calculator to see your full schedule, including tax, insurance and PMI. If you already have a mortgage, the mortgage payoff calculator shows where you stand today and what extra payments would change. For how the fixed payment itself is set, read how a mortgage payment is calculated.