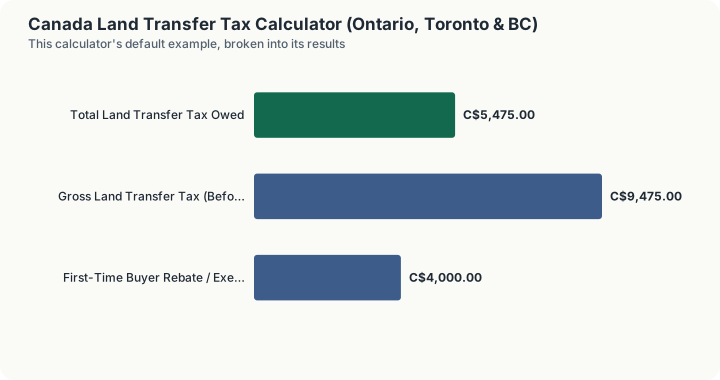
Quick Answer: A first-time buyer purchasing a C$650,000 home in Ontario outside Toronto owes C$9,475 of gross provincial Land Transfer Tax, reduced by the maximum C$4,000 first-time-buyer rebate to a net C$5,475. Inside Toronto, a municipal tax and a separate rebate of up to C$4,475 stack on top. This calculator covers only Ontario (incl. Toronto) and British Columbia.
Overview
Land Transfer Tax (called "Property Transfer Tax" in British Columbia) is a one-time provincial tax owed by the BUYER when real estate changes hands, calculated as a percentage of the purchase price (or fair market value) and due at closing -- it is separate from, and in addition to, annual municipal property tax. Every Canadian province structures this tax differently: some use flat rates, some use marginal brackets like an income tax, some charge a flat registration fee instead of a percentage tax, and cities can layer an ADDITIONAL municipal transfer tax on top of the provincial one.
This calculator focuses on the two best-documented, highest-transaction-volume land transfer tax regimes in Canada: Ontario (which uses a marginal bracket schedule, and where the City of Toronto separately levies its own near-identical Municipal Land Transfer Tax on top) and British Columbia (which uses a similarly-structured but differently-priced marginal bracket schedule, plus an additional surtax on high-value residential property). Both provinces also offer a meaningful first-time home buyer relief program, modeled here in full.
How This Is Calculated
Ontario provincial Land Transfer Tax
Ontario applies marginal rates to the full purchase price, in tiers:
| Portion of Purchase Price | Rate |
|---|---|
| C$0 - C$55,000 | 0.5% |
| C$55,000 - C$250,000 | 1.0% |
| C$250,000 - C$400,000 | 1.5% |
| C$400,000 - C$2,000,000 | 2.0% |
| Above C$2,000,000 | 2.5% |
Each tier taxes only the portion of the price that falls within it -- the same marginal-bracket mechanics as income tax, applied to a purchase price instead of taxable income.
First-time buyer rebate: up to C$4,000 off the calculated tax, which fully eliminates the tax for a purchase price up to roughly C$368,000.
Toronto Municipal Land Transfer Tax (MLTT)
If the property is within the City of Toronto, an ADDITIONAL municipal tax applies on top of the provincial tax, using the same bracket schedule described above (through C$3,000,000). A separate first-time buyer rebate of up to C$4,475 applies to the municipal portion, stacking with the provincial C$4,000 rebate for a combined maximum saving of C$8,475.
Toronto introduced additional graduated "luxury" MLTT brackets (rates escalating from roughly 4.4% up to 8.6%) on the portion of price above C$3,000,000 for properties with one or two single-family residences, effective April 1, 2026. This calculator does NOT model those luxury brackets -- a Toronto property priced above C$3,000,000 will owe MORE municipal tax than this tool reports, and is flagged in the output as exceeding that threshold.
British Columbia Property Transfer Tax (PTT)
BC uses its own marginal bracket schedule applied to fair market value:
| Portion of Fair Market Value | Rate |
|---|---|
| C$0 - C$200,000 | 1% |
| C$200,000 - C$2,000,000 | 2% |
| Above C$2,000,000 | 3% |
An additional 2% surtax applies to the RESIDENTIAL portion of fair market value above C$3,000,000.
First Time Home Buyers' Program exemption:
| Fair Market Value | Exemption |
|---|---|
| Up to C$500,000 | Full exemption (the entire PTT owed) |
| C$500,000 - C$835,000 | Flat C$8,000 off the tax owed |
| C$835,000 - C$860,000 | The C$8,000 exemption phases out linearly to zero |
| Above C$860,000 | No exemption |
Worked Example
A first-time buyer purchases a C$650,000 house in Ottawa -- Ontario, but outside Toronto, so only the provincial tax applies. Ontario's schedule is marginal, so each slice of the price is taxed at its own rate.
Step 1 -- First C$55,000 at 0.5%. C$55,000 x 0.5% = C$275
Step 2 -- Next C$195,000 at 1.0%. C$195,000 x 1.0% = C$1,950
Step 3 -- Next C$150,000 at 1.5%. C$150,000 x 1.5% = C$2,250
Step 4 -- Remaining C$250,000 at 2.0%. C$250,000 x 2.0% = C$5,000
Step 5 -- Gross provincial land transfer tax. C$275 + C$1,950 + C$2,250 + C$5,000 = C$9,475
Step 6 -- The first-time buyer rebate. Gross tax of C$9,475 exceeds the cap, so the rebate is capped at C$4,000
Step 7 -- Net provincial tax payable. C$9,475 - C$4,000 = C$5,475
The Same House Inside Toronto
Toronto levies a municipal land transfer tax on the identical bracket schedule, so the buyer pays the whole thing twice, with a separate and slightly larger municipal rebate.
Step 8 -- Gross municipal tax. Same schedule on C$650,000 = C$9,475
Step 9 -- Municipal first-time buyer rebate. Capped at C$4,475
Step 10 -- Net municipal tax. C$9,475 - C$4,475 = C$5,000
Step 11 -- Combined gross tax across both levels. C$9,475 + C$9,475 = C$18,950
Step 12 -- Combined rebates. C$4,000 + C$4,475 = C$8,475
Step 13 -- Combined net land transfer tax. C$18,950 - C$8,475 = C$10,475
Crossing the city boundary costs C$5,000 in cash at closing on the same purchase price. That is roughly the size of a legal bill and a moving budget combined, and it is payable in cash, which no mortgage will advance against.
British Columbia, for Contrast
BC uses its own brackets and grants relief as an exemption rather than a rebate.
Step 14 -- First C$200,000 at 1%. C$200,000 x 1% = C$2,000
Step 15 -- Next C$450,000 at 2%. C$450,000 x 2% = C$9,000
Step 16 -- Gross property transfer tax. C$2,000 + C$9,000 = C$11,000
Step 17 -- The first-time buyer exemption. C$650,000 sits in the C$500,000 to C$835,000 band, so a flat C$8,000 exemption applies
Step 18 -- Net property transfer tax. C$11,000 - C$8,000 = C$3,000
The same price, the same buyer profile, and a C$2,475 lower bill in Vancouver than in Ottawa -- and C$7,475 lower than in Toronto. Land transfer tax is one of the largest closing costs in Canada and one of the most jurisdictionally arbitrary.
What This Does Not Account For
- Every province except Ontario and British Columbia. Alberta and Saskatchewan charge only small flat land TITLE registration fees, not a percentage-of-price transfer tax. Quebec has its own "welcome tax" (droit de mutation) with municipality-set variations. Manitoba, Nova Scotia, PEI, and others each have distinct structures. NONE of these are modeled here -- this calculator is Ontario/Toronto and BC only.
- Toronto's luxury MLTT surtax above C$3,000,000. As noted above, the exact graduated rates on the portion of price above C$3,000,000 (effective April 1, 2026) are not modeled; only flagged.
- Ontario's non-single-family-residential nuance. The 2.0%/2.5% top provincial tiers technically apply in full only to land containing one or two single-family residences; other property types (many condos, commercial, multi-unit) can have a lower effective top rate in Ontario's own published guidance. This calculator models the common single-family-residential case.
- Non-resident/foreign buyer surtaxes. Both Ontario (Non-Resident Speculation Tax, an additional 25% in the Greater Golden Horseshoe) and BC (Additional Property Transfer Tax, 20% in specified areas) levy a SEPARATE, much larger surtax on foreign entities/taxable trustees buying residential property. Not modeled here -- this calculator assumes a Canadian citizen or permanent resident buyer.
- Legal, notary, and other closing costs. This is a land-transfer-tax-only calculator; use this platform's companion Closing Costs Calculator for the full bundle of lender, title, and legal fees.
- BC's Newly Built Home Exemption and other BC exemption programs. BC offers a SEPARATE exemption for newly-constructed homes with its own thresholds, distinct from the First Time Home Buyers' Program modeled here; not included.
Common Pitfalls
- Assuming the Toronto tax REPLACES the Ontario tax. It does not -- Toronto's Municipal LTT is charged in ADDITION to the provincial LTT, roughly doubling the total land transfer tax bill for a Toronto purchase compared to an identical purchase elsewhere in Ontario.
- Forgetting the BC exemption has a hard ceiling, not just a percentage cap. Properties priced even slightly above C$860,000 fair market value get ZERO first-time-buyer PTT relief in BC, unlike a smoothly-declining percentage discount -- the C$25,000 phase-out window between C$835,000 and C$860,000 is a hard, narrow cliff.
- Confusing Ontario's rebate cap with a full exemption for all buyers. The C$4,000 (or combined C$8,475 in Toronto) rebate only fully zeroes out the tax for lower-priced homes; above roughly C$368,000 (Ontario) the buyer still owes the excess above the rebate cap.
- Not checking for a foreign-buyer surtax. A non-citizen, non-permanent-resident buyer in specified regions of Ontario or BC can owe an ADDITIONAL 20-25% surtax on top of everything modeled here -- a completely separate calculation this tool does not perform.
- Treating "Land Transfer Tax" and "Property Transfer Tax" as different taxes. They are the same concept under different provincial names -- Ontario (and most provinces) call it Land Transfer Tax; British Columbia specifically calls its version the Property Transfer Tax.
Frequently Asked Questions
How much is Ontario's Land Transfer Tax on a $650,000 home?
Does the Toronto first-time buyer rebate stack with Ontario's?
What is the BC Property Transfer Tax first-time buyer exemption threshold?
Does this calculator cover Quebec's "welcome tax"?
Is there an additional tax for foreign buyers?
Sources
- Internal Revenue Service, the official authority for the tax rules this calculator relates to. irs.gov
Also consulted: Ontario Land Transfer Tax Act, R.S.O. 1990, c. L.6 -- the provincial marginal bracket schedule and first-time buyer refund program; City of Toronto Municipal Code, Chapter 760, "Land Transfer Tax" -- the additional municipal tax and its first-time buyer rebate; City of Toronto Council's December 17, 2025 bylaw amendment introducing graduated high-value brackets effective April 1, 2026 (per Miller Thomson and KRP professional tax-bulletin coverage); British Columbia Property Transfer Tax Act, RSBC 1996, c. 378 -- the general PTT bracket schedule, the additional 2% high-value residential surtax, and the First Time Home Buyers' Program; All specific dollar thresholds and bracket boundaries cross-verified across Ratehub, WOWA, and multiple independent Canadian real-estate law-firm client bulletins on 2026-08-22. Direct fetches to canada.ca and gov.bc.ca both failed in this session (403 Forbidden / connection errors) and these figures could not be independently re-confirmed against the primary .gov source in this pass -- cross-verify directly against gov.bc.ca and ontario.ca/toronto.ca before relying on this calculator for an actual closing-cost decision.