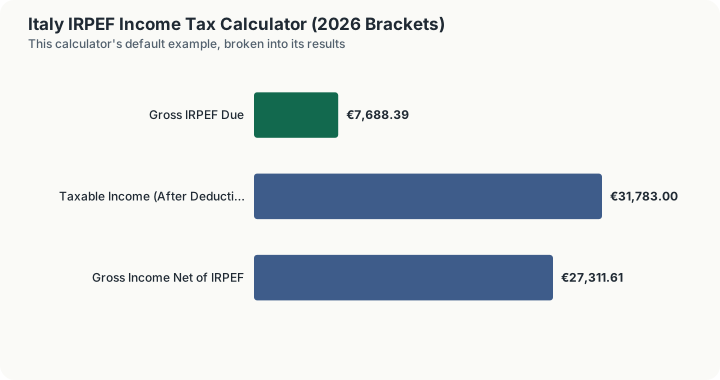
Quick Answer: On €35,000 of gross Italian income with a typical €3,217 INPS-contribution deduction, taxable income is €31,783 and gross IRPEF (Imposta sul Reddito delle Persone Fisiche) due for 2026 is €7,688.39 -- an effective rate of about 24.2% and a marginal rate of 33%.
Overview
IRPEF is Italy's national personal income tax, administered by the Agenzia delle Entrate, and it applies progressively: each euro of taxable income is taxed at the rate for the bracket it falls into, not at a single flat rate on the whole amount. Starting 1 January 2026, the Legge di Bilancio 2026 (Budget Law, L. 199/2025) made permanent a three-bracket structure that had been trialled experimentally in 2024-2025, and it went a step further by cutting the middle bracket's rate from 35% to 33% for income between €28,000 and €50,000.
This calculator is built for Italy specifically -- it computes IRPEF in euros using the current 2026 bracket thresholds and rates, not a generic income-tax model borrowed from another country. It takes your gross annual income, subtracts any deductible expenses (oneri deducibili) you enter -- most commonly mandatory INPS social-security withholding -- and applies the 2026 progressive schedule to what remains.
How This Is Calculated
Step 1 -- Taxable income:
Step 2 -- 2026 IRPEF brackets, applied progressively (each rate applies only to the slice of income within that bracket):
| Bracket | Rate |
|---|---|
| €0-€28,000 | 23% |
| €28,000-€50,000 | 33% |
| Above €50,000 | 43% |
For example, €40,000 of taxable income is taxed as: €28,000 at 23%, plus the remaining €12,000 at 33% -- not €40,000 at a single rate.
What changed for 2026: the middle bracket was 35% through 2025; the Budget Law 2026 cut it to 33%. At exactly €50,000 of taxable income, this brought gross tax down from €14,140 to €13,700 -- a €440 saving that is also, not coincidentally, the maximum benefit anyone sees from this reform (see the caveat below).
Worked Example
Using the calculator's default inputs:
- Annual Gross Income: €35,000
- Deductible Expenses: €3,217 (approximating a typical employee's 9.19% INPS contribution)
Step by step:
- Taxable income = €35,000 − €3,217 = €31,783.
- First €28,000 taxed at 23% = €6,440.00.
- Remaining €3,783 (€31,783 − €28,000) taxed at 33% = €1,248.39.
- Gross IRPEF = €6,440.00 + €1,248.39 = €7,688.39.
- Effective rate = €7,688.39 ÷ €31,783 ≈ 24.2%. Marginal rate = 33% (the rate on the last euro earned).
- Gross income net of IRPEF only = €35,000 − €7,688.39 = €27,311.61.
Compare a higher earner with €80,000 gross income and €7,352 in deductions (taxable income €72,648): the first €28,000 is taxed at 23% (€6,440), the next €22,000 at 33% (€7,260), and the remaining €22,648 at 43% (€9,738.64) -- a total of €23,438.64, with a 43% marginal rate.
What This Does Not Account For
- Detrazioni (tax credits). This calculator computes gross IRPEF only. It does not subtract the employment-income tax credit (detrazione da lavoro dipendente), dependent-family-member credits, or credits for deductible expenses like healthcare, mortgage interest, or home-renovation bonuses -- all of which reduce the final amount actually owed.
- Regional and municipal surtaxes. Every Italian region levies an "addizionale regionale" (commonly 1.2%-3.3% of taxable income) and most comuni levy an "addizionale comunale" (commonly 0%-0.9%), both set annually and varying by location and income band. Neither is included here.
- The >€200,000 sterilization mechanism. For taxpayers with total income above €200,000, the Budget Law 2026 claws back the 33%-bracket benefit by reducing certain 19%-rate deductions by €440 -- in effect, cancelling the net advantage of the rate cut for very high earners. This calculator does not model that clawback.
- Non-progressive income categories. Some income types (certain capital gains, severance pay under "tassazione separata," some rental income under cedolare secca) are taxed outside the ordinary IRPEF brackets modeled here -- see this platform's dedicated TFR, rental-tax, and pension calculators for those cases.
- Self-employment-specific regimes, such as the flat-rate "regime forfettario" (5%/15% substitute tax for qualifying small businesses and freelancers), which replaces IRPEF entirely rather than modifying it.
Common Pitfalls
- Applying the marginal rate to your whole income. Italy's IRPEF is a true progressive/marginal system: only the portion of income inside a given bracket is taxed at that bracket's rate. A €31,783 taxable income is not taxed entirely at 33% -- only the €3,783 above the €28,000 threshold is.
- Forgetting the 2026 rate cut only applies between €28,000 and €50,000. Income below €28,000 remains at 23%, and income above €50,000 remains at 43% -- the reform did not change the top or bottom brackets, only the middle one.
- Assuming the >€200,000 clawback affects the bracket rate itself. It doesn't change the 33% rate -- it separately reduces certain deductions to neutralize the euro-for-euro benefit, a subtler mechanism than a rate change.
- Confusing gross IRPEF with take-home pay. Regional/municipal surtaxes, detrazioni, and (for employees) INPS withholding all sit between gross IRPEF and your actual net paycheck -- none of the "net income" figures on this page should be read as a final take-home number.
- Mixing up "reddito" (income) and "imponibile" (taxable base). Deductible expenses (oneri deducibili) reduce the taxable base before brackets are applied; tax credits (detrazioni) reduce the tax bill afterward -- conflating the two produces the wrong final figure.
Frequently Asked Questions
What are the IRPEF tax brackets for 2026 in Italy?
How much did the 2026 tax reform actually save me?
Is this the same as my take-home pay?
Does IRPEF apply to self-employed income too?
Why is my deductible-expenses default set to a specific figure?
Are regional and municipal surtaxes really separate from IRPEF?
What income counts toward the IRPEF brackets?
Sources
- Agenzia delle Entrate -- "Aliquote e calcolo dell'IRPEF" portal page (agenziaentrate.gov.it), consulted for the underlying bracket-structure framework. agenziaentrate.gov.it
Caveat: the >€200,000 deduction-clawback ("sterilization") mechanism and current-year regional/municipal surtax rates were not independently re-verified against a primary Agenzia delle Entrate or regional-government document this session; both are disclosed above as not modeled in this calculator's output.
Also consulted: Legge di Bilancio 2026 (L. 199/2025): three-bracket IRPEF structure made permanent and second-bracket rate cut from 35% to 33% for income between €28,000 and €50,000, effective 1 January 2026. Confirmed via multiple concordant 2026 Italian tax-press sources (fiscomania.com, soluzionetasse.com, CGIL Roma e Lazio, sgravi.com, cafinforma.it), all independently agreeing on the exact bracket boundaries, rates, and the €14,140-to-€13,700 figure at €50,000.