How much do you contribute each month to Atal Pension Yojana?
The Atal Pension Yojana (APY) is India's guaranteed pension scheme for workers outside formal pension cover. You choose a pension of ₹1,000 to ₹5,000 a month from age 60, and you pay a fixed monthly contribution until then. What that contribution is depends almost entirely on how old you are when you join.
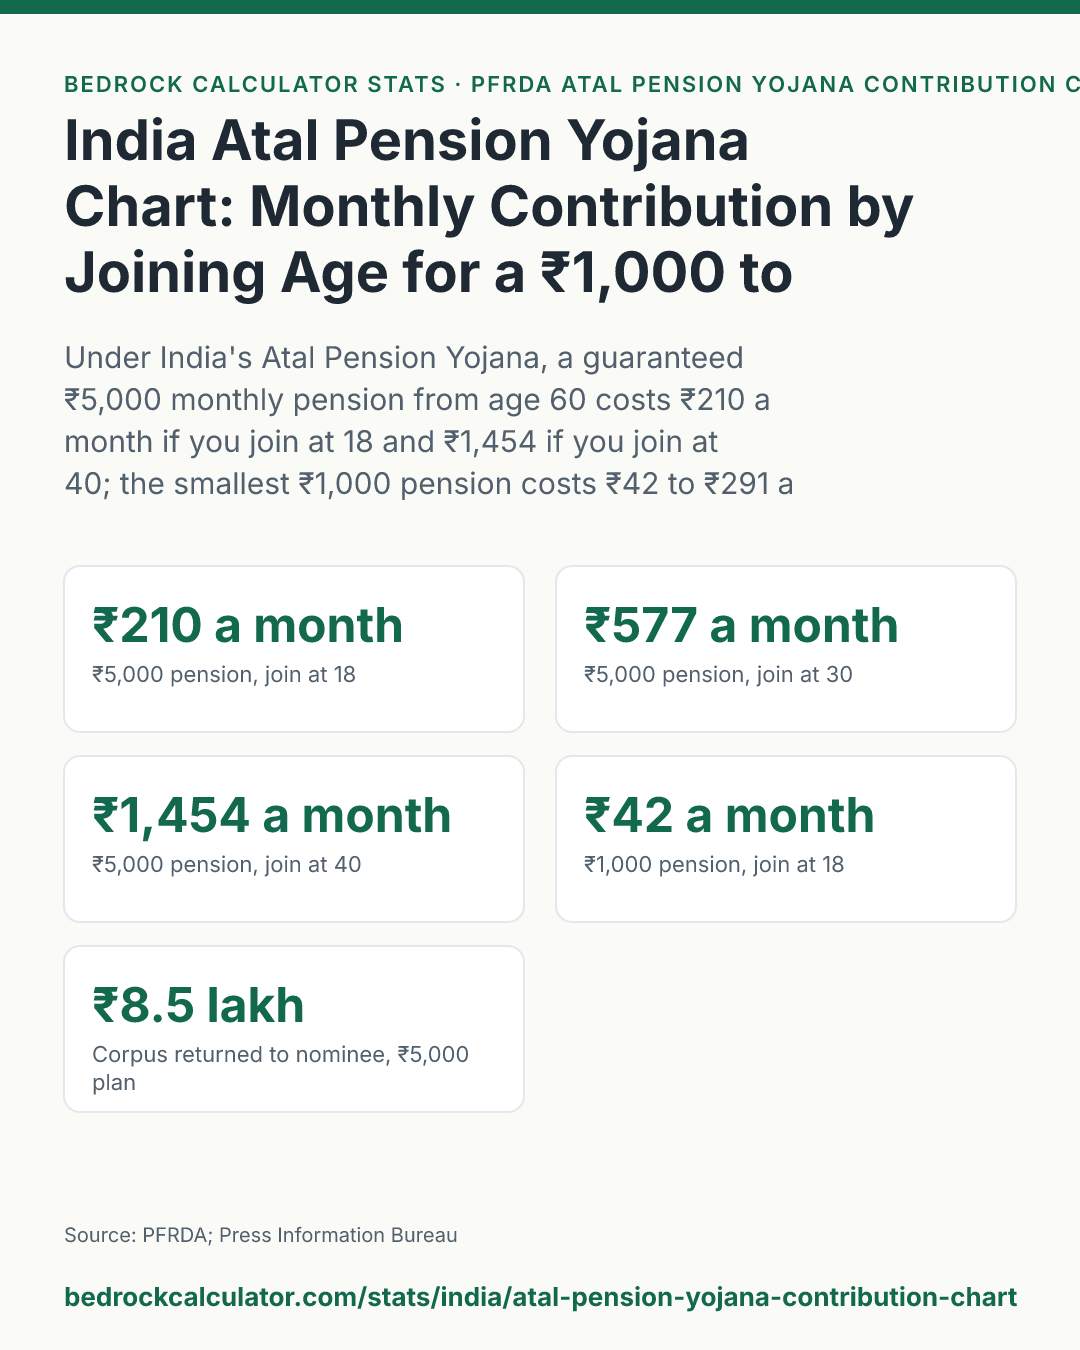
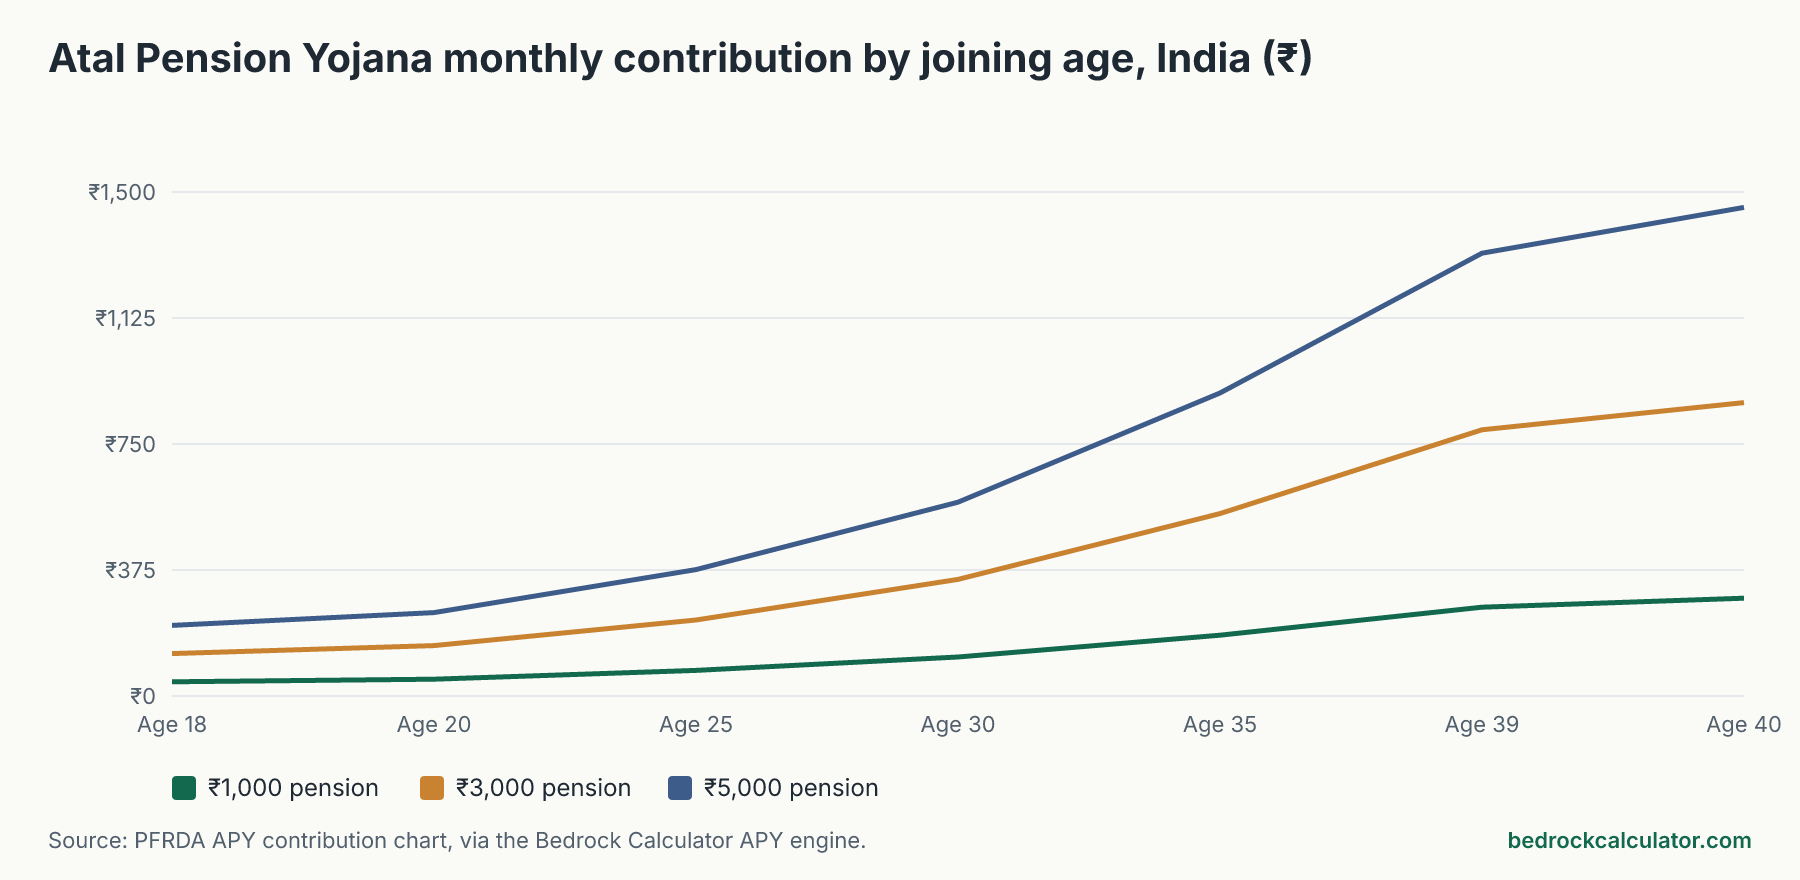
For the top ₹5,000 pension it's ₹210 a month if you join at 18, ₹577 at 30 and ₹1,454 at 40. For the smallest ₹1,000 pension it's ₹42 at 18 and ₹291 at 40.
The APY contribution chart
The contribution isn't calculated from an interest rate you can look up. The Pension Fund Regulatory and Development Authority (PFRDA) publishes a fixed chart: one monthly amount for each joining age from 18 to 40 and each of the five pension levels. The APY calculator on this site holds that chart, and we checked every figure in it against PFRDA's own chart in October 2026.
Here are the joining ages most people ask about. Click a column heading to sort.
India Atal Pension Yojana: monthly contribution by joining age and pension (₹)
Download CSVMonthly contribution payable until age 60 for a guaranteed monthly pension from 60. PFRDA contribution chart, as held by the calculator.
| 18 | 42 | ₹42 | ₹84 | ₹126 | ₹168 | ₹210 |
| 20 | 40 | ₹50 | ₹100 | ₹150 | ₹198 | ₹248 |
| 25 | 35 | ₹76 | ₹151 | ₹226 | ₹301 | ₹376 |
| 30 | 30 | ₹116 | ₹231 | ₹347 | ₹462 | ₹577 |
| 35 | 25 | ₹181 | ₹362 | ₹543 | ₹722 | ₹902 |
| 39 | 21 | ₹264 | ₹528 | ₹792 | ₹1,054 | ₹1,318 |
| 40 | 20 | ₹291 | ₹582 | ₹873 | ₹1,164 | ₹1,454 |
Two patterns stand out. First, the contribution climbs faster the later you join, because there are fewer years to build the money and the pension still starts at 60. Joining at 40 costs 6.9 times as much a month as joining at 18 for the same ₹5,000 pension. Second, the pension levels scale almost exactly. A ₹5,000 pension costs about five times what a ₹1,000 pension costs at the same age, so you can pick a level purely on what you can afford each month.
Picking a pension level
Take someone who joins at 30. The ₹1,000 pension costs ₹116 a month, the middle ₹3,000 pension ₹347, and the top ₹5,000 pension ₹577. Over the 30 years to 60, the smallest plan adds up to ₹41,760 paid in, and the largest to ₹2.08 lakh.
A sensible way to choose is to start from the monthly amount you can keep paying in a bad month, not a good one. The contribution is debited automatically from your savings account, and the plan only works if it keeps going for decades. Since the pension is a fixed rupee amount, many people pick the highest level they can sustain, because inflation will eat into whatever they choose.
How much you pay in total by 60
A lower monthly figure doesn't always mean less paid overall, because an early joiner pays for more years. A person joining at 18 pays for 42 years. Someone joining at 30 pays for 30 years, and someone joining at 40 pays for 20.
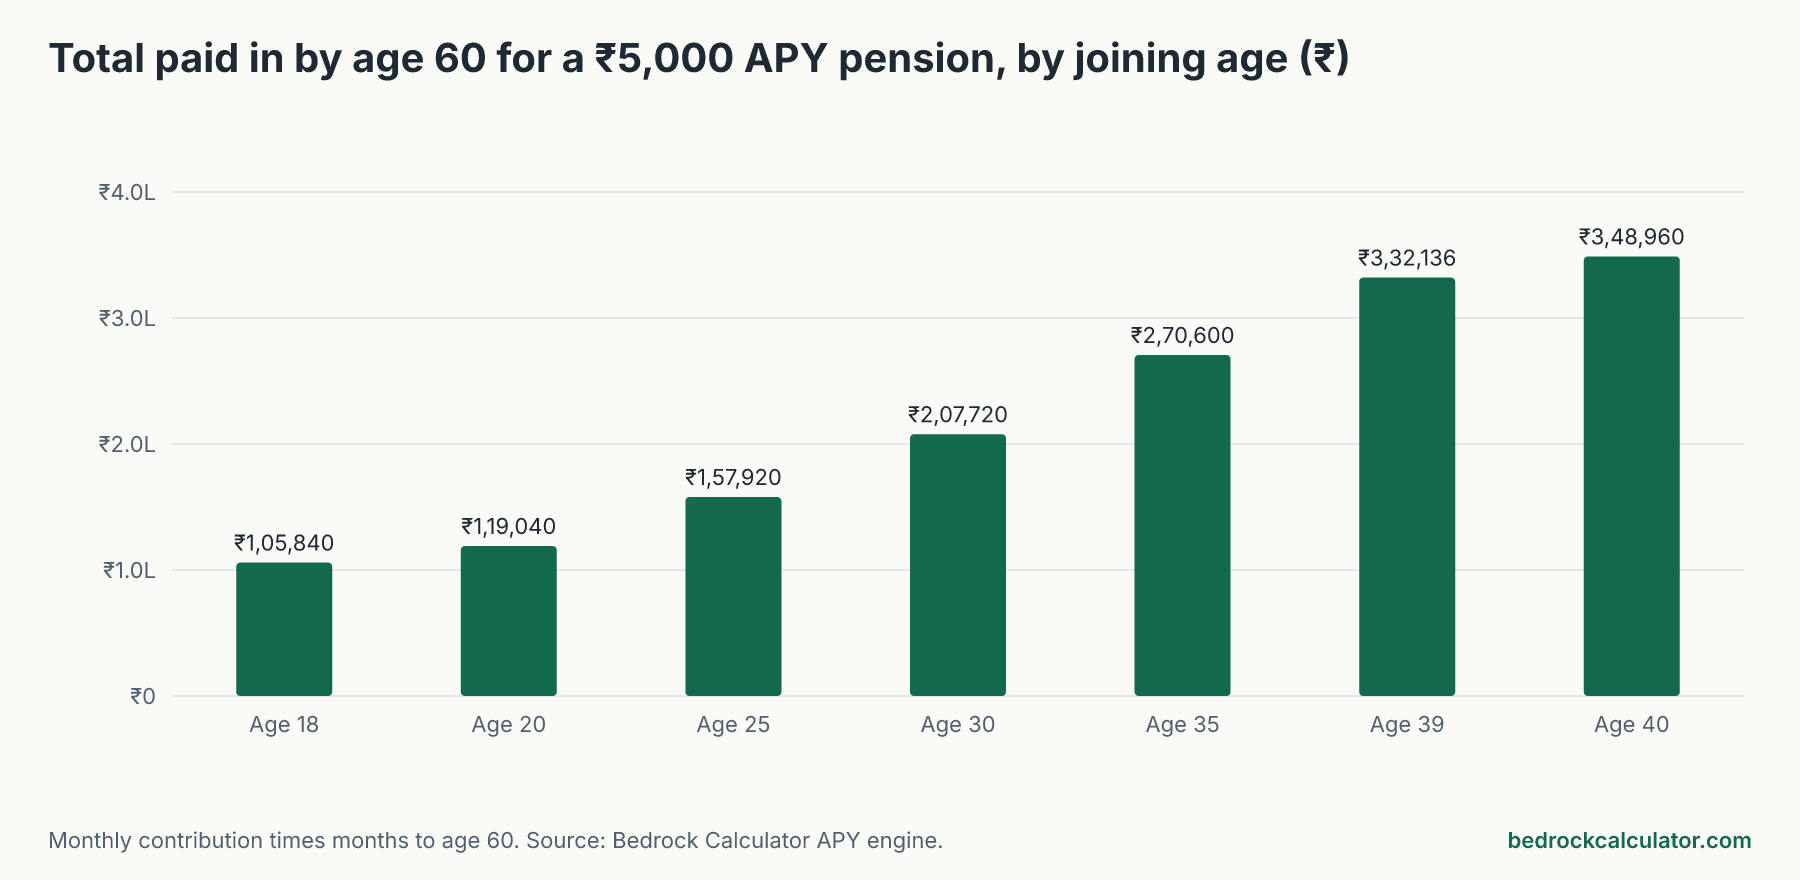
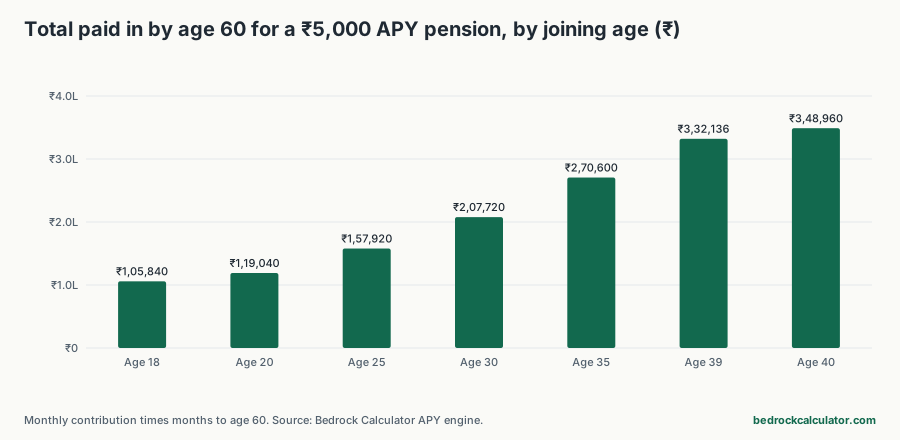
For the ₹5,000 plan the total paid by age 60 is ₹1.06 lakh from 18, ₹2.08 lakh from 30 and ₹3.49 lakh from 40. So even counting the extra years, joining at 40 means paying 3.3 times as much in total as joining at 18.
India Atal Pension Yojana: total paid in by age 60 for a ₹5,000 pension (₹)
Download CSVMonthly contribution times 12 times the years to age 60. Years of pension to match is the total paid divided by a year of pension.
| 18 | ₹210 | ₹1,05,840 | 1.8 |
| 20 | ₹248 | ₹1,19,040 | 2 |
| 25 | ₹376 | ₹1,57,920 | 2.6 |
| 30 | ₹577 | ₹2,07,720 | 3.5 |
| 35 | ₹902 | ₹2,70,600 | 4.5 |
| 39 | ₹1,318 | ₹3,32,136 | 5.5 |
| 40 | ₹1,454 | ₹3,48,960 | 5.8 |
The last column is a rough way to read value for money. It divides what you've paid in by one year of pension (₹60,000 for the ₹5,000 plan). Someone who joined at 18 has received back as much as they paid after about 1.8 years of pension. Someone who joined at 30 needs about 3.5 years, and someone who joined at 40 about 5.8. That ignores what the money could have earned elsewhere, but it shows how much early joining is worth.
What happens after 60, and if the subscriber dies
At 60 the guaranteed monthly pension starts and is paid for life. If the subscriber dies, the spouse gets the same pension for the rest of their life. After both have died, the nominee receives the pension wealth built up to the subscriber's age 60. PFRDA's chart gives an indicative figure for that return of corpus: ₹1.7 lakh for the ₹1,000 plan, rising to ₹8.5 lakh for the ₹5,000 plan.
The minimum pension is guaranteed by the Central Government, so it doesn't depend on how the fund's investments perform.
Who can join
You can join APY if you're an Indian citizen aged 18 to 40 and have a savings account with a bank or the post office. Since 1 October 2022, anyone who is or has been an income-tax payer can't join.
That rule matters for salaried workers. If you pay income tax, the National Pension System or the Public Provident Fund are the usual alternatives for long-term retirement saving.
How we worked out these numbers
Every contribution comes from the APY calculator, which looks up PFRDA's chart for the joining age and pension you pick:
- Monthly contributions, paid on time every month until age 60
- Totals are the monthly amount times the number of months to 60, with no interest added
- The return of corpus figures are PFRDA's indicative amounts from the same chart
What these numbers leave out
- Quarterly and half-yearly payment. APY also lets you pay every quarter or every six months, at slightly different amounts. Only the monthly chart is shown.
- Late payment charges. Any charge for a missed or late contribution isn't included.
- Leaving early. Voluntary exit before 60 returns your contributions and the earnings on them, without the guaranteed pension.
- The old government co-contribution. It applied only to eligible people who joined between 1 June 2015 and 31 March 2016.
- Inflation. The pension is a fixed rupee amount. ₹5,000 a month in 20 or 40 years' time will buy much less than it does today.
- Tax. Whether your contributions give you a tax deduction depends on your tax regime and situation. This page doesn't model it.
Run your own numbers
The APY calculator gives the contribution, total paid and pension for any joining age and pension level. To compare with other ways to save for retirement, try the NPS calculator, the PPF calculator or, if you're in a job with provident fund, the EPS pension calculator.