How much will your EPF corpus be at retirement?
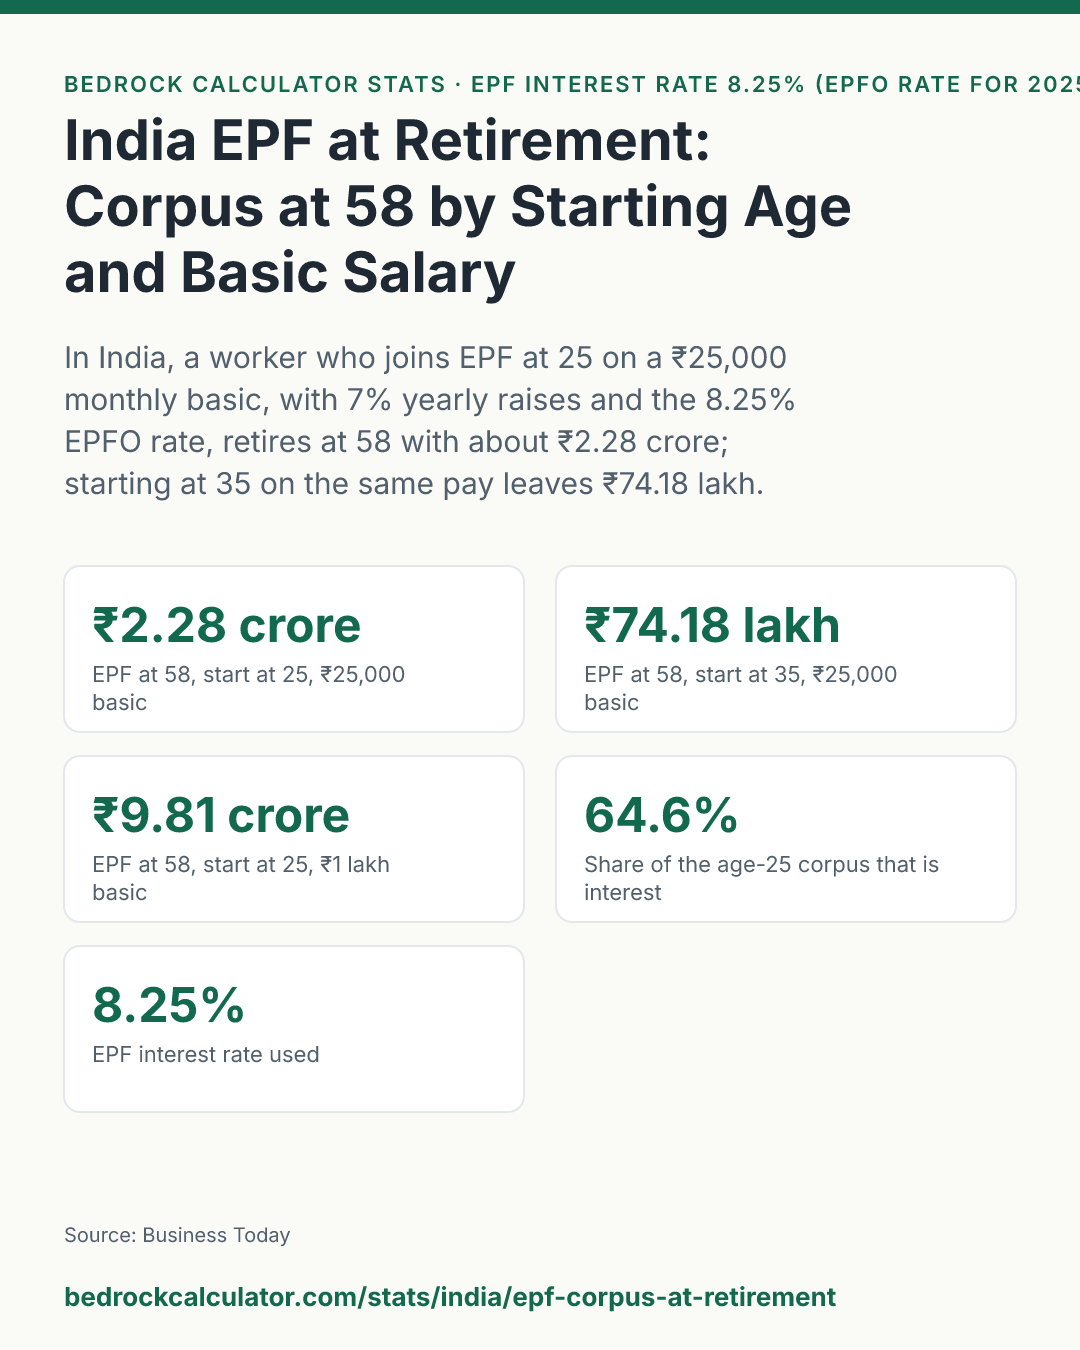
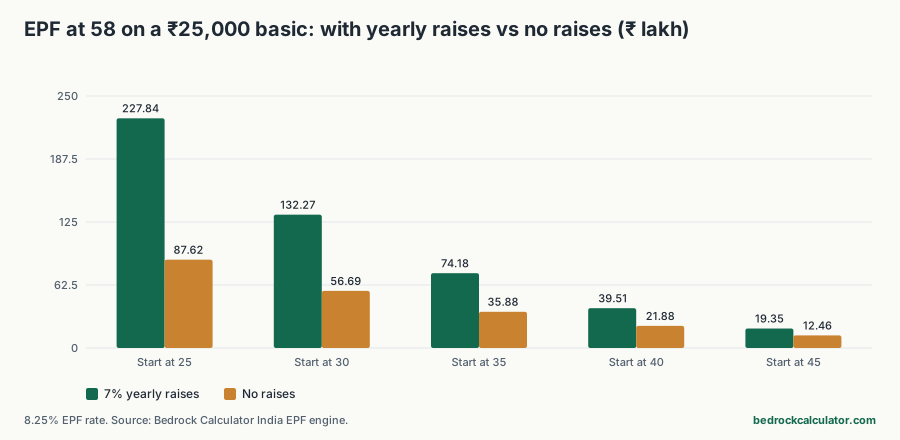
In India, someone who joins the Employees' Provident Fund at 25 on a basic salary of ₹25,000 a month, gets 7% raises every year and earns the 8.25% EPFO rate throughout would retire at 58 with about ₹2.28 crore in EPF. Start at 30 on the same pay and it's ₹1.32 crore. Start at 35 and it's ₹74.18 lakh.
That ten-year delay costs a lot. The age-25 corpus is 3.1 times the age-35 one, even though the earlier starter only works ten more years.
How we worked out these numbers
Every figure comes from the EPF calculator on this site, run once for each starting age and salary. Each run assumes:
- Basic pay plus dearness allowance (Basic + DA) of ₹15,000, ₹25,000, ₹50,000 or ₹1 lakh a month in the first year
- Pay that rises 7% a year, the calculator's default
- An EPF interest rate of 8.25%, the rate the EPFO board set for 2025-26, held flat for the whole career
- No opening balance and continuous service until 58, the normal EPF retirement age
Each month you put 12% of Basic + DA into EPF. Your employer pays the same 12%, but 8.33% of pay, worked out on no more than the ₹15,000 wage ceiling, goes to the Employees' Pension Scheme instead. On any salary at or above the ceiling that's ₹1,249.50 a month. The rest of the employer's share lands in your EPF account. The calculator adds a year's contributions at the end of each year and credits interest once a year on the running balance.
EPF corpus at 58 for every starting age and salary
Figures are in lakh rupees, so 100 means ₹1 crore. Click a column heading to sort.
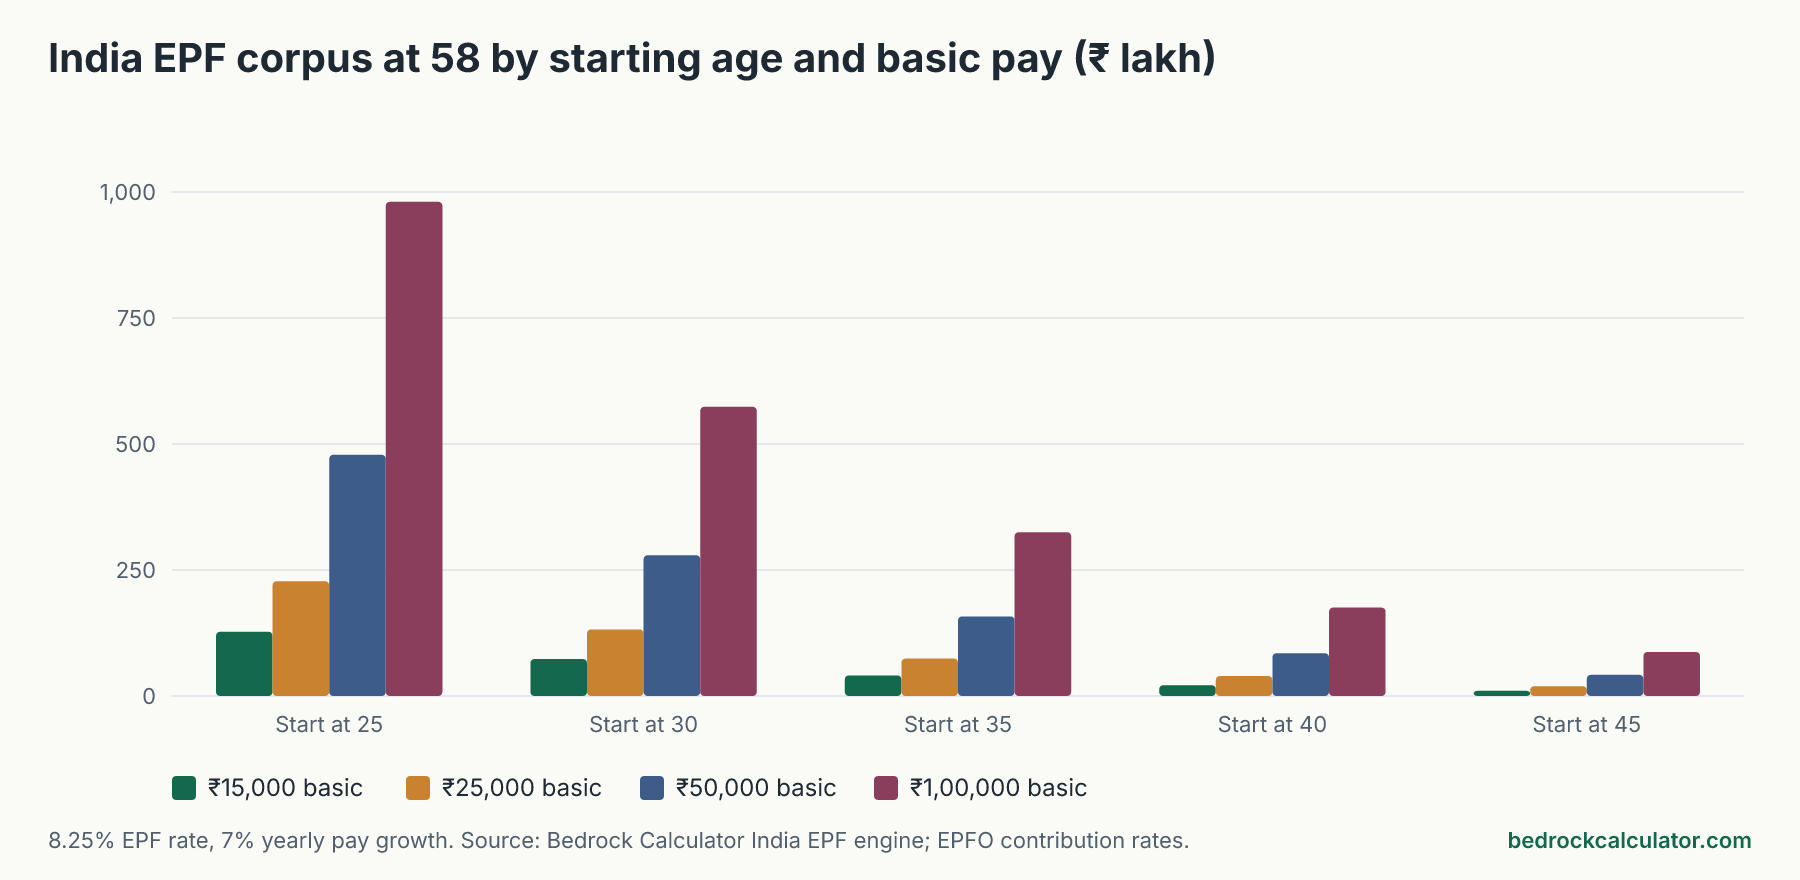
India EPF corpus at 58 by starting age and monthly basic (₹ lakh)
Download CSVEPF balance only, not EPS pension. 8.25% interest every year, 7% yearly growth in Basic + DA, no opening balance. Figures in lakh rupees (1 lakh = ₹1,00,000).
| 25 | 33 | 127.49 | 227.84 | 478.74 | 980.52 |
| 30 | 28 | 73.4 | 132.27 | 279.46 | 573.82 |
| 35 | 23 | 40.73 | 74.18 | 157.79 | 325.02 |
| 40 | 18 | 21.41 | 39.51 | 84.78 | 175.32 |
| 45 | 13 | 10.3 | 19.35 | 41.97 | 87.22 |
A few patterns stand out. Doubling your basic roughly doubles the corpus, because almost everything is a fixed percentage of pay. The exception is the EPS slice, which stops growing once pay passes the ceiling, so higher earners keep a slightly larger share of the employer's money in EPF. At the top of the table, joining at 25 on a ₹1 lakh basic grows to ₹9.81 crore. At the bottom, joining at 45 on ₹15,000 reaches ₹10.3 lakh.
Why starting early matters so much in EPF
The answer is compound interest. For the ₹25,000 earner who starts at 25, the money paid in is modest: ₹42.82 lakh from their own salary and ₹37.87 lakh from the employer. Interest supplies the other ₹1.47 crore, which is 64.6% of the final balance. Someone who starts at 45 on the same pay has only 13 years of compounding, and interest makes up just 35.1% of what they retire with.
Where a ₹25,000-basic EPF corpus comes from, by starting age (₹ lakh)
Download CSVYour 12% share, the employer share left after the EPS diversion, and interest. The EPS diversion is shown for reference; it is not part of the EPF balance.
| 25 | 42.82 | 37.87 | 147.16 | 227.84 | 4.95 |
| 30 | 29.05 | 24.85 | 78.37 | 132.27 | 4.2 |
| 35 | 19.24 | 15.79 | 39.15 | 74.18 | 3.45 |
| 40 | 12.24 | 9.54 | 17.73 | 39.51 | 2.7 |
| 45 | 7.25 | 5.3 | 6.8 | 19.35 | 1.95 |
The last column is worth a look. Over a career starting at 30, about ₹4.2 lakh of employer money goes to EPS rather than EPF. It doesn't vanish. It buys a monthly pension from 58, which the EPS pension calculator works out, but you can't withdraw it as a lump sum the way you can EPF.
What if your salary doesn't grow?
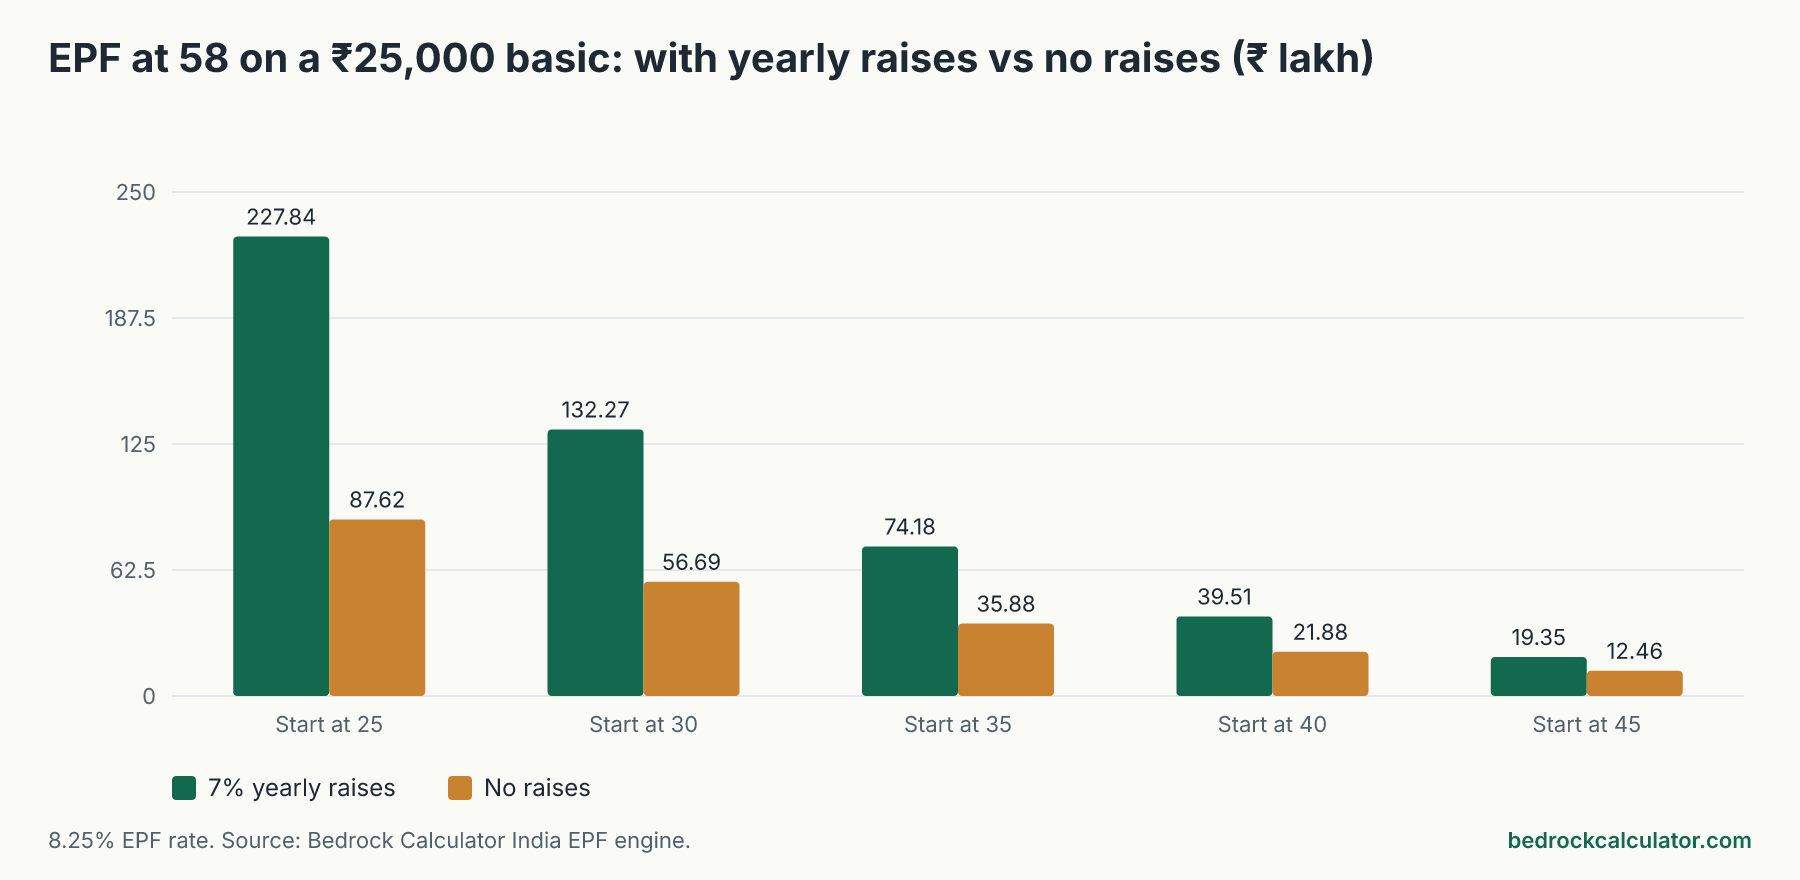
Raises do as much work as interest here. Starting at 30 on a ₹25,000 basic, flat pay for 28 years gives ₹56.69 lakh at 58. With 7% raises it's ₹1.32 crore, a difference of ₹75.58 lakh. Your contributions are a fixed share of pay, so every raise lifts every later deposit.
If your raises have been smaller than 7%, or most of them went into allowances rather than Basic + DA, expect something closer to the flat line. Only Basic + DA counts for EPF.
What the calculator leaves out
These are projections under fixed assumptions, and several things would change your own number:
- Interest rate changes. The EPFO board sets a new rate each year. We've held 8.25% for decades, which won't happen exactly.
- Inflation. Every figure is in future rupees. A corpus of ₹2.28 crore in 33 years will buy far less than that sum buys today.
- Employer contributions above the ceiling. The calculator has the employer pay its share on your full Basic + DA. Many employers only contribute on the first ₹15,000 a month, which would cut the employer column sharply for anyone earning more. The employer PF contribution calculator shows both versions.
- Tax on interest. Interest on employee contributions above a yearly threshold is taxable every year. That mostly affects the ₹50,000 and ₹1 lakh rows, and no tax has been taken off here.
- Voluntary PF, withdrawals and job gaps. Extra VPF contributions would raise the corpus. Withdrawals for a house, a wedding or a spell between jobs would lower it.
- Monthly crediting. EPFO works interest out on monthly balances. Adding the year's deposits at year end is a slightly cautious approximation.
Getting your own EPF figure
Open the EPF calculator and enter your current Basic + DA, your age and your current balance from the EPFO passbook. It will project your corpus at 58 and show how much of it is interest. If you want a second pillar alongside EPF, the NPS calculator works the same way for National Pension System contributions.