How much is the home loan EMI on each loan size in India?
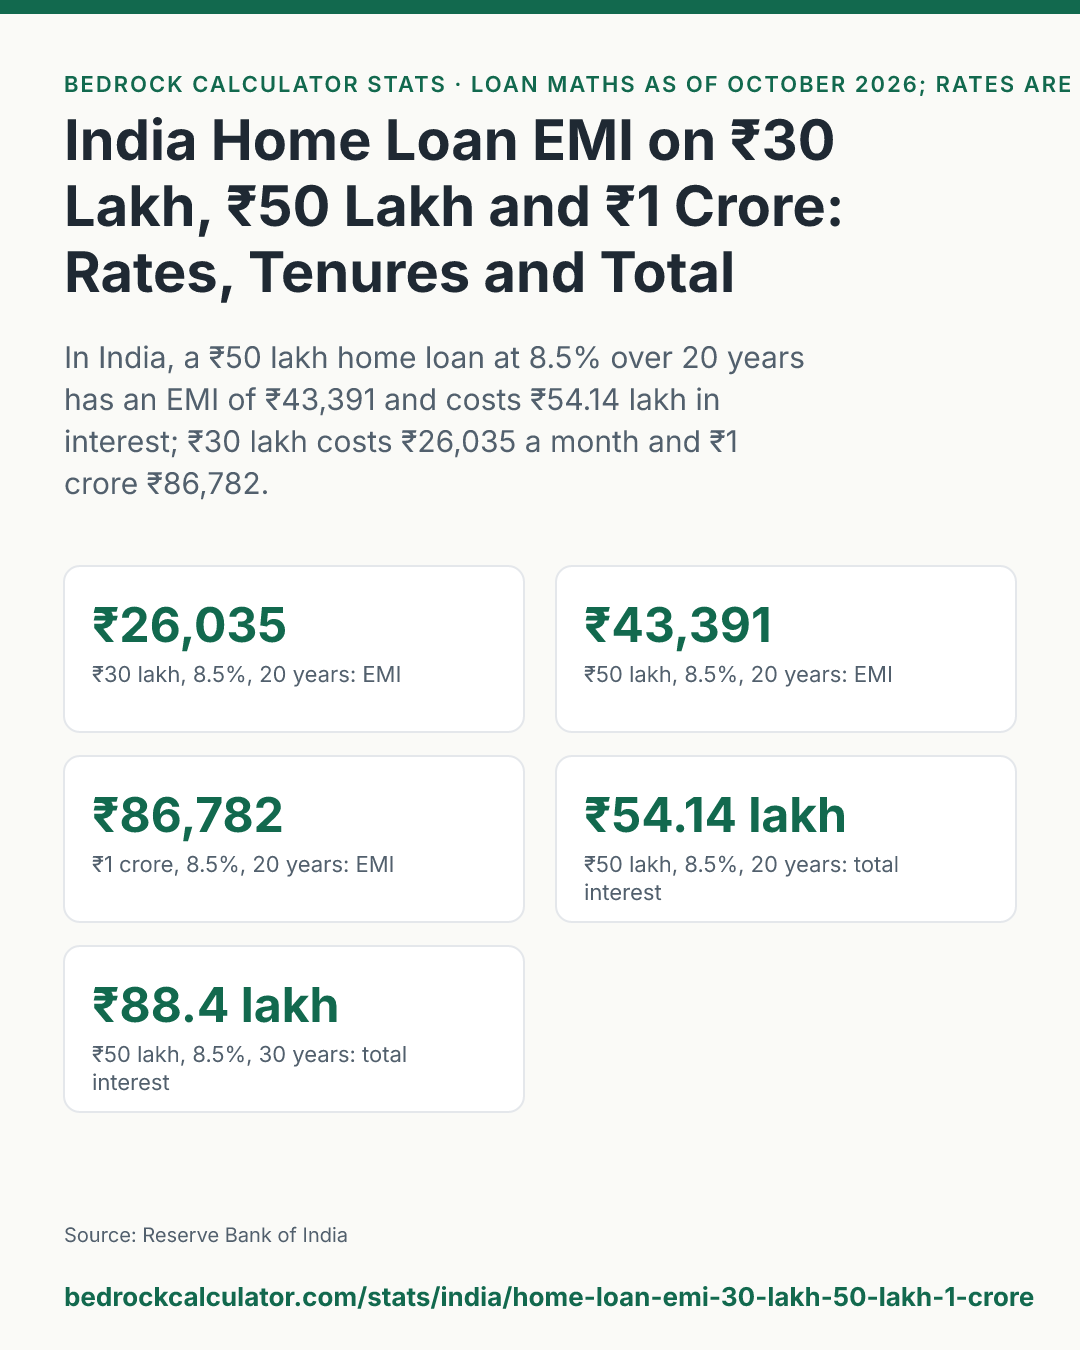
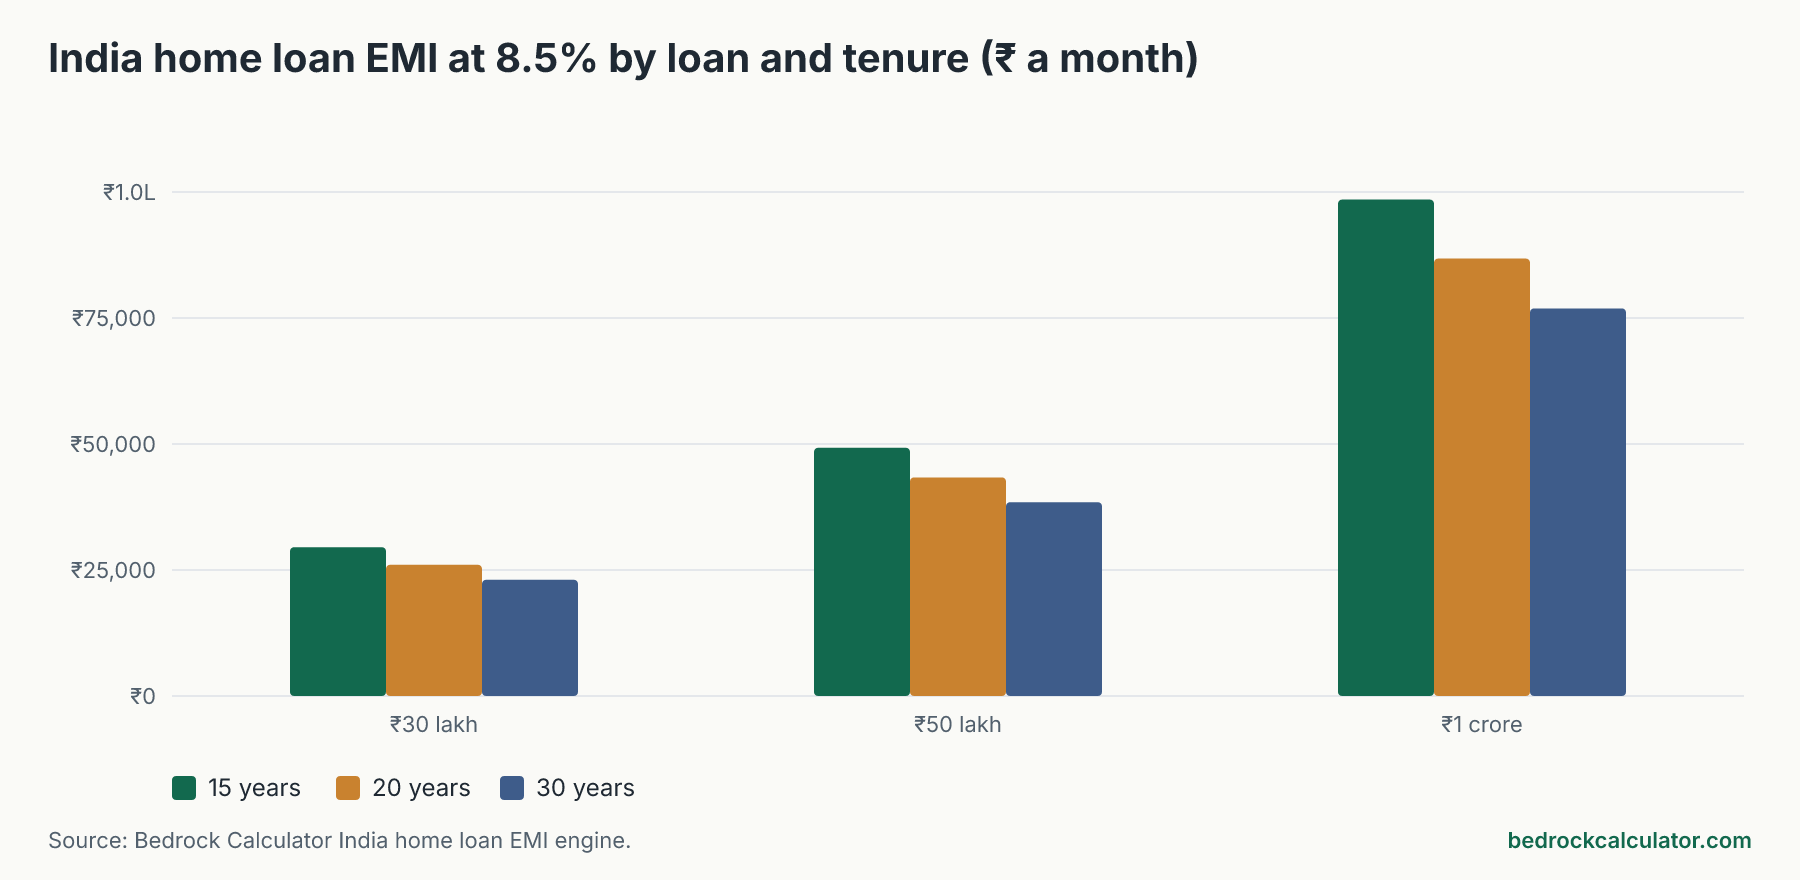
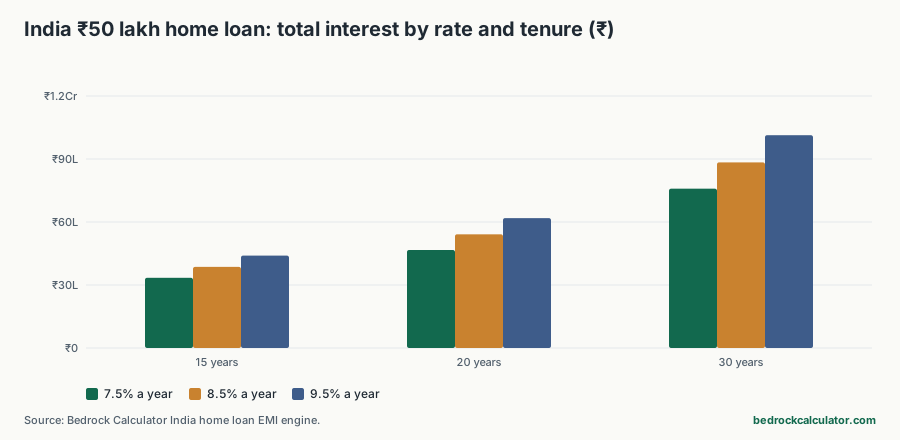
In India, a ₹50 lakh home loan at 8.5% a year over 20 years has an EMI of ₹43,391. Over the full term you pay ₹54.14 lakh in interest, so the loan costs ₹1.04 crore in all. The same terms on ₹30 lakh give an EMI of ₹26,035, and on ₹1 crore ₹86,782.
Stretch that ₹50 lakh loan to 30 years and the EMI falls by only ₹4,945 a month, while total interest rises by ₹34.27 lakh.
How we worked out these numbers
Every figure comes from the home loan EMI calculator on this site. It uses the standard reducing-balance method that Indian banks and housing finance companies use: interest each month on the outstanding balance, a fixed EMI that clears the loan exactly on time, and a final instalment that settles any paisa rounding.
We picked three rates, 7.5%, 8.5% and 9.5% a year, to cover the range most borrowers see. They are inputs, not quotes from any lender. Each rate is held for the whole loan, there is no prepayment unless we say so, and processing fees are left out.
EMI and total interest on ₹30 lakh, ₹50 lakh and ₹1 crore
Amounts in rupees. Click a column heading to sort.
India home loan EMI and total interest on ₹30 lakh, ₹50 lakh and ₹1 crore (₹)
Download CSVReducing-balance EMI, rate held for the whole loan, no prepayment, no fees. Rupees.
| ₹30,00,000 | 7.5 | 15 | ₹27,810 | ₹20,05,867 | ₹50,05,867 |
| ₹30,00,000 | 7.5 | 20 | ₹24,168 | ₹28,00,270 | ₹58,00,270 |
| ₹30,00,000 | 7.5 | 30 | ₹20,976 | ₹45,51,512 | ₹75,51,512 |
| ₹30,00,000 | 8.5 | 15 | ₹29,542 | ₹23,17,593 | ₹53,17,593 |
| ₹30,00,000 | 8.5 | 20 | ₹26,035 | ₹32,48,326 | ₹62,48,326 |
| ₹30,00,000 | 8.5 | 30 | ₹23,067 | ₹53,04,272 | ₹83,04,272 |
| ₹30,00,000 | 9.5 | 15 | ₹31,327 | ₹26,38,813 | ₹56,38,813 |
| ₹30,00,000 | 9.5 | 20 | ₹27,964 | ₹37,11,343 | ₹67,11,343 |
| ₹30,00,000 | 9.5 | 30 | ₹25,226 | ₹60,81,220 | ₹90,81,220 |
| ₹50,00,000 | 7.5 | 15 | ₹46,351 | ₹33,43,111 | ₹83,43,111 |
| ₹50,00,000 | 7.5 | 20 | ₹40,280 | ₹46,67,118 | ₹96,67,118 |
| ₹50,00,000 | 7.5 | 30 | ₹34,961 | ₹75,85,857 | ₹1,25,85,857 |
| ₹50,00,000 | 8.5 | 15 | ₹49,237 | ₹38,62,656 | ₹88,62,656 |
| ₹50,00,000 | 8.5 | 20 | ₹43,391 | ₹54,13,879 | ₹1,04,13,879 |
| ₹50,00,000 | 8.5 | 30 | ₹38,446 | ₹88,40,448 | ₹1,38,40,448 |
| ₹50,00,000 | 9.5 | 15 | ₹52,211 | ₹43,98,023 | ₹93,98,023 |
| ₹50,00,000 | 9.5 | 20 | ₹46,607 | ₹61,85,574 | ₹1,11,85,574 |
| ₹50,00,000 | 9.5 | 30 | ₹42,043 | ₹1,01,35,376 | ₹1,51,35,376 |
| ₹1,00,00,000 | 7.5 | 15 | ₹92,701 | ₹66,86,222 | ₹1,66,86,222 |
| ₹1,00,00,000 | 7.5 | 20 | ₹80,559 | ₹93,34,237 | ₹1,93,34,237 |
| ₹1,00,00,000 | 7.5 | 30 | ₹69,921 | ₹1,51,71,723 | ₹2,51,71,723 |
| ₹1,00,00,000 | 8.5 | 15 | ₹98,474 | ₹77,25,311 | ₹1,77,25,311 |
| ₹1,00,00,000 | 8.5 | 20 | ₹86,782 | ₹1,08,27,759 | ₹2,08,27,759 |
| ₹1,00,00,000 | 8.5 | 30 | ₹76,891 | ₹1,76,80,884 | ₹2,76,80,884 |
| ₹1,00,00,000 | 9.5 | 15 | ₹1,04,422 | ₹87,96,044 | ₹1,87,96,044 |
| ₹1,00,00,000 | 9.5 | 20 | ₹93,213 | ₹1,23,71,148 | ₹2,23,71,148 |
| ₹1,00,00,000 | 9.5 | 30 | ₹84,085 | ₹2,02,70,753 | ₹3,02,70,753 |
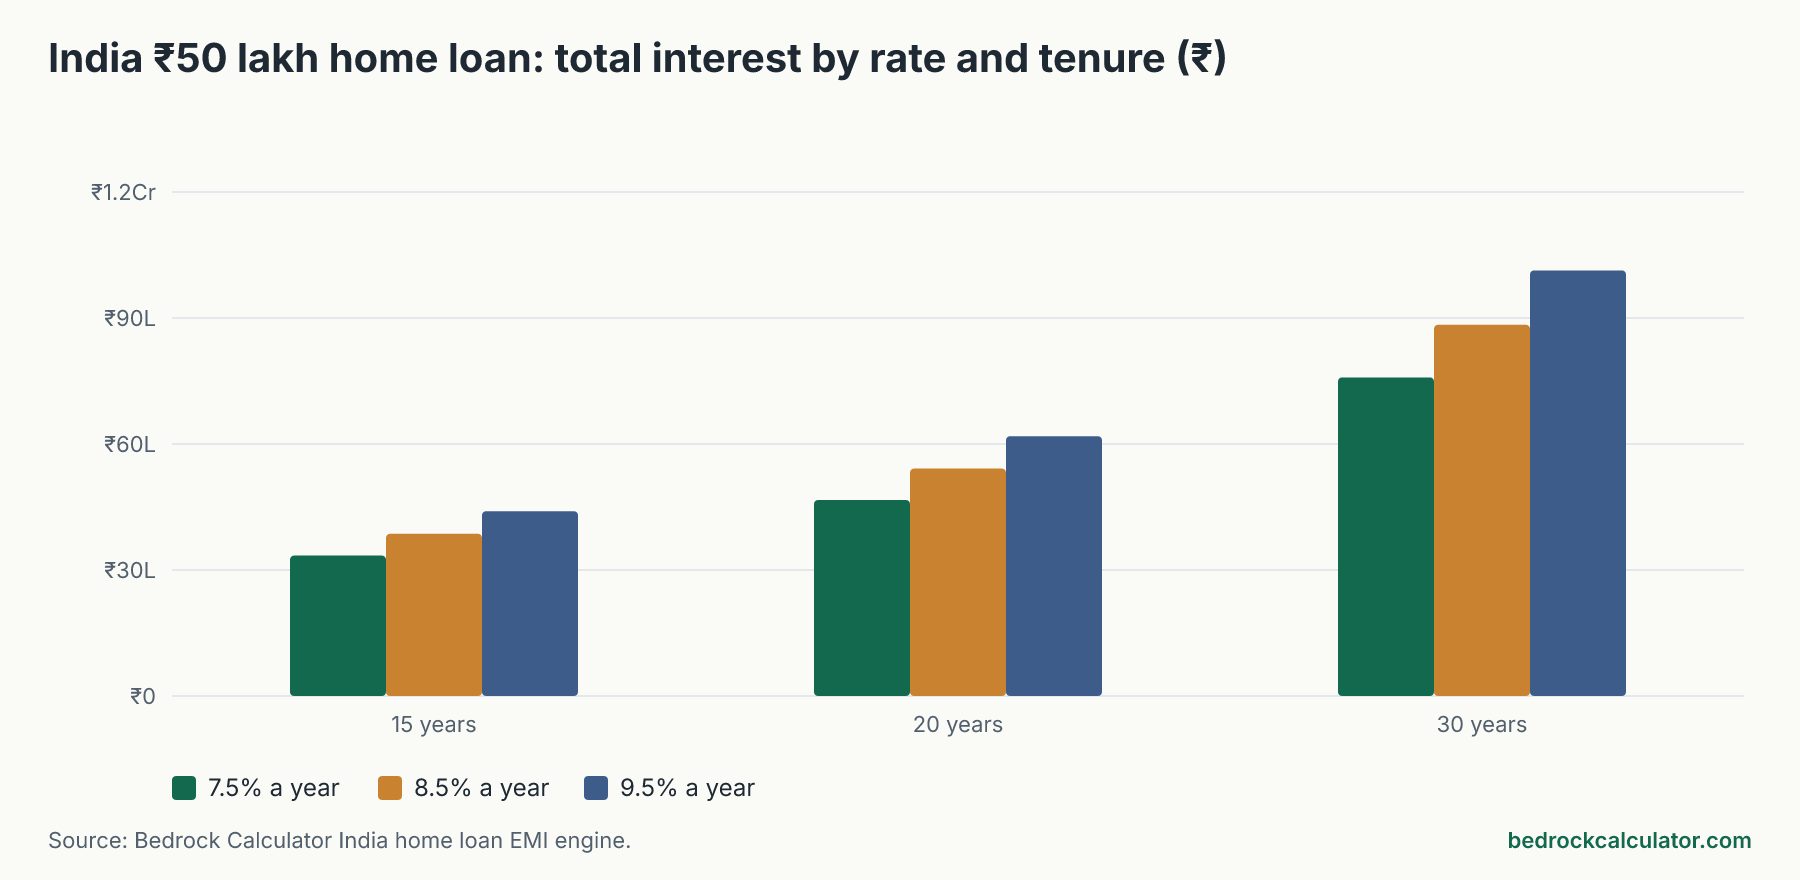
Two things stand out. First, the EMI scales exactly with the loan: ₹1 crore costs twice what ₹50 lakh does on the same terms. Second, the total interest is huge relative to the loan once the tenure gets long. On ₹50 lakh at 8.5% over 30 years, interest comes to ₹88.4 lakh, which is 1.77 times the amount you borrowed.
Tenure: the trade between EMI and interest
On ₹50 lakh at 8.5%:
- 15 years: EMI ₹49,237, total interest ₹38.63 lakh
- 20 years: EMI ₹43,391, total interest ₹54.14 lakh
- 30 years: EMI ₹38,446, total interest ₹88.4 lakh
Going from 20 years down to 15 raises the EMI by ₹5,846 a month and saves ₹15.51 lakh of interest. Going from 20 up to 30 lowers the EMI by ₹4,945 and adds ₹34.27 lakh. A longer tenure is the most expensive way there is to make an EMI affordable.
How much the interest rate matters
On a ₹50 lakh, 20-year loan, the gap between 7.5% and 9.5% is ₹6,327 a month on the EMI and ₹15.18 lakh of interest over the loan. Even one percentage point, 7.5% against 8.5%, is worth ₹3,112 a month and ₹7.47 lakh in total.
That is why a rate cut from your lender, or moving the loan to a cheaper one, is worth chasing. Most Indian home loans are floating rate, and when the rate changes your lender may adjust the EMI, the remaining tenure or both. The table assumes the rate never moves, which won't be true over 20 years.
Why the first years feel like you're paying only interest
On the ₹50 lakh loan at 8.5%, the very first EMI of ₹43,391 includes ₹35,417 of interest, 81.6% of the payment. The balance hardly moves in the early years because interest is charged on almost the whole loan. The split improves every month, but the principal part of the EMI only overtakes the interest part in month 143, about 11.9 years in.
What a ₹5 lakh prepayment does
The flip side of front-loaded interest is that early prepayments are powerful. On the ₹50 lakh, 20-year loan at 8.5%, a one-time prepayment of ₹5 lakh after 5 years, with the EMI kept the same, saves ₹10.69 lakh of interest and ends the loan 36 months early. Since 1 January 2026, the Reserve Bank of India's prepayment directions bar lenders from charging a fee for prepaying a floating rate loan taken by an individual for non-business purposes, so there is no penalty eating into that saving on a new floating rate home loan.
What these figures leave out
- Rate changes over the life of a floating rate loan
- Processing fees, legal and valuation charges, and any insurance added to the loan
- Pre-EMI interest on an under-construction home
- Tax benefits. Under the old regime part of the interest and principal can reduce your taxable income. The home loan tax benefit calculator works that out.
- Stamp duty and registration, which you pay upfront on top of the down payment; see the stamp duty calculator
Working out your own EMI
Open the home loan EMI calculator, enter your loan amount, the rate on your sanction letter and the tenure, and try a one-time prepayment or a fixed extra amount each month to see how much sooner the loan ends. If you are deciding whether to buy or keep renting, the HRA vs home loan calculator compares the tax side of each.