How much is the Medicare IRMAA surcharge at each income in 2026?
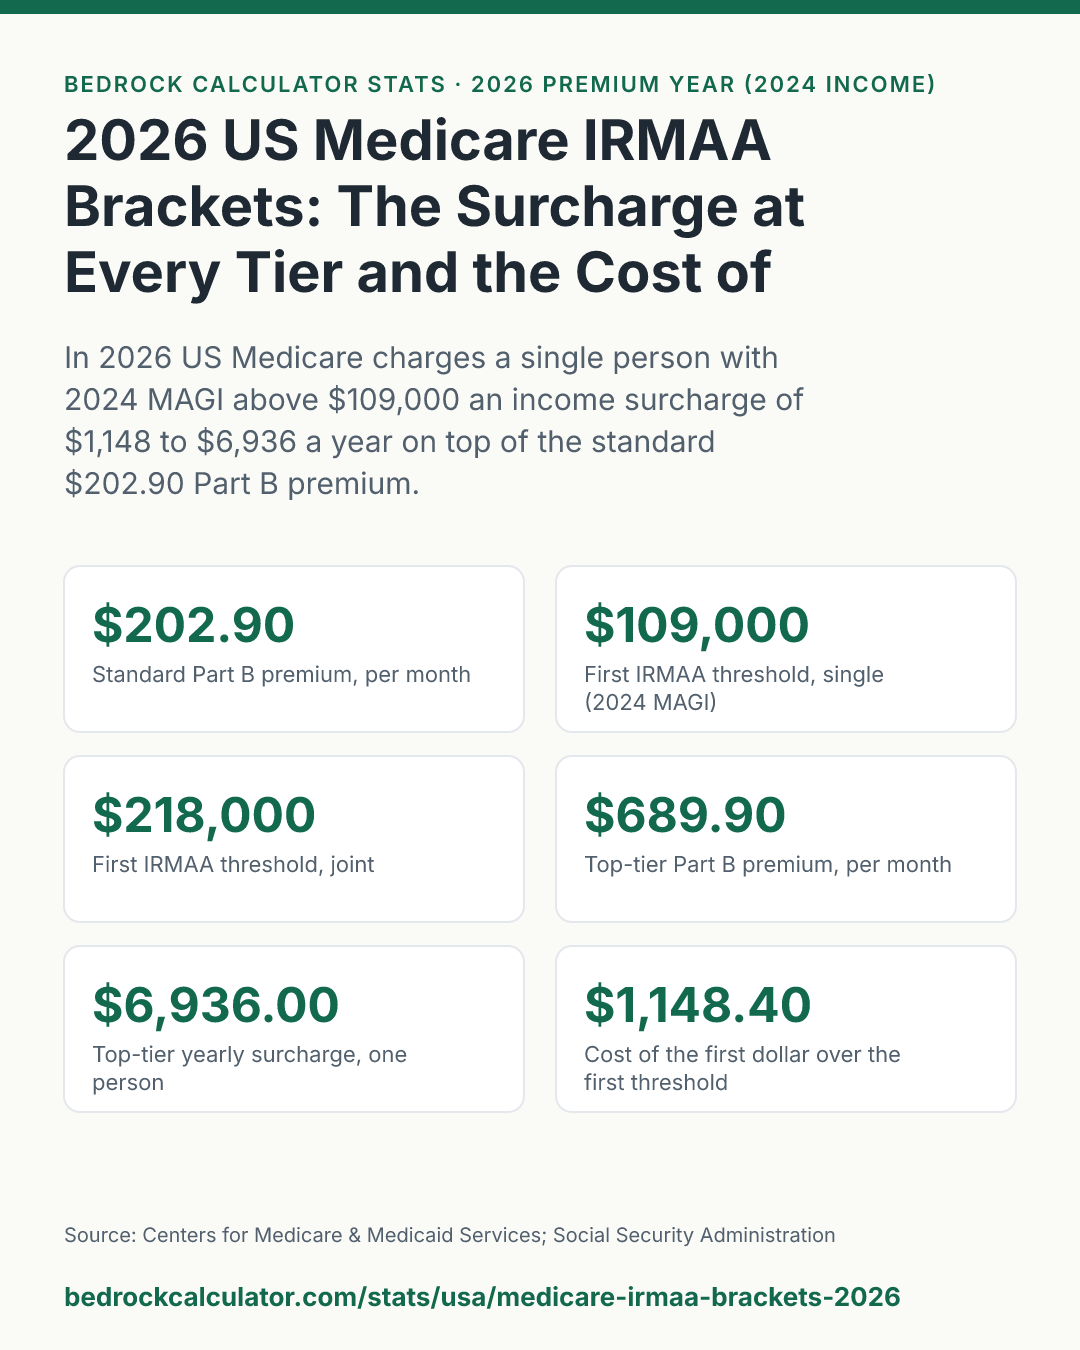
Most people on Medicare in the US pay the standard Part B premium of $202.90 a month in 2026. If your 2024 modified adjusted gross income was above $109,000 as a single filer, or $218,000 on a joint return, you pay an income-related surcharge called IRMAA on top, for both Part B and Part D.
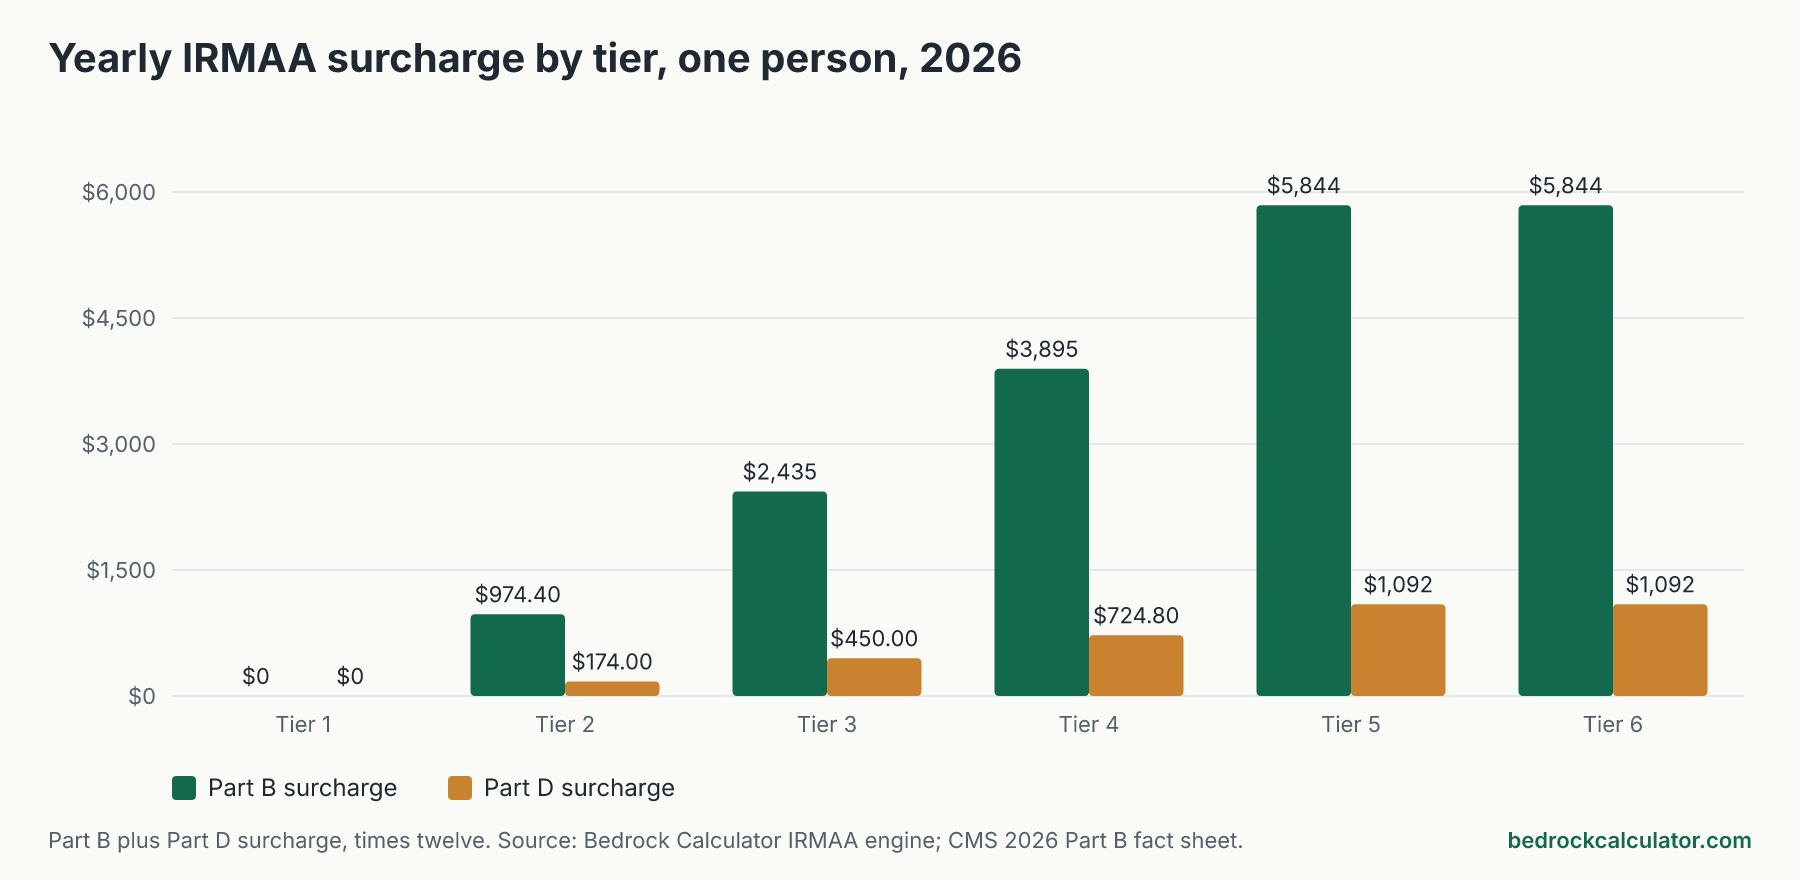
The surcharge runs from $1,148.40 a year in the first tier to $6,936.00 a year in the top one, per person. And it's a cliff, not a slope: one dollar over a threshold costs the whole step, which is $1,148.40 a year at the first threshold.
The 2026 IRMAA brackets
There are 6 tiers. The first is the standard premium with no surcharge. Each one after that adds a fixed monthly amount to Part B and another to Part D.
2026 Medicare IRMAA brackets and monthly surcharges
Download CSVMAGI from the 2024 tax return. Tiers 2 to 5 apply once MAGI is above the previous tier's ceiling; CMS starts the top tier at exactly $500,000 single or $750,000 joint. The Part D surcharge is added to whatever your drug plan charges.
| 1 | $109,000 | $218,000 | $0.00 | $202.90 | $0.00 | $0.00 | $0.00 |
| 2 | $137,000 | $274,000 | $81.20 | $284.10 | $14.50 | $1,148.40 | $2,296.80 |
| 3 | $171,000 | $342,000 | $202.90 | $405.80 | $37.50 | $2,884.80 | $5,769.60 |
| 4 | $205,000 | $410,000 | $324.60 | $527.50 | $60.40 | $4,620.00 | $9,240.00 |
| 5 | $500,000 | $750,000 | $487.00 | $689.90 | $91.00 | $6,936.00 | $13,872.00 |
| 6 | n/a | n/a | $487.00 | $689.90 | $91.00 | $6,936.00 | $13,872.00 |
n/a means the top tier has no upper limit.
Reading across a row: a single person whose 2024 MAGI was between $109,000 and $137,000 is in tier 2. Their Part B premium is $284.10 a month instead of $202.90, and Medicare adds $14.50 a month to whatever their drug plan charges. Together that's $95.70 a month, or $1,148.40 a year more than someone in tier 1.
At the top, for MAGI from $500,000 up as a single filer or $750,000 up on a joint return, the Part B premium is $689.90 a month, about 3.4 times the standard premium, and the Part D surcharge is $91.00.
How we worked out these numbers
We ran the Medicare IRMAA calculator on this site at a MAGI inside every tier, for single and joint filers, and then again one dollar above each threshold to price the cliffs. The thresholds and surcharges come from the CMS 2026 premium tables held in the site's engine. Nothing here is estimated.
What the numbers include and leave out:
- They're the surcharge amounts that CMS sets for Part B and Part D. They don't include the premium your Part D drug plan or Medicare Advantage plan charges, which varies by insurer and region.
- They don't include the Part B deductible, coinsurance, Medigap premiums, or any late enrollment penalty.
- They assume you enter the right MAGI. For IRMAA that's adjusted gross income plus tax-exempt interest, from the return two years before the premium year.
- The hold-harmless rule, which caps Part B increases for some people whose premium comes out of a Social Security check, isn't modeled. It generally doesn't protect anyone who owes IRMAA anyway.
What one dollar over an IRMAA threshold costs
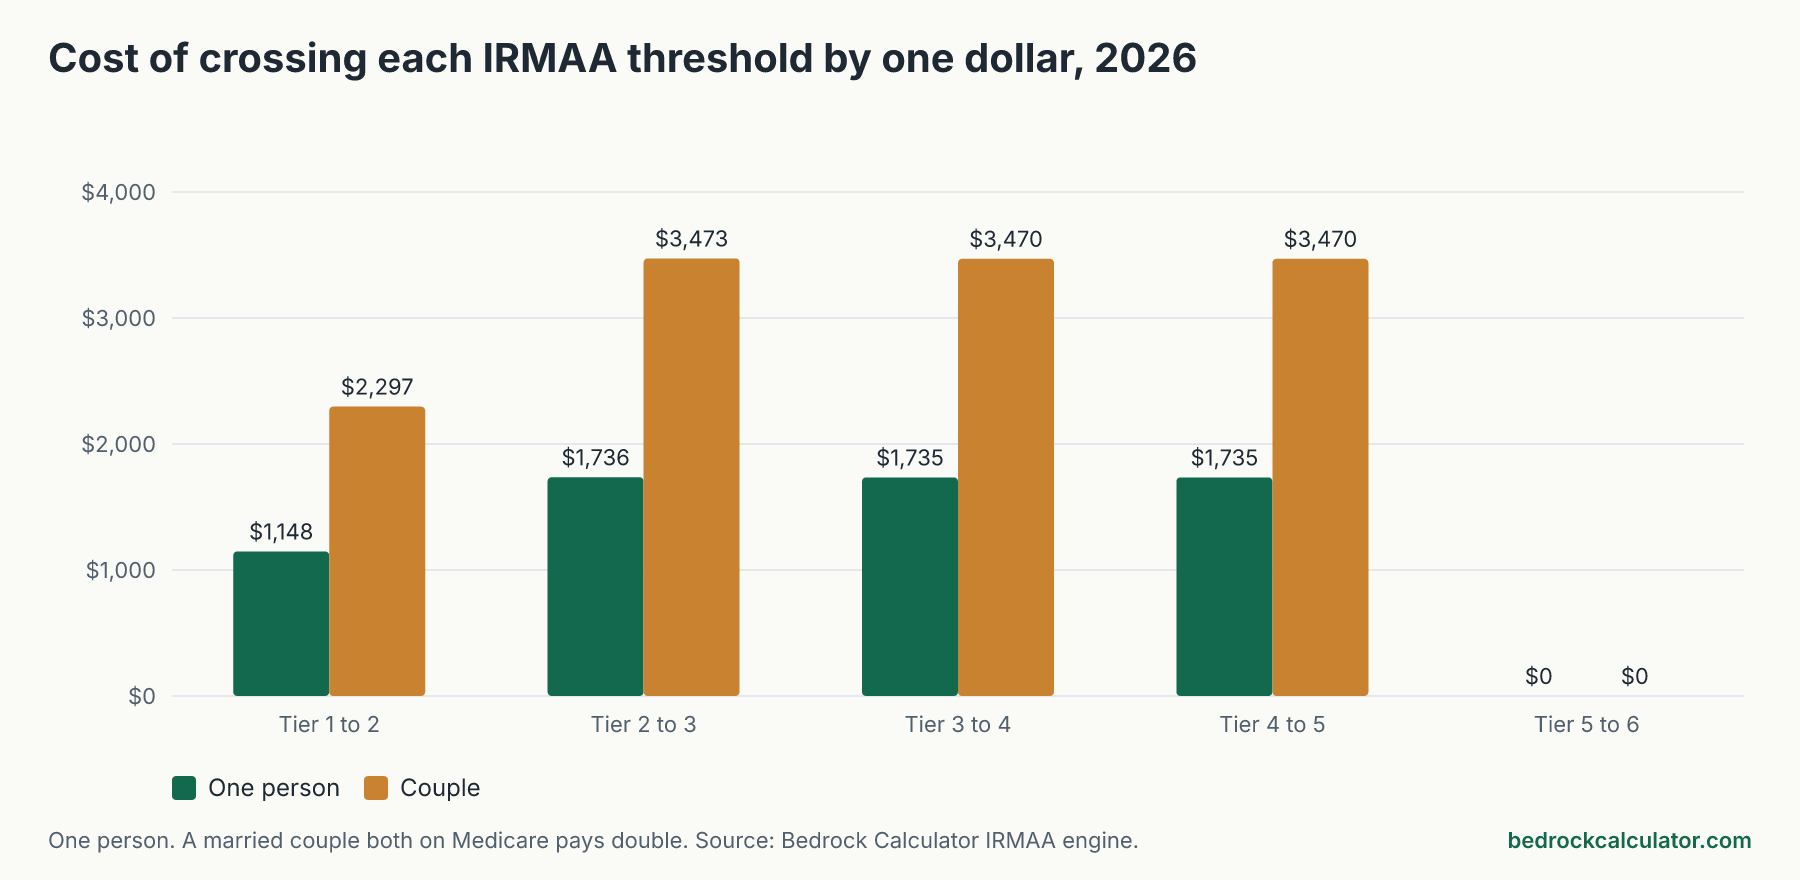
Because IRMAA is a step function, the useful number isn't the surcharge in your tier. It's the cost of the next dollar of income that pushes you into the tier above.
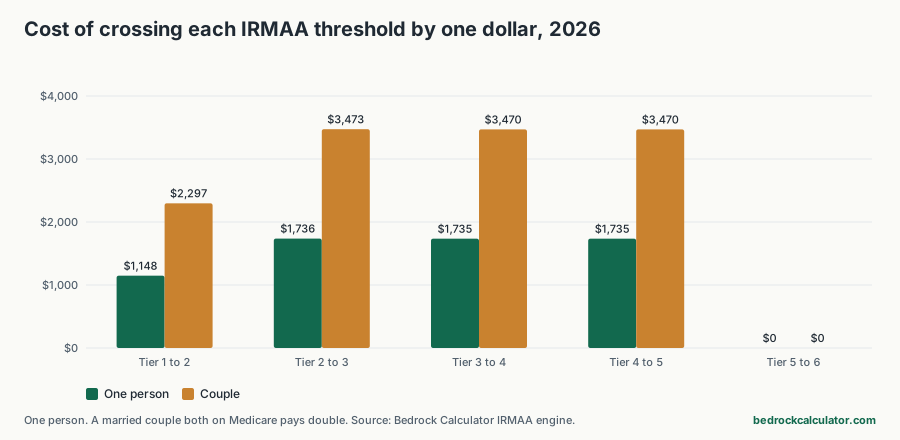
What one dollar over each IRMAA threshold costs, 2026
Download CSVYearly increase in Part B and Part D surcharges from one extra dollar of MAGI at each single-filer ceiling. A couple on a joint return pays twice this at the joint ceiling.
| Tier 1 to tier 2 | $109,000 | $1,148.40 | $2,296.80 |
| Tier 2 to tier 3 | $137,000 | $1,736.40 | $3,472.80 |
| Tier 3 to tier 4 | $171,000 | $1,735.20 | $3,470.40 |
| Tier 4 to tier 5 | $205,000 | $1,735.20 | $3,470.40 |
| Tier 5 to tier 6 | $500,000 | $0.00 | $0.00 |
The first threshold costs a single person $1,148.40 a year. The middle steps are the steepest, about $1,736.40 each, starting at $137,000. The last step, into the top tier, is the smallest at $0.00.
For a married couple who are both on Medicare, every one of those figures doubles. The joint thresholds are twice the single ones for the first four ceilings, but each spouse is billed the surcharge separately off the same joint income. Crossing the first joint threshold of $218,000 by a dollar costs the household $2,296.80 a year.
Why your 2026 premium depends on 2024 income
Social Security sets your IRMAA from the most recent tax return the IRS has, which for 2026 premiums is the 2024 return. That two-year lag catches people in two common ways.
The first is retirement itself. If you worked a full year in 2024 and retired in 2025, your 2026 premium is set on a working salary even though your income has dropped. The second is a one-off spike: a large Roth conversion, a home sale with a gain above the exclusion, or a big capital gain in 2024 can lift you a tier or two for 2026 only.
There's a remedy for the first case. If your income fell because of one of the life-changing events Social Security recognizes, such as retirement, the death of a spouse or the loss of a pension, you can file Form SSA-44 and ask it to use a more recent year. The IRMAA appeal calculator shows what a successful appeal would save. A spike from a voluntary choice like a Roth conversion isn't a qualifying event.
Planning around the 2026 IRMAA thresholds
Since the cost lands all at once at each threshold, the planning question is simple: how far below the next ceiling are you, and is the extra income you're considering worth a full step?
A few ways people manage it:
- Size Roth conversions to the bracket. Converting up to the ceiling of your current tier, rather than a round number, avoids paying a step for a few hundred dollars of extra income. The Roth conversion ladder calculator helps plan the amounts.
- Use qualified charitable distributions. Giving from an IRA after age 70 and a half keeps the gift out of AGI altogether.
- Watch tax-exempt interest. Municipal bond interest is free of federal income tax but still counts toward IRMAA MAGI.
- Time large gains. Spreading a sale over two tax years can keep each year under a ceiling.
To see where your own income lands, and how much headroom you have, enter your MAGI in the Medicare IRMAA calculator. The Medicare Part B premium calculator prices the household cost for a couple and shows what a specific extra amount of income would do.
If you're working out your 2026 taxes alongside this, our 2026 Social Security and Medicare tax guide covers the payroll side, which is a different thing from these premiums.