How much is the monthly mortgage payment at each rate and loan size?
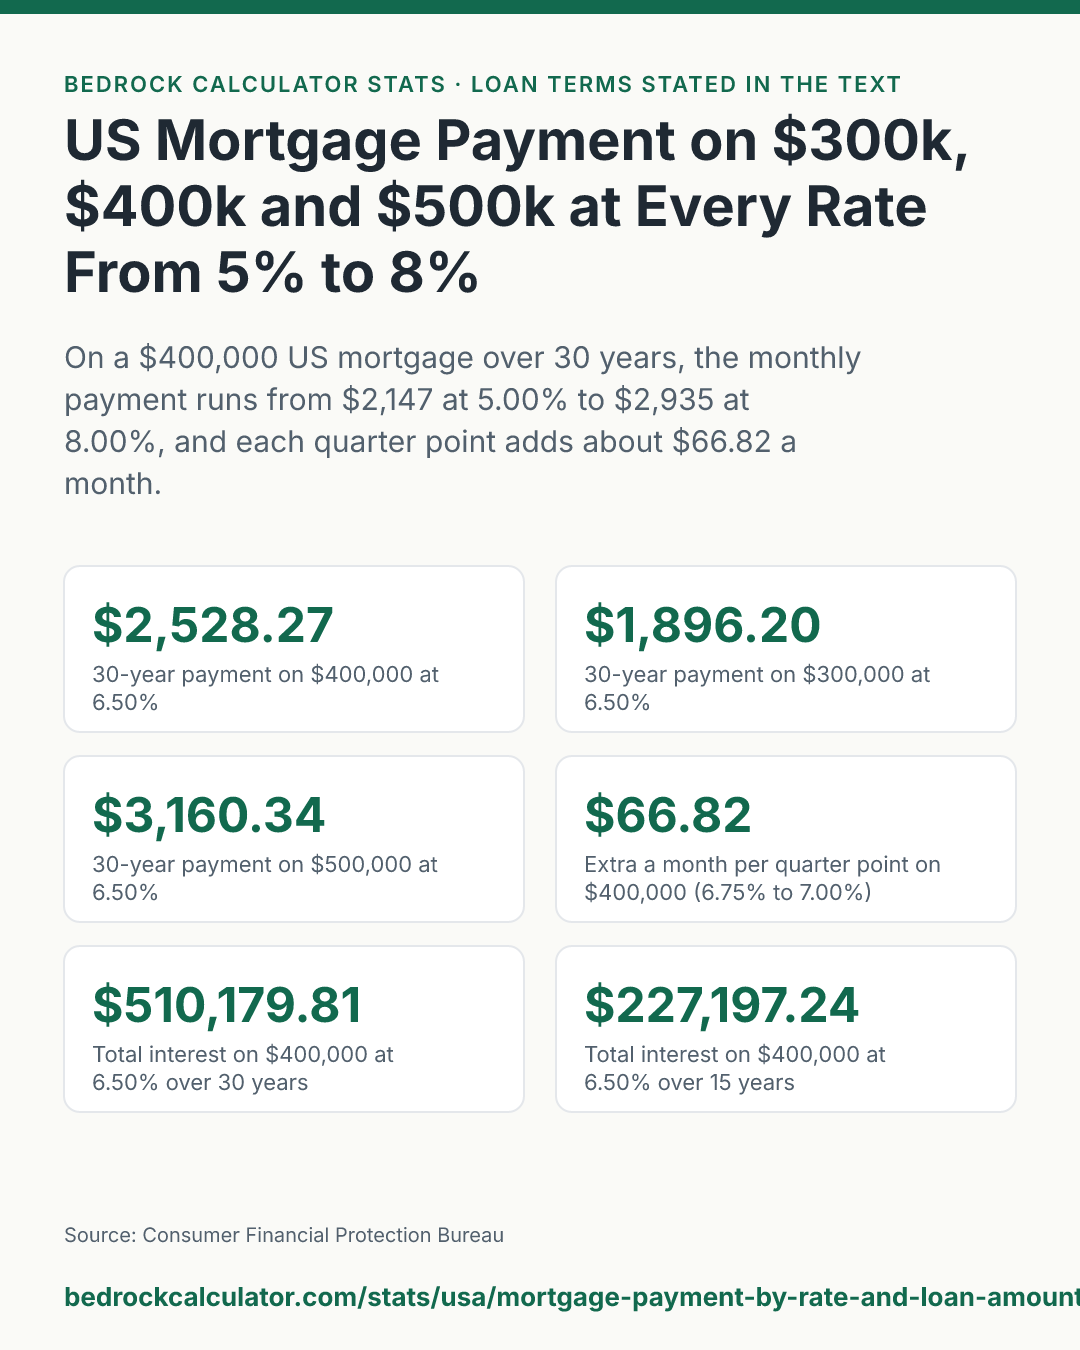
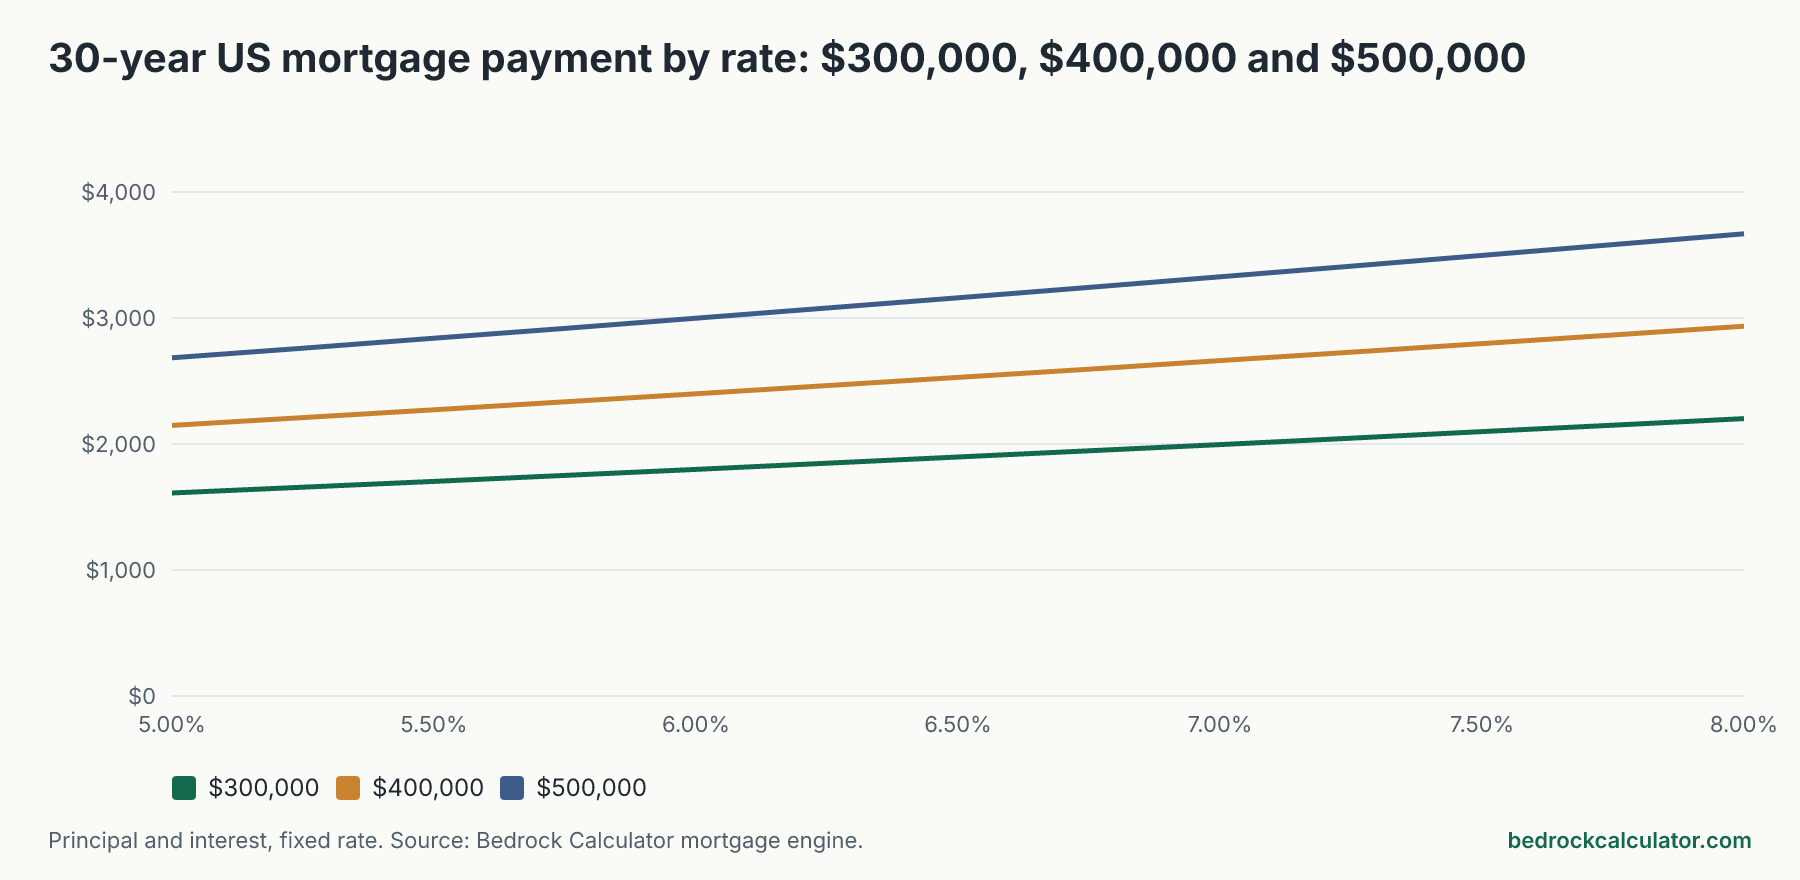
On a $400,000 US mortgage over 30 years, principal and interest costs $2,147.29 a month at 5.00%, $2,528.27 at 6.50% and $2,935.06 at 8.00%. Every quarter point adds roughly $66.82 a month, or about $801.84 a year.
Over the life of the loan the rate matters even more. Total interest on that $400,000 runs from $373,021.33 at 5.00% to $656,619.15 at 8.00%, a difference of $283,597.82.
What this page is for
Most people shopping for a home in the US have two numbers in mind: roughly how much they'll borrow and the rate a lender quoted. This page is a lookup table for exactly that. Find your loan size and your rate, and you can read off the monthly payment and the total interest you'd pay if you kept the loan to the end.
We cover the three loan sizes people search for most, $300,000, $400,000 and $500,000, at all 13 quarter-point rates from 5.00% to 8.00%, on both 15-year and 30-year fixed terms. If you want to compare the two terms in depth, our 15-year vs 30-year mortgage comparison goes further into equity and balances.
How we worked out these numbers
Every figure comes from the mortgage calculator on this site. We ran it once for each loan size, rate and term, and recorded the monthly principal and interest and the total interest over the schedule.
The calculator works from a home price and a down payment, so each loan was entered as a purchase with 20% down. That makes the loan exactly $300,000, $400,000 or $500,000, and it means no private mortgage insurance. Interest accrues monthly at one twelfth of the annual rate, and the payment is rounded to the cent the way a lender's note would be, so the final payment is a few cents different from the rest.
Here is what the figures leave out:
- Property tax and homeowners insurance. Both are paid on top of the figures here, and in high-tax states they add a lot. Our page on the monthly cost of a $400,000 home in every US state adds them in.
- PMI. With less than 20% down, a conventional loan adds private mortgage insurance until the balance falls far enough.
- HOA dues and closing costs. Neither is in these numbers.
- APR versus note rate. The rate here is the note rate. A quoted APR also spreads fees and points over the loan, so it's a little higher than the rate that sets your payment.
- Adjustable-rate loans. Everything here is a fixed rate for the whole term.
Monthly payment on a 30-year mortgage at every rate
Sort by any column. The first three columns are the monthly payment, the last three the total interest over 30 years if every payment is made on schedule.
Monthly principal and interest on a 30-year fixed US mortgage
Download CSVPrincipal and interest only. Property tax, homeowners insurance, PMI and HOA dues are extra.
| 5.00% | $1,610.46 | $2,147.29 | $2,684.11 | $279,769.69 | $373,021.33 | $466,278.27 |
| 5.25% | $1,656.61 | $2,208.81 | $2,761.02 | $296,380.39 | $395,175.65 | $493,966.10 |
| 5.50% | $1,703.37 | $2,271.16 | $2,838.95 | $313,210.43 | $417,614.29 | $522,017.33 |
| 5.75% | $1,750.72 | $2,334.29 | $2,917.86 | $330,257.96 | $440,345.85 | $550,433.57 |
| 6.00% | $1,798.65 | $2,398.20 | $2,997.75 | $347,515.44 | $463,354.10 | $579,192.69 |
| 6.25% | $1,847.15 | $2,462.87 | $3,078.59 | $364,975.79 | $486,632.23 | $608,288.31 |
| 6.50% | $1,896.20 | $2,528.27 | $3,160.34 | $382,636.71 | $510,179.81 | $637,722.20 |
| 6.75% | $1,945.79 | $2,594.39 | $3,242.99 | $400,489.69 | $533,983.09 | $667,476.96 |
| 7.00% | $1,995.91 | $2,661.21 | $3,326.51 | $418,524.05 | $558,035.91 | $697,546.97 |
| 7.25% | $2,046.53 | $2,728.71 | $3,410.88 | $436,749.23 | $582,329.20 | $727,918.62 |
| 7.50% | $2,097.64 | $2,796.86 | $3,496.07 | $455,155.38 | $606,866.84 | $758,589.03 |
| 7.75% | $2,149.24 | $2,865.65 | $3,582.06 | $473,721.42 | $631,632.55 | $789,543.43 |
| 8.00% | $2,201.29 | $2,935.06 | $3,668.82 | $492,470.60 | $656,619.15 | $820,779.23 |
A few reference points. On $300,000, the 30-year payment is $1,798.65 at 6.00% and $1,995.91 at 7.00%. On $500,000 it's $2,997.75 at 6.00% and $3,326.51 at 7.00%.
What a quarter point really costs you
A quarter point sounds small. On a $400,000 30-year loan, going from 6.75% to 7.00% adds $66.82 to every payment. Over the whole move from 5.00% to 8.00% the payment climbs by $787.77 a month.
Put another way: the rate can matter as much as the price. A $500,000 loan at 5.75% costs $2,917.86 a month, which is less than a $400,000 loan at 8.00%. That's why buying points or waiting for a better rate can be worth doing the math on. Our mortgage points break-even page shows how long it takes to earn back the cost of a lower rate.
At 5.00%, the interest on a 30-year $400,000 loan adds up to 93.3% of the amount borrowed. At 8.00% it's 164.2%, so you'd repay more than two and a half times what you borrowed.
Monthly payment on a 15-year mortgage
Monthly principal and interest on a 15-year fixed US mortgage
Download CSVPrincipal and interest only. Property tax, homeowners insurance, PMI and HOA dues are extra.
| 5.00% | $2,372.38 | $3,163.17 | $3,953.97 | $127,028.69 | $169,371.80 | $211,714.02 |
| 5.25% | $2,411.63 | $3,215.51 | $4,019.39 | $134,094.28 | $178,792.01 | $223,489.80 |
| 5.50% | $2,451.25 | $3,268.33 | $4,085.42 | $141,225.11 | $188,300.49 | $235,374.86 |
| 5.75% | $2,491.23 | $3,321.64 | $4,152.05 | $148,421.55 | $197,895.31 | $247,369.12 |
| 6.00% | $2,531.57 | $3,375.43 | $4,219.28 | $155,682.79 | $207,576.56 | $259,471.59 |
| 6.25% | $2,572.27 | $3,429.69 | $4,287.11 | $163,008.18 | $217,344.58 | $271,681.03 |
| 6.50% | $2,613.32 | $3,484.43 | $4,355.54 | $170,398.28 | $227,197.24 | $283,996.31 |
| 6.75% | $2,654.73 | $3,539.64 | $4,424.55 | $177,850.86 | $237,134.59 | $296,418.12 |
| 7.00% | $2,696.48 | $3,595.31 | $4,494.14 | $185,367.94 | $247,156.90 | $308,945.71 |
| 7.25% | $2,738.59 | $3,651.45 | $4,564.31 | $192,945.75 | $257,261.44 | $321,577.32 |
| 7.50% | $2,781.04 | $3,708.05 | $4,635.06 | $200,586.24 | $267,448.68 | $334,311.41 |
| 7.75% | $2,823.83 | $3,765.10 | $4,706.38 | $208,288.45 | $277,719.07 | $347,147.98 |
| 8.00% | $2,866.96 | $3,822.61 | $4,778.26 | $216,051.29 | $288,069.23 | $360,086.92 |
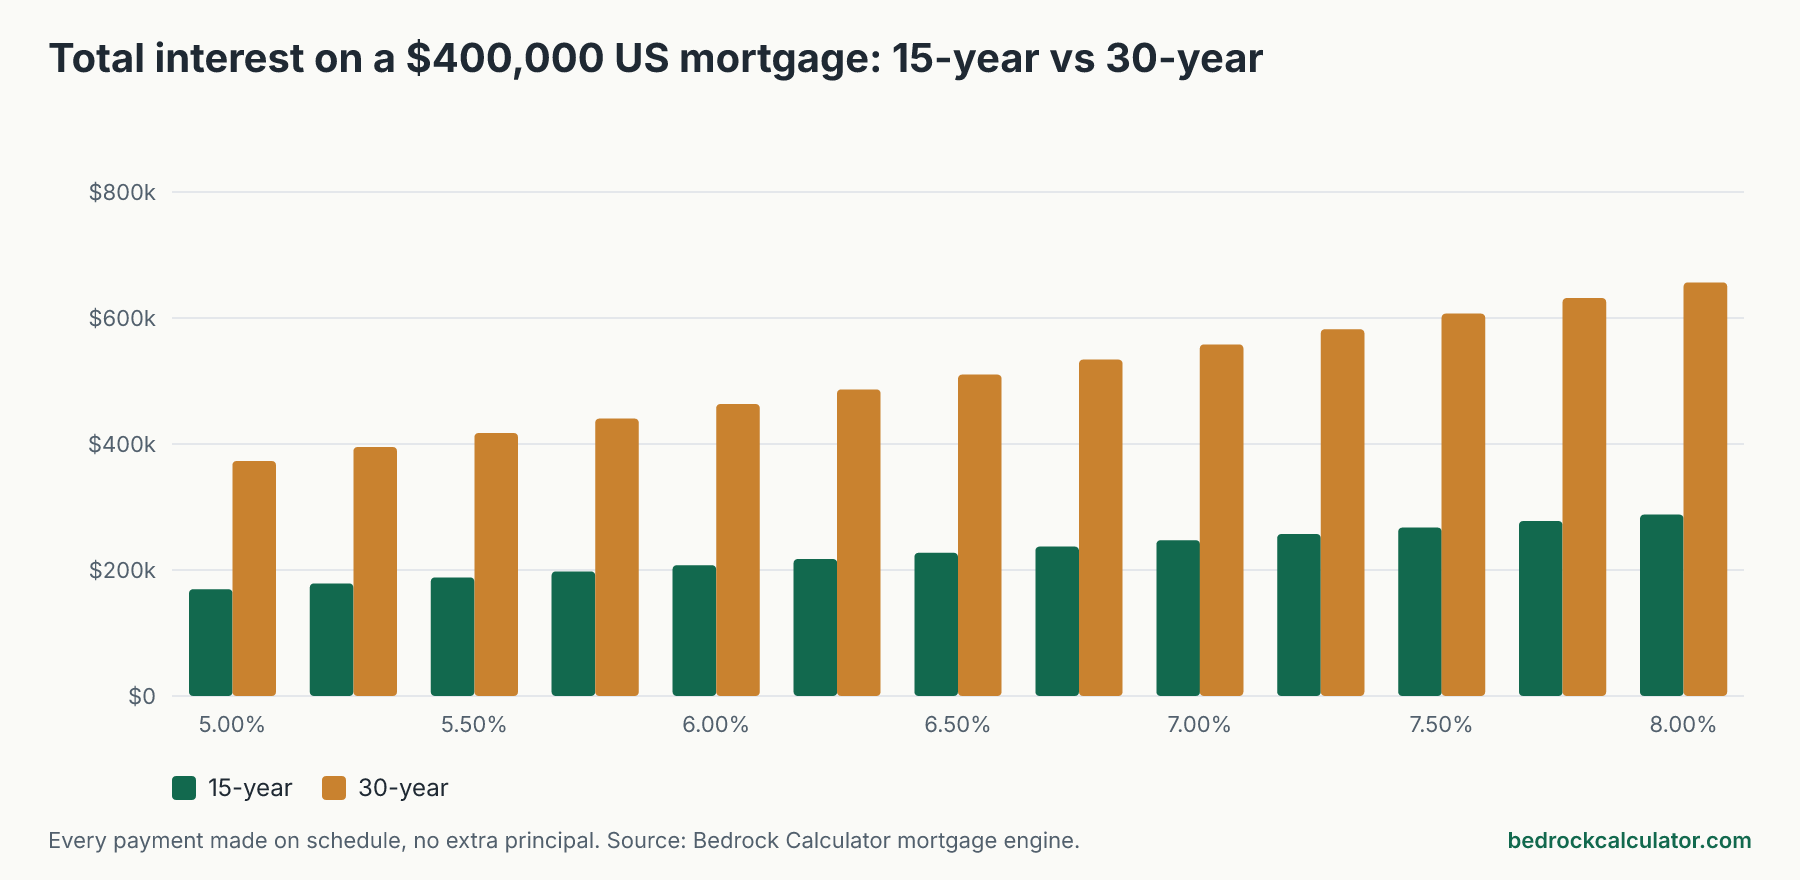
The 15-year payment is much higher, but the interest bill is a fraction of the 30-year one. On $400,000 at 6.50%, the 15-year loan costs $3,484.43 a month, which is $956.16 more than the 30-year, and it saves $282,982.57 in interest.
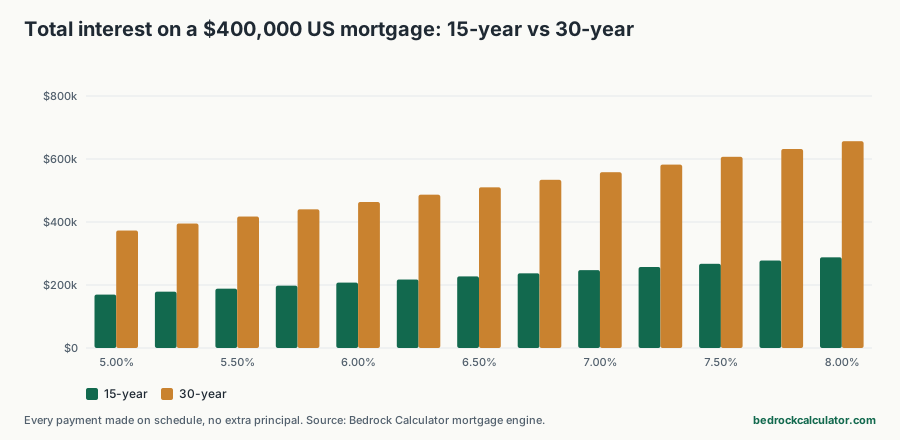
Total interest, 15-year against 30-year
The gap between the two bars grows as rates rise. At 5.00%, a $400,000 loan costs $169,371.80 in interest over 15 years and $373,021.33 over 30. At 8.00% those become $288,069.23 and $656,619.15. Higher rates punish the long term more, because interest compounds on a balance that shrinks slowly in the early years. You can see how slowly in our breakdown of how much of each payment is interest, year by year.
How to use these numbers
If you already know your loan amount and rate, read the payment straight from the table, then add your property tax, insurance and any PMI or HOA dues to get the real monthly cost. If your loan falls between two sizes, the payment scales in a straight line with the amount borrowed, so a loan halfway between two columns has a payment halfway between them.
For your exact numbers, enter your price, down payment and rate in the mortgage calculator. To see the full payment-by-payment schedule, use the loan amortization calculator. If you're deciding how big a loan you can carry, start with the house affordability calculator, and if you already have a mortgage at a higher rate, the refinance calculator shows when switching pays off.