How much Social Security is withheld if you work before full retirement age?
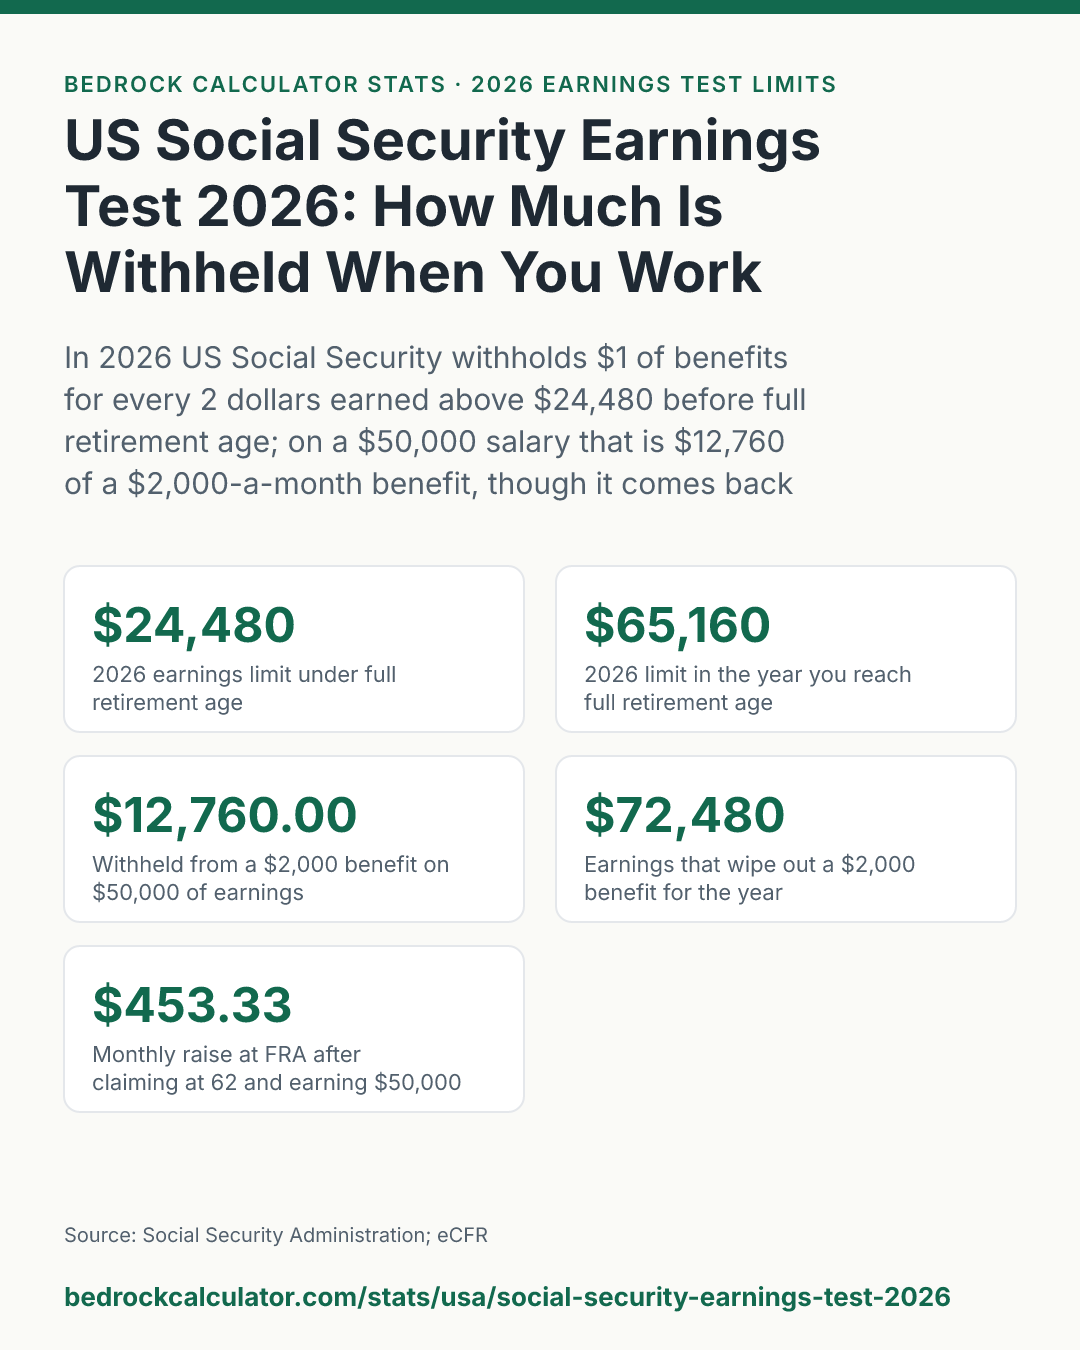
If you claim US Social Security before full retirement age and keep working, the earnings test can hold back part of your benefit. In 2026 the limit is $24,480 a year. Above it, Social Security withholds $1 of benefits for every 2 dollars you earn.
In the calendar year you reach full retirement age the limit jumps to $65,160, and only $1 in every 3 dollars above it is withheld.
On $50,000 of earnings that's $12,760.00 withheld from a $2,000-a-month benefit in a full year before your full retirement age year. The money isn't lost. Once you reach full retirement age, your monthly check goes up permanently to make up for it.
The 2026 earnings test limits
The Social Security Administration sets the two limits each year in its cost-of-living notice. For 2026:
- Under full retirement age for the whole year: $24,480 a year, or $2,040 a month. $1 is withheld for every 2 dollars above the limit.
- The year you reach full retirement age: $65,160 a year, or $5,430 a month. $1 is withheld for every 3 dollars above the limit, and only earnings before the month you reach that age count.
- From the month you reach full retirement age: no limit at all. You can earn any amount.
Only money from work counts: wages and net self-employment earnings. Pensions, annuities, interest, dividends, capital gains and IRA withdrawals don't.
How much is withheld at each income
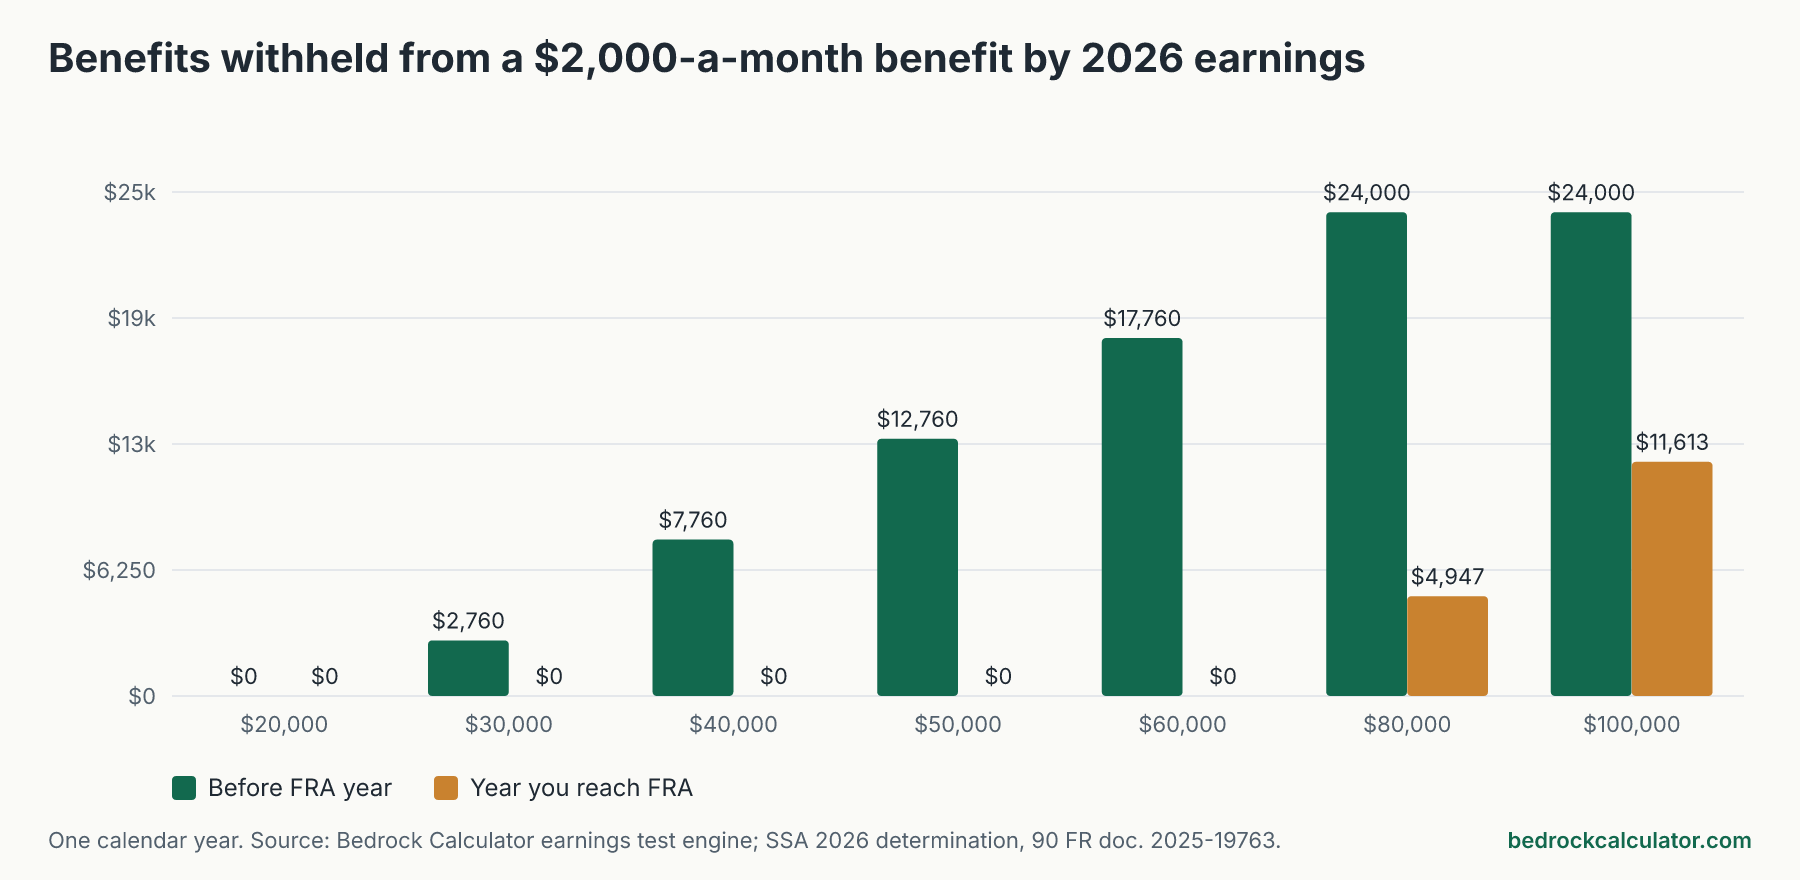
Sort by any column. Each row is one calendar year, so the withholding depends only on how far your earnings are over the limit, until it runs out of benefit to withhold.
Social Security benefits withheld by the 2026 earnings test (US)
Download CSVOne calendar year. "Before FRA year" uses the lower exempt amount and $1 for $2; "FRA year" uses the higher amount and $1 for $3, applied to the whole year's earnings.
| $20,000 | $1,500 | $0.00 | 0 | $0.00 |
| $20,000 | $2,000 | $0.00 | 0 | $0.00 |
| $20,000 | $2,500 | $0.00 | 0 | $0.00 |
| $30,000 | $1,500 | $2,760.00 | 2 | $0.00 |
| $30,000 | $2,000 | $2,760.00 | 2 | $0.00 |
| $30,000 | $2,500 | $2,760.00 | 2 | $0.00 |
| $40,000 | $1,500 | $7,760.00 | 6 | $0.00 |
| $40,000 | $2,000 | $7,760.00 | 4 | $0.00 |
| $40,000 | $2,500 | $7,760.00 | 4 | $0.00 |
| $50,000 | $1,500 | $12,760.00 | 9 | $0.00 |
| $50,000 | $2,000 | $12,760.00 | 7 | $0.00 |
| $50,000 | $2,500 | $12,760.00 | 6 | $0.00 |
| $60,000 | $1,500 | $17,760.00 | 12 | $0.00 |
| $60,000 | $2,000 | $17,760.00 | 9 | $0.00 |
| $60,000 | $2,500 | $17,760.00 | 8 | $0.00 |
| $80,000 | $1,500 | $18,000.00 | 12 | $4,946.67 |
| $80,000 | $2,000 | $24,000.00 | 12 | $4,946.67 |
| $80,000 | $2,500 | $27,760.00 | 12 | $4,946.67 |
| $100,000 | $1,500 | $18,000.00 | 12 | $11,613.33 |
| $100,000 | $2,000 | $24,000.00 | 12 | $11,613.33 |
| $100,000 | $2,500 | $30,000.00 | 12 | $11,613.33 |
Two things stand out. First, in a year before your full retirement age year, the amount withheld is the same whatever your benefit, until it eats the whole year's benefit. On $40,000 of earnings it's $7,760.00 whether you get $1,500 or $2,500 a month. What changes is how many months that takes: 6 months of a $1,500 check against 4 of a $2,500 one.
Second, the full-retirement-age year is much gentler. At $80,000 of earnings, a $2,000-a-month benefit loses the whole year, $24,000.00, in an earlier year. In the year you reach full retirement age it loses $4,946.67. Below $65,160 it loses nothing.
Social Security withholds whole monthly checks until it has held back enough, so in practice you'll see checks stop for a few months rather than shrink. The table's month column shows how many. If the whole checks add up to more than was due, the difference is paid back to you.
You get the withheld money back
This is the part most people miss. At full retirement age, Social Security recalculates your benefit as if you'd claimed later, leaving out every month that was withheld. The smaller early-claiming reduction raises your check for the rest of your life.
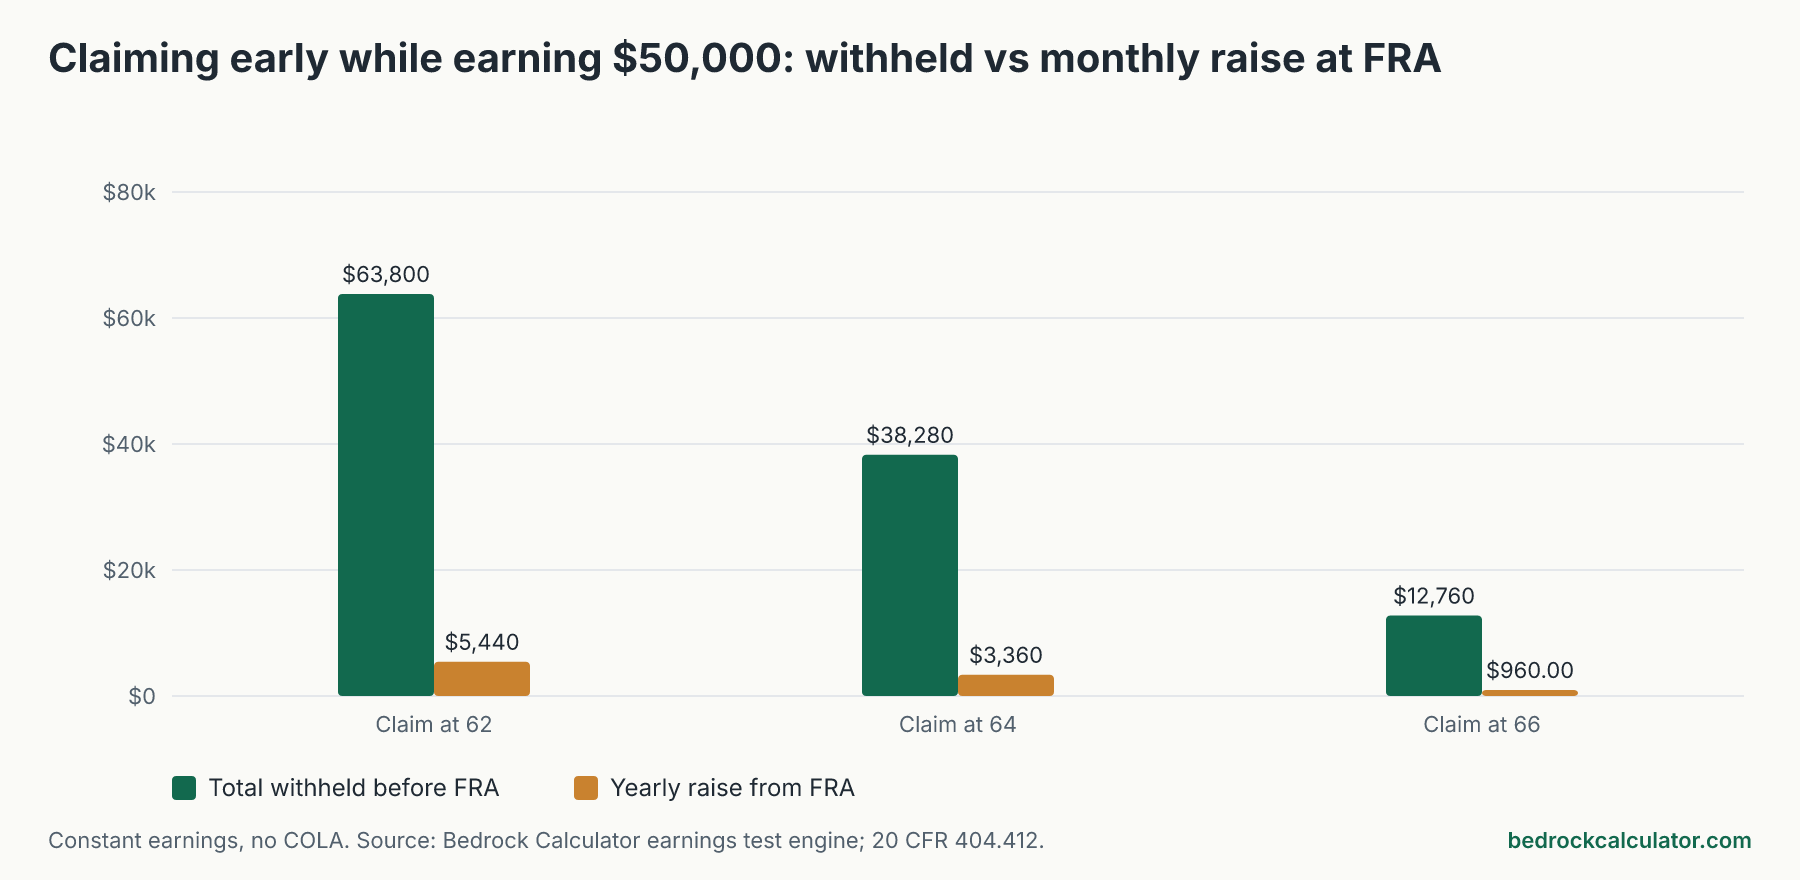
Take a worker born in 1964, whose full retirement age is 67 years, with a full benefit of $2,400 a month, who earns $50,000 a year until then:
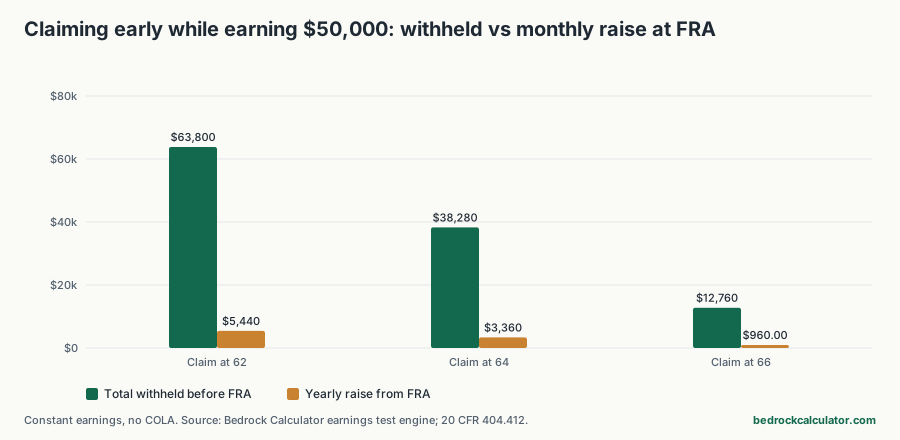
- Claim at 62: the check is $1,680.00. Over the years to full retirement age, $63,800.00 is withheld, covering 40 months. At full retirement age the check rises to $2,133.33, a raise of $453.33 a month. It takes about 11.8 years of the higher check to earn back what was withheld.
- Claim at 64: $38,280.00 is withheld over 21 months. The check goes from $1,920.00 to $2,200.00, and the break-even is about 11.4 years.
- Claim at 66: $12,760.00 is withheld over 6 months, and the check rises from $2,240.00 to $2,320.00.
So the earnings test works more like a delay than a penalty. Whether it's a good trade depends on how long you live past full retirement age, which is the same question as when to claim in the first place. Our page on claiming Social Security at 62, 67 or 70 works through that.
How we worked out these numbers
The one-year figures in the table and first chart come from the same earnings test function the Social Security earnings test calculator runs for each year, using SSA's 2026 limits. The claim-age example is the calculator itself, run with the inputs listed above.
What the calculator leaves out:
- The monthly cutoff in your full retirement age year. Only earnings before the month you reach that age count. The calculator applies the higher limit to the whole year's earnings, which overstates the withholding for someone who works all year.
- The first-year monthly test. In your first year of benefits, you can be paid for any month in which you earn under the monthly limit, whatever you earn in the year. That isn't modeled.
- Cost-of-living increases. Benefits are held flat, and the break-even years are in today's dollars.
- Changing earnings. Earnings are the same every year in the projection.
- Taxes on benefits, a higher benefit from extra years of work, and spousal or survivor benefits, which can also be withheld because of your earnings.
Run your own numbers
Enter your full benefit, birth year, claiming age and expected earnings in the Social Security earnings test calculator to see what's withheld each year and what comes back. The Social Security breakeven calculator shows how your benefit changes with claiming age. And if you're working part-time to bridge to full retirement age, the paycheck calculator shows what that job leaves you after tax.