How much can you put into a retirement account in each country?
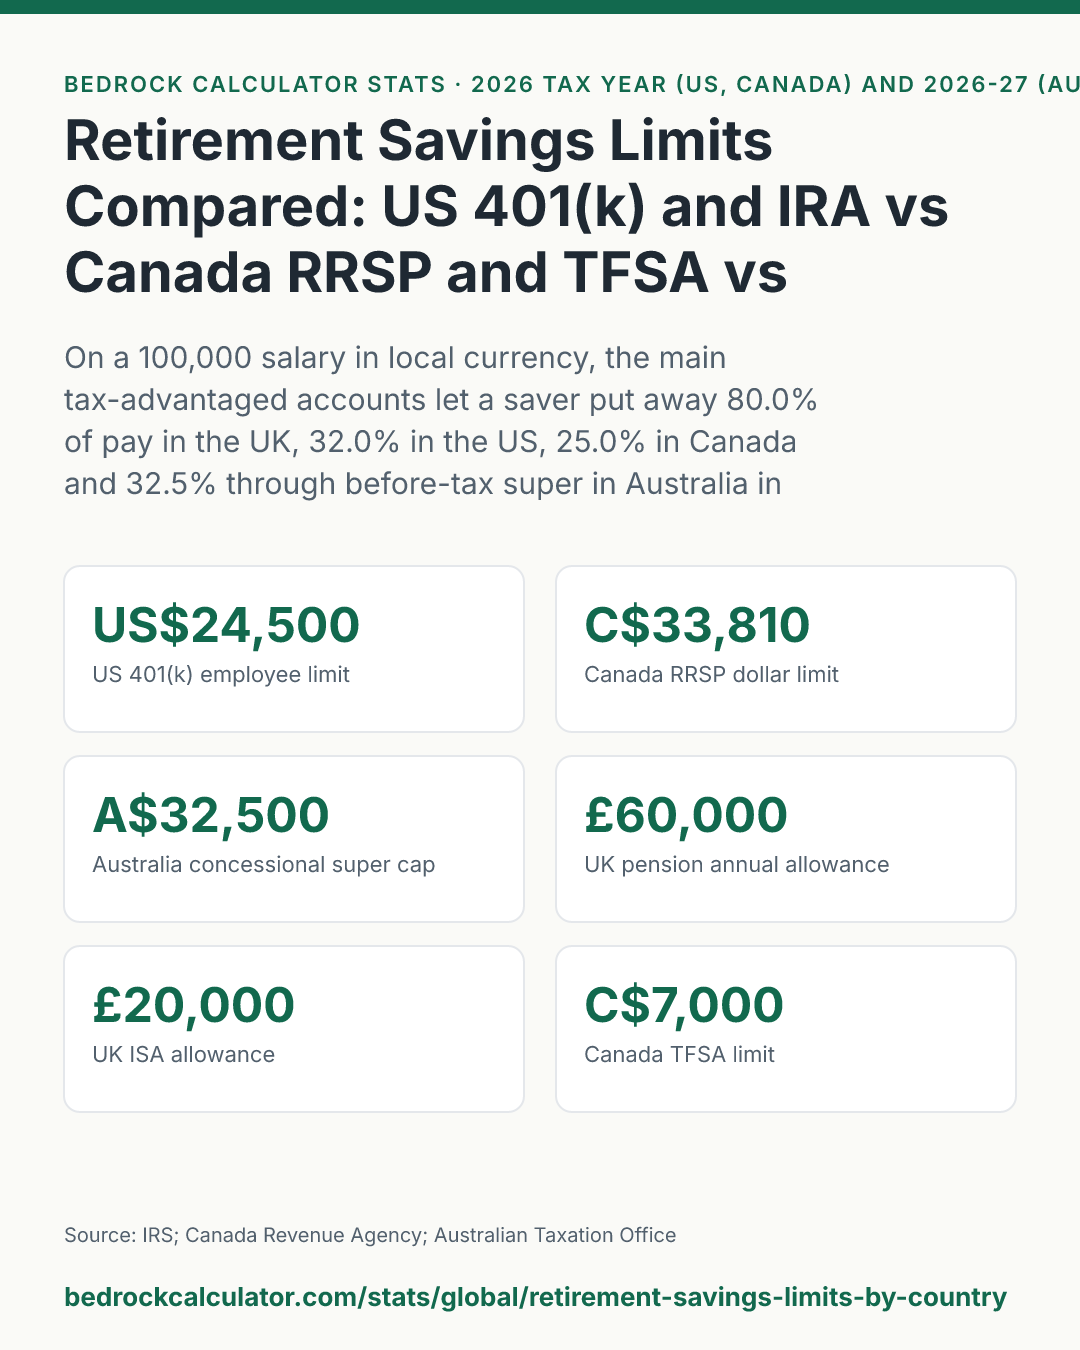
The US, Canada, Australia and the UK all reward saving for retirement with tax breaks, but they cap it in very different ways. In 2026 a US employee can put US$24,500 into a 401(k) and US$7,500 into an IRA. A Canadian gets RRSP room of 18% of last year's earnings, up to C$33,810, plus C$7,000 in a TFSA.
In Australia the before-tax super cap for 2026-27 is A$32,500, employer contributions included. In the UK the pension annual allowance is £60,000, with £20,000 more in an ISA.
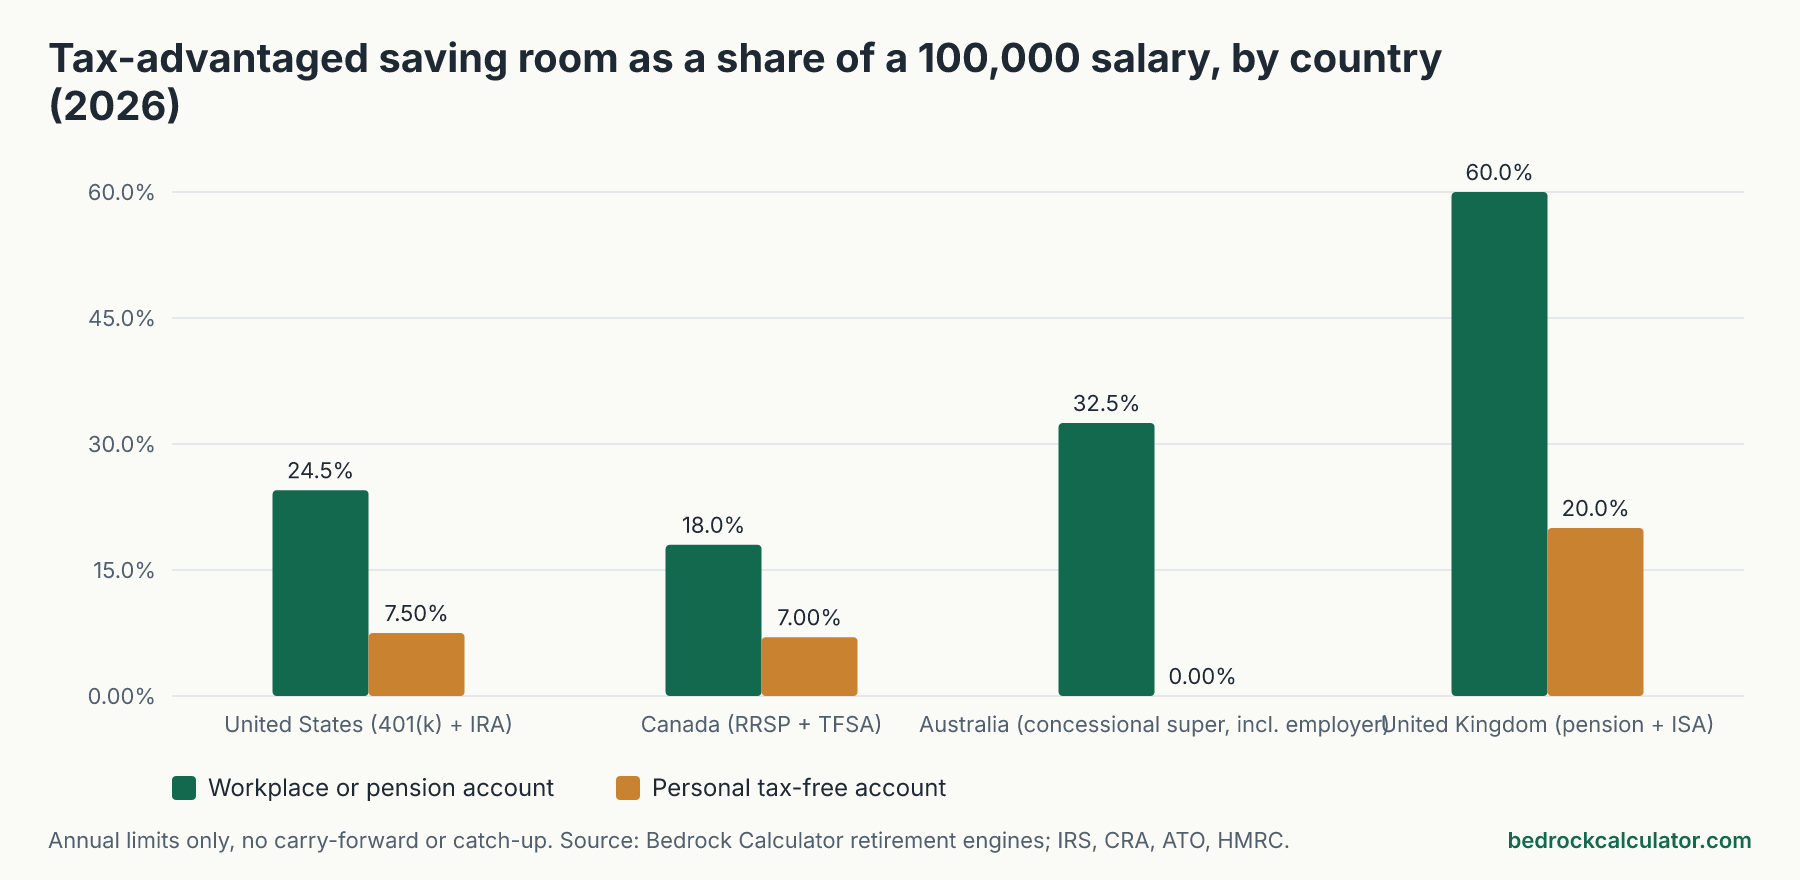
Measured against a 100,000 salary in each country's own currency, the UK's limits are by far the most generous: pension plus ISA room comes to 80.0% of pay, against 32.0% in the US, 25.0% in Canada and 32.5% through before-tax super in Australia.
How we worked out these numbers
Every limit here comes from the constants and functions that power the site's own calculators: the 401(k) calculator and Roth IRA calculator for the US, the RRSP calculator and TFSA calculator for Canada, the superannuation calculator for Australia, and the pension annual allowance calculator and ISA allowance calculator for the UK. We didn't type any limit ourselves.
Each figure stays in its own currency, because a dollar, a pound and an Australian dollar aren't the same thing. To compare across countries we used one simple measure: how much of a salary of 100,000, in local currency, each country's main accounts let you shelter in a year. That's a share of pay, so it needs no exchange rate. It ignores carry-forward of unused room and age-based catch-up, which we cover separately below.
The years differ too. US and Canadian limits run on the 2026 calendar year. Australia's run from 1 July 2026 to 30 June 2027, and the UK's from 6 April 2026 to 5 April 2027.
Australia's 2026-27 caps match the Australian Taxation Office's contributions caps page: A$32,500 concessional and A$130,000 non-concessional.
Every limit, side by side
Click any column heading to sort. Each amount is in the currency shown.
Retirement and tax-free savings limits: US, Canada, Australia, UK (2026)
Download CSVAnnual limits in each country's own currency for the 2026 tax year (US, Canada), 2026-27 income year (Australia, 1 July to 30 June) and 2026-27 tax year (UK, 6 April to 5 April).
| Australia | Super: concessional (before-tax) cap | AUD | 32,500 | Unused cap carries forward 5 years if balance under the threshold | Includes employer Super Guarantee; taxed in the fund |
| Australia | Super: non-concessional (after-tax) cap | AUD | 130,000 | Bring-forward of up to 3 years | After-tax money; not taxed on the way in |
| Canada | RRSP | CAD | 33,810 | Unused room carries forward | 18% of prior-year earned income, up to the dollar limit |
| Canada | TFSA | CAD | 7,000 | Unused room carries forward | After-tax in, tax-free out |
| United Kingdom | Pension annual allowance | GBP | 60,000 | 3 years of unused allowance carry forward | All contributions incl. employer; personal relief capped at 100% of earnings |
| United Kingdom | ISA allowance | GBP | 20,000 | Use it or lose it | After-tax in, tax-free out |
| United Kingdom | Lifetime ISA (inside the ISA allowance) | GBP | 4,000 | None | Government bonus up to £1,000 a year; open by 39 |
| United States | 401(k), 403(b), governmental 457(b): employee deferral | USD | 24,500 | US$8,000 at 50+, US$11,250 at 60 to 63 | Pre-tax or Roth; workplace plan |
| United States | 401(k): all contributions including employer | USD | 72,000 | Catch-up on top | Overall annual additions limit |
| United States | Traditional or Roth IRA | USD | 7,500 | US$1,100 at 50+ | Individual account; deduction and Roth eligibility depend on income |
401(k) vs UK pension: which lets you save more?
The UK pension annual allowance of £60,000 is the single largest limit here, and it counts everything going in: your contributions, your employer's, and salary sacrifice. You can't get tax relief on personal contributions above your earnings, so on a £100,000 salary the full £60,000 is available.
The US splits it differently. The 401(k) employee limit of US$24,500 covers what you defer from your own pay. Employer matches sit on top, inside a separate overall limit of US$72,000. So on employee money alone, the UK lets you save 60.0% of a 100,000 salary against 24.5% in the US.
High earners in the UK face a taper. Once both threshold income and adjusted income pass set levels, the allowance shrinks; someone with £300,000 of adjusted income in our model has £40,000, and the floor is £10,000.
RRSP vs 401(k)
An RRSP is tied to earnings rather than a flat figure. You get 18% of last year's earned income, up to C$33,810. On C$100,000 that's C$18,000 of new room, which is 18.0% of pay. The dollar cap only starts to bite at around C$187,833 of earned income. Unlike the 401(k), unused RRSP room carries forward indefinitely, so someone who skips a few years can catch up later at any age.
ISA vs Roth IRA vs TFSA
These three work the same way: you pay in money you've already been taxed on, and everything that comes out later is tax free.
The UK ISA allowance of £20,000 is the most generous, and it isn't limited to retirement saving. Inside it, a Lifetime ISA takes up to £4,000 a year with a government bonus of up to £1,000, for people who open one by age 39.
Canada's TFSA allows C$7,000 a year, but unused room carries forward from 2009, so someone who has been eligible since then has C$109,000 of total room. The Roth IRA allows US$7,500, or US$8,600 from age 50, and only below income limits that this comparison doesn't cover.
Australian super and the before-tax cap
Australia's system is built around compulsory employer contributions. The concessional cap of A$32,500 includes the employer's Super Guarantee at 12.0% of salary. On A$100,000 the employer puts in A$12,000, so the worker has A$20,500 left for salary sacrifice or personal deductible contributions. That's why the Australian share in our chart is the whole cap: it already counts the employer.
Australians can also add after-tax money up to A$130,000 a year, the non-concessional cap, which is the largest single figure in the table, though it gets no tax break on the way in.
Catch-up: where age changes the answer
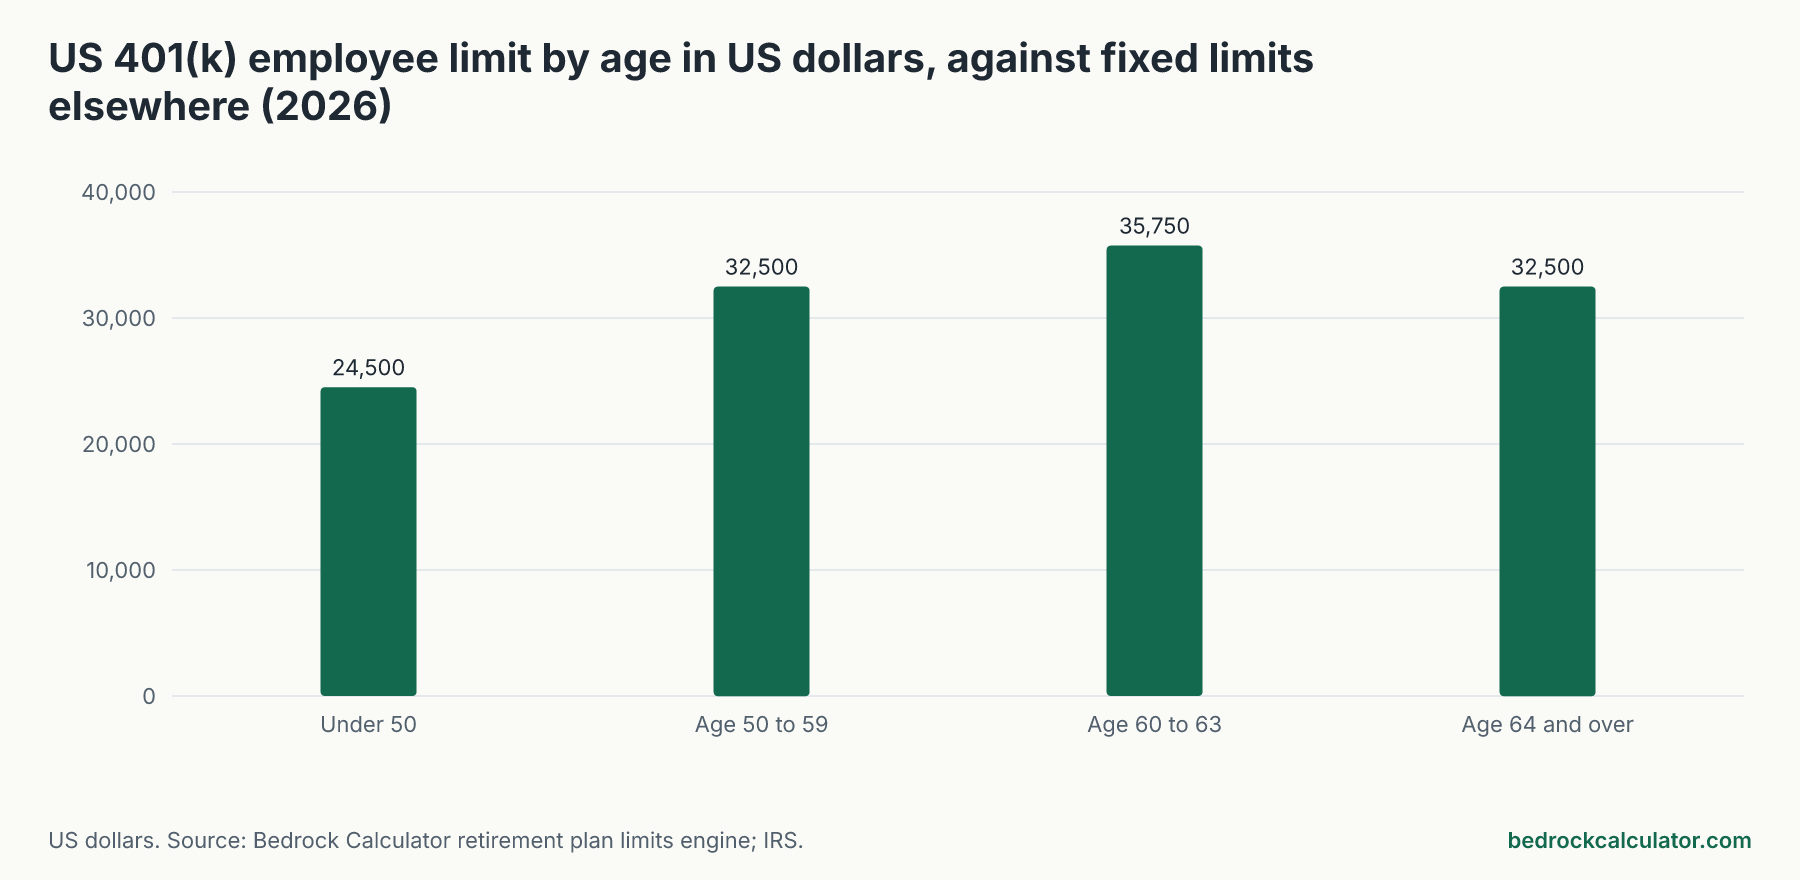
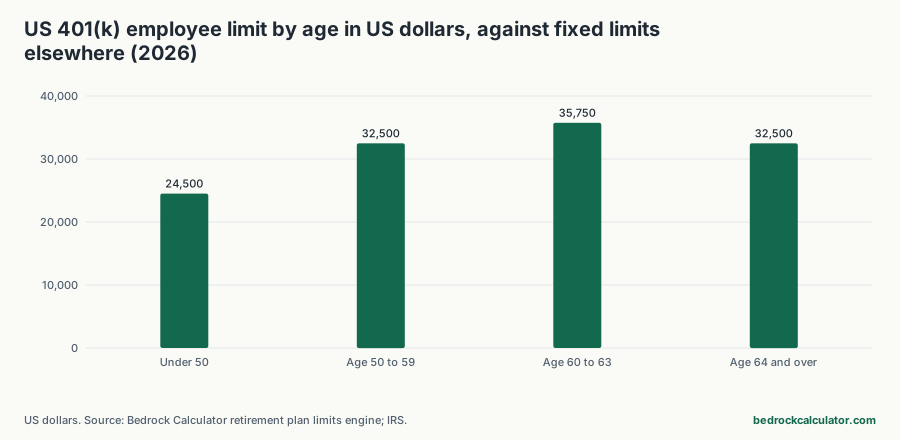
Only the US raises its limits at a fixed age. From 50, the 401(k) limit rises by US$8,000 to US$32,500. Between 60 and 63, a larger catch-up of US$11,250 applies instead, taking the limit to US$35,750. Canada, Australia and the UK don't use age-based catch-up; they let you carry unused room forward instead, three years in the UK, five years for Australian concessional super (for balances under a threshold), and indefinitely for the RRSP and TFSA.
For the full set of US limits, including HSAs, SEP IRAs and 403(b) service catch-up, see our 2026 US retirement contribution limits.
Getting your own figure
Each calculator linked above takes your own salary and age. If you're a UK earner deciding between pension and ISA, our figures on salary sacrifice savings show how much tax and National Insurance a workplace pension saves at each salary.