How much more does a longer car loan or a lower credit score cost?
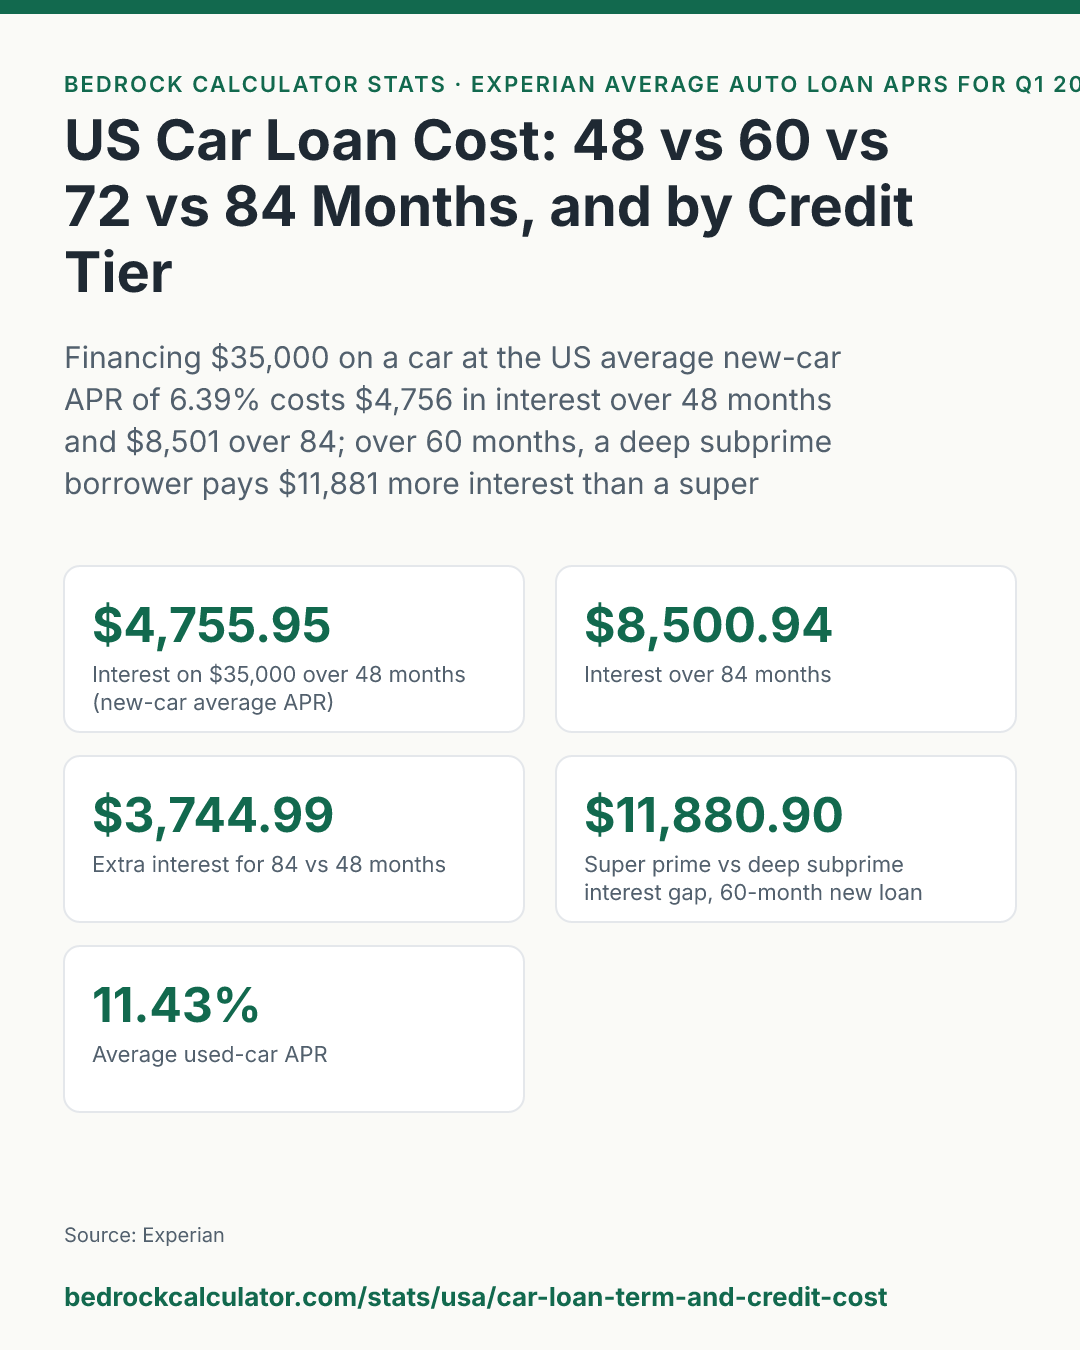
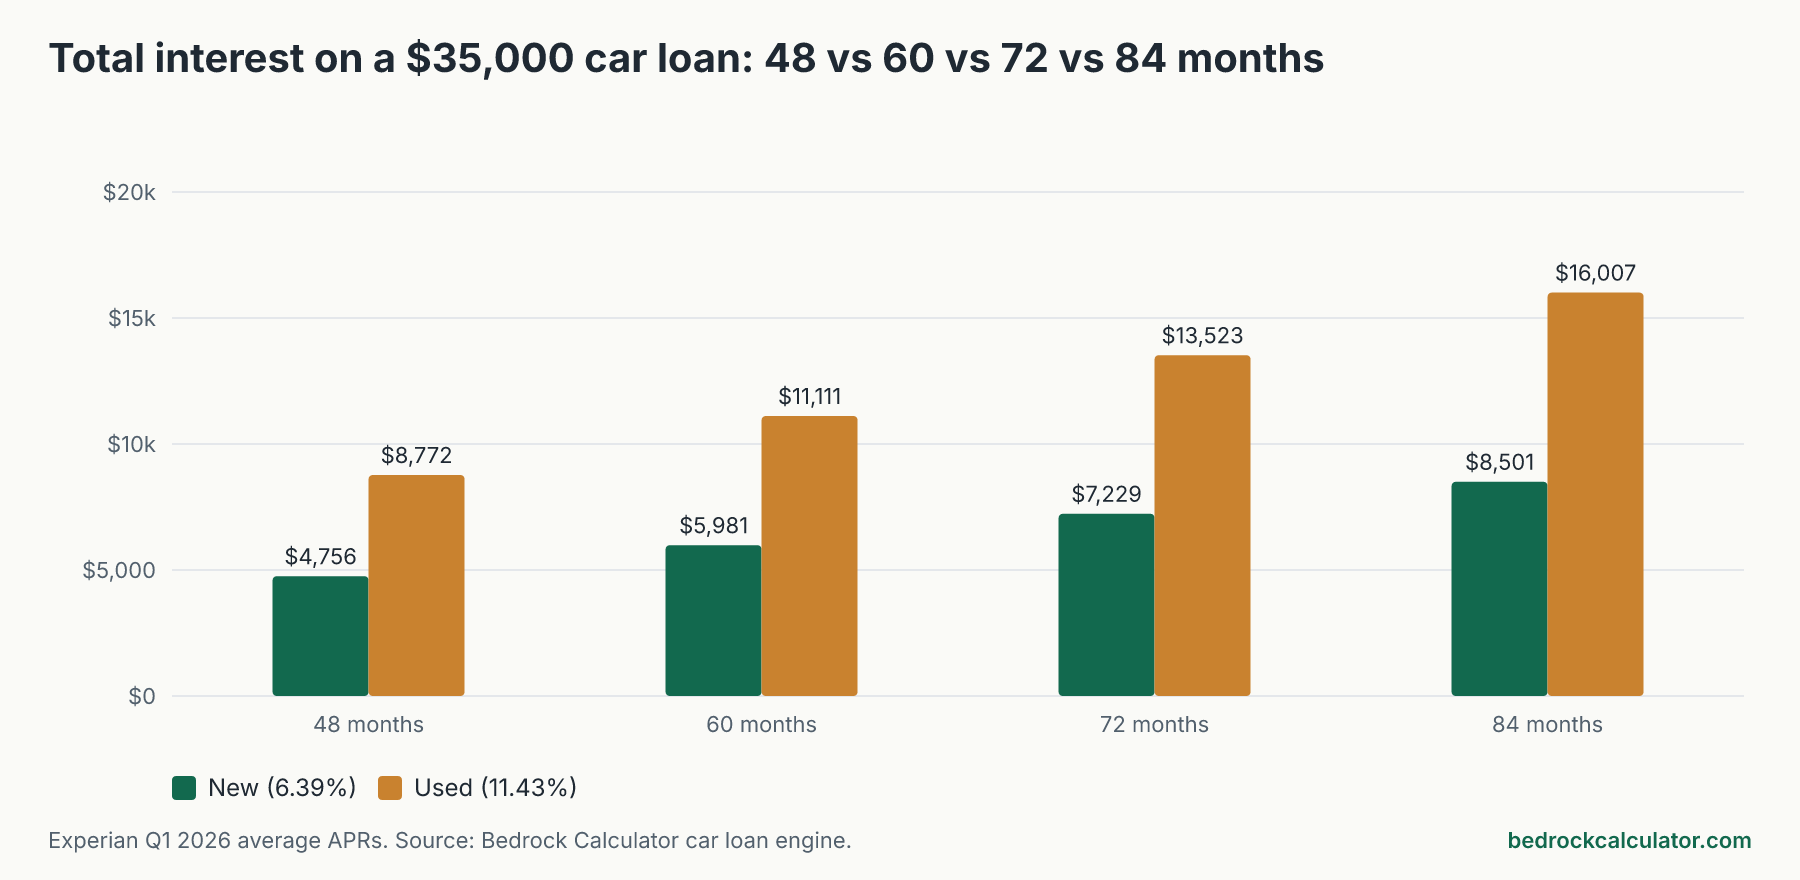
Finance $35,000 on a new car in the US at the average new-car APR of 6.39%, and a 48-month loan costs $4,755.95 in interest. Stretch it to 84 months and the interest rises to $8,500.94, $3,744.99 more, in exchange for a payment that's $310.38 a month lower.
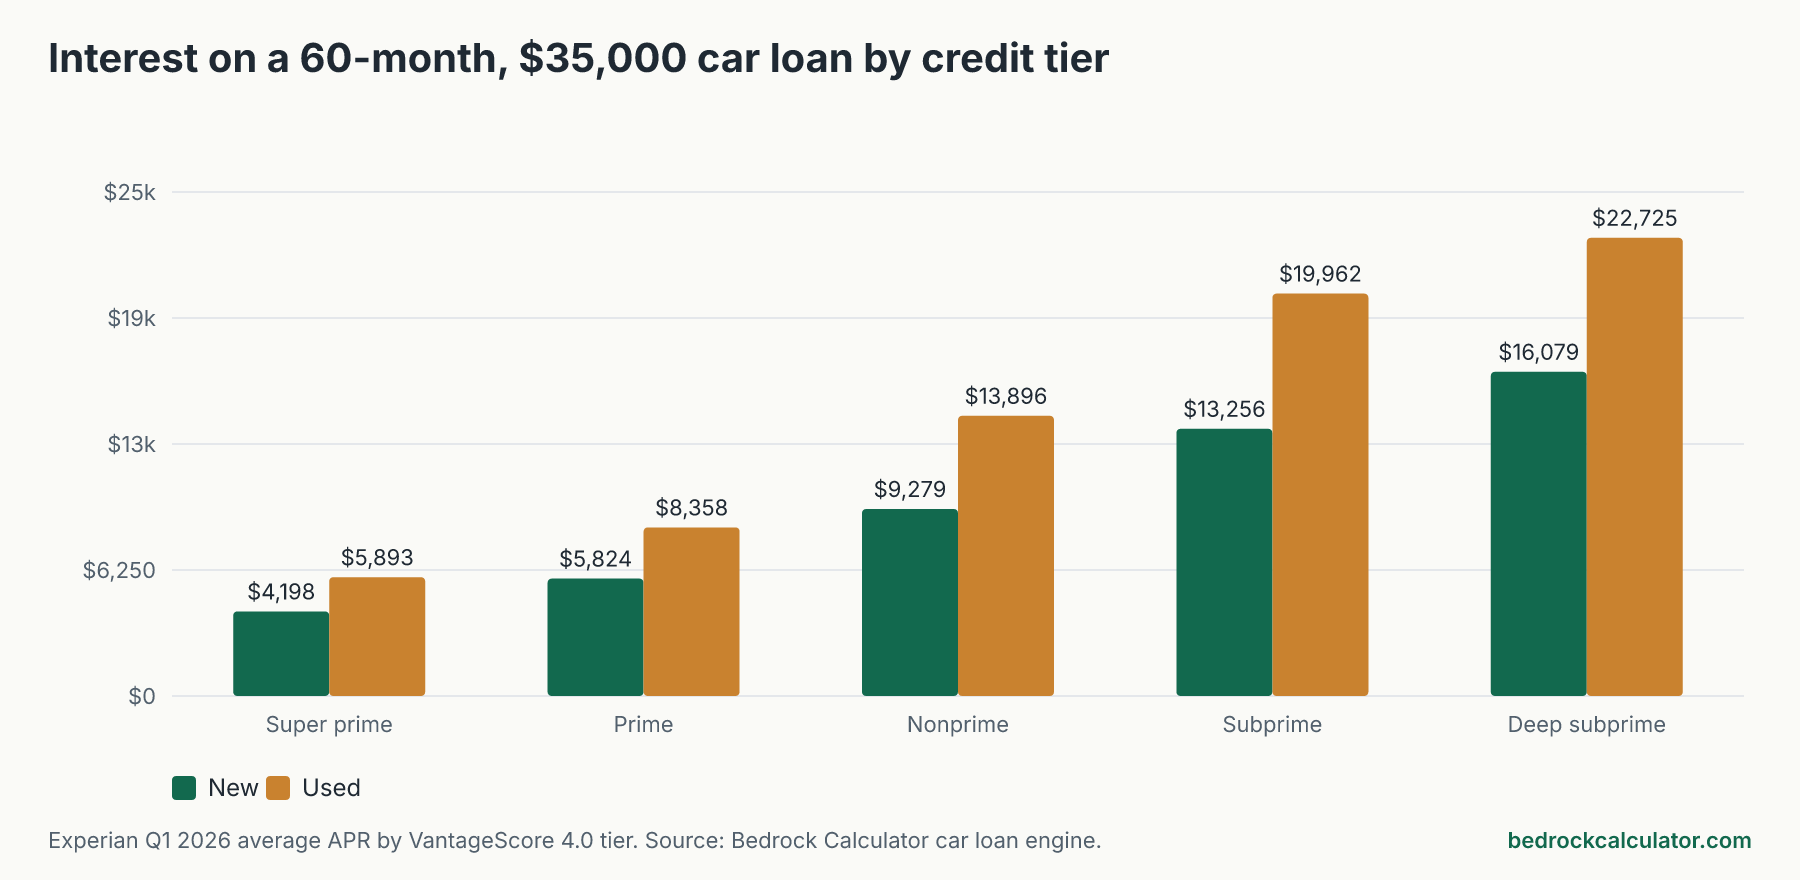
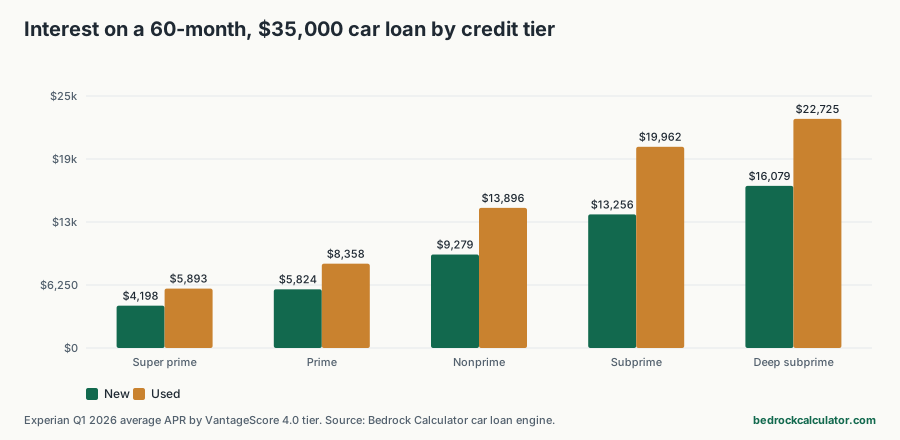
Your credit matters even more than the term. On a 60-month new-car loan, a borrower in the top credit tier pays $4,198.13 in interest. A borrower in the bottom tier pays $16,079.03, a gap of $11,880.90 on the same car.
How we worked out these numbers
Every figure comes from the car loan calculator on this site, on a $40,000 car with $5,000 down, leaving $35,000 to finance. The calculator works out a fixed monthly payment that repays the loan over the term, with interest charged monthly at one twelfth of the APR.
The interest rates come from Experian's State of the Automotive Finance Market report for Q1 2026, the latest edition with figures by credit tier. Experian reports an average APR of 6.39% for new-car loans and 11.43% for used-car loans, plus an average for each of five credit tiers. These are national averages; Experian doesn't break them out by state.
Experian sorts borrowers by VantageScore 4.0, not by FICO score. The same person can land in a different tier on each scale, so treat the score bands as a guide only.
48 vs 60 vs 72 vs 84 months
Car loan payment and interest on $35,000 by term
Download CSV$40,000 car, $5,000 down. New at Experian's average new-car APR (6.39%), used at the average used-car APR (11.43%), Q1 2026.
| 48 months | $828.25 | $4,755.95 | $911.92 | $8,772.14 |
| 60 months | $683.01 | $5,980.84 | $768.51 | $11,110.76 |
| 72 months | $586.52 | $7,229.09 | $673.93 | $13,522.62 |
| 84 months | $517.87 | $8,500.94 | $607.23 | $16,007.06 |
Each extra year on the loan lowers the payment, but by less each time, while the interest keeps climbing. On a new car at 6.39%, going from 48 to 60 months cuts the payment by $145.24 a month and adds $1,224.89 of interest. Going from 72 to 84 months cuts it by only $68.65 but adds $1,271.85.
The used-car column shows the same pattern at a higher rate. At 11.43%, an 84-month used-car loan on $35,000 costs $16,007.06 in interest, $7,234.92 more than over 48 months.
There's a second cost of long loans that this table doesn't show. Cars lose value fastest in their first few years, and a long loan pays down the balance slowly. On a 72 or 84-month loan, it's common to owe more than the car is worth for years. If it's totaled or you need to sell, you'd have to cover the difference.
What your credit tier costs
Car loan cost on $35,000 over 60 months by credit tier
Download CSVExperian average APR by VantageScore 4.0 tier, Q1 2026. National averages; these are VantageScore bands, not FICO ranges.
| Deep subprime | 300-500 | 16.01% | $851.32 | $16,079.03 | 21.77% | $962.09 | $22,725.42 |
| Nonprime | 601-660 | 9.67% | $737.98 | $9,278.50 | 14.03% | $814.93 | $13,896.15 |
| Prime | 661-780 | 6.23% | $680.40 | $5,823.83 | 8.77% | $722.64 | $8,358.49 |
| Subprime | 501-600 | 13.44% | $804.26 | $13,255.81 | 19.42% | $916.03 | $19,961.52 |
| Super prime | 781-850 | 4.55% | $653.30 | $4,198.13 | 6.3% | $681.54 | $5,892.50 |
On a 60-month new-car loan, the payment ranges from $653.30 for super prime borrowers (781-850) to $851.32 for deep subprime (300-500). That's $198.02 more every month for the same car.
The used-car gap is bigger still, because used-car rates run higher at every tier. A deep subprime borrower at 21.77% pays $22,725.42 in interest on a 60-month used-car loan of $35,000; a super prime borrower at 6.3% pays $5,892.50.
How to pay less
- Shorten the term if the payment allows. The 48 and 60-month rows cost far less in total than 72 or 84.
- Improve your credit before you shop. Each tier up the table comes with a lower average rate. Paying down card balances and fixing errors on your report can help.
- Get a preapproval. A quote from a bank or credit union gives you a rate to compare against the dealer's offer.
- Put more down. A larger down payment shrinks the loan and the interest, and lowers the risk of owing more than the car is worth.
What this leaves out
- Rates that change with the term. We used the same average APR at every term. Lenders often charge more for longer loans, so the real gap between 48 and 84 months is usually wider than shown.
- Sales tax, fees and trade-ins. The car loan calculator finances the price minus the down payment only. The auto loan calculator adds sales tax, dealer fees and trade-in value.
- Your actual rate. These are national averages for each tier. Your offer depends on your full credit history, income, the car and the lender.
- Depreciation and insurance. Neither is part of the loan math.
Run your own numbers
Plug your price, down payment, rate and term into the car loan calculator, or use the auto loan calculator to include tax, fees and a trade-in. If you're deciding between an electric and a gas car, see our EV vs gas total cost of ownership comparison.