What APR do payday and title loans really charge?
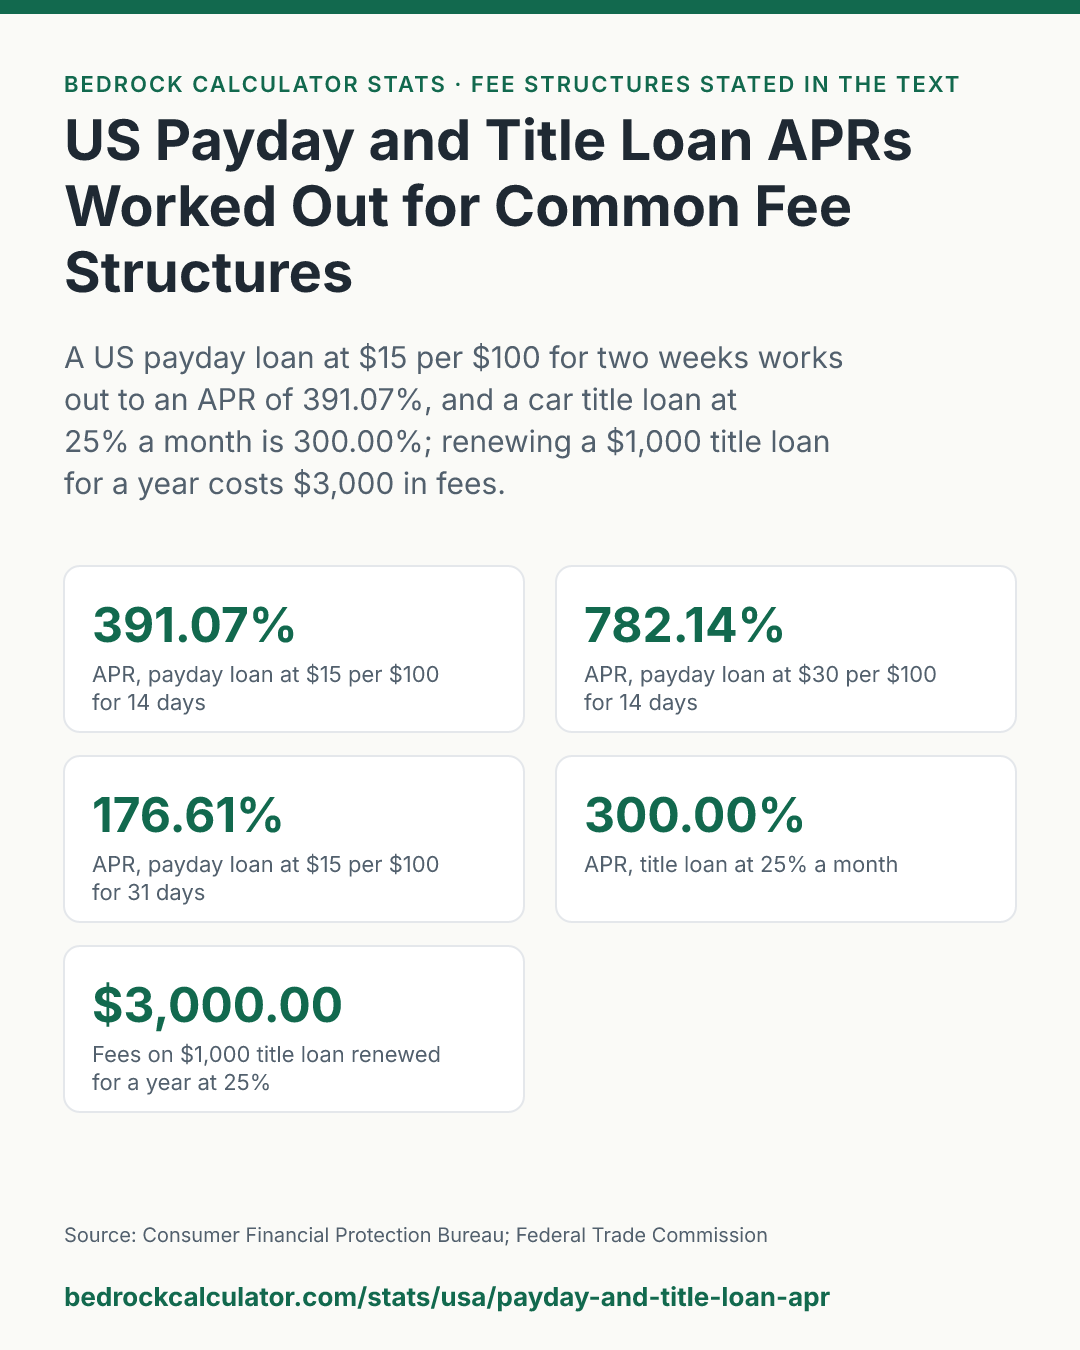
A US payday loan that charges $15 per $100 borrowed for two weeks has an annual percentage rate of 391.07%. At $30 per $100, the top of the range many state laws allow, it's 782.14%. A car title loan at 25% a month works out to 300.00% a year.
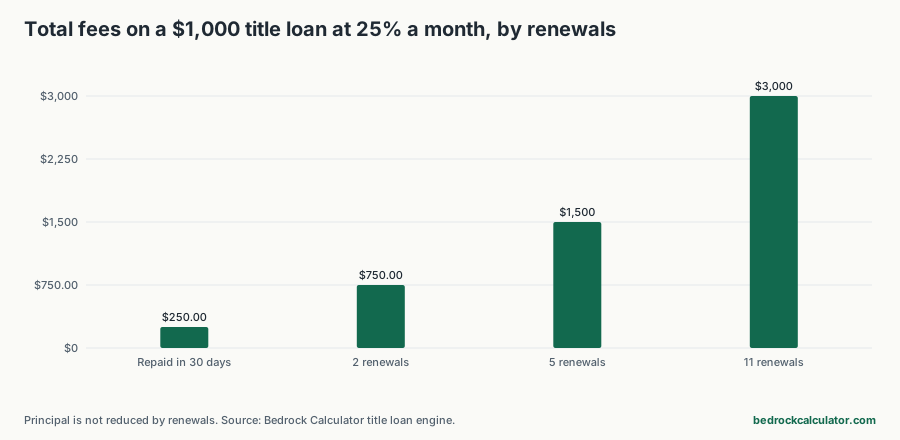
Those rates look abstract until you count the dollars. Renew a $1,000 title loan every month for a year at 25% and you pay $3,000.00 in fees, then still owe the original $1,000.
How we worked out these numbers
We used two calculators on this site.
The payday loan APR calculator takes the amount borrowed, the fee per $100 and the number of days until the loan is due. It turns the flat fee into an APR the same way federal Truth in Lending disclosures do: the fee divided by the amount borrowed, multiplied by 365 divided by the number of days. We ran a $400 advance at fees from $10 to $30 per $100, for 14 days (a typical two-week pay cycle) and 31 days.
The title loan calculator takes the amount borrowed against your car title, a flat monthly finance charge and the number of 30-day renewals. Each renewal charges the full fee again without paying down any principal. We ran $1,000 at 10%, 15%, 20% and 25% a month, repaid after the first month or renewed 2, 5 or 11 times.
Payday loans: every fee and term
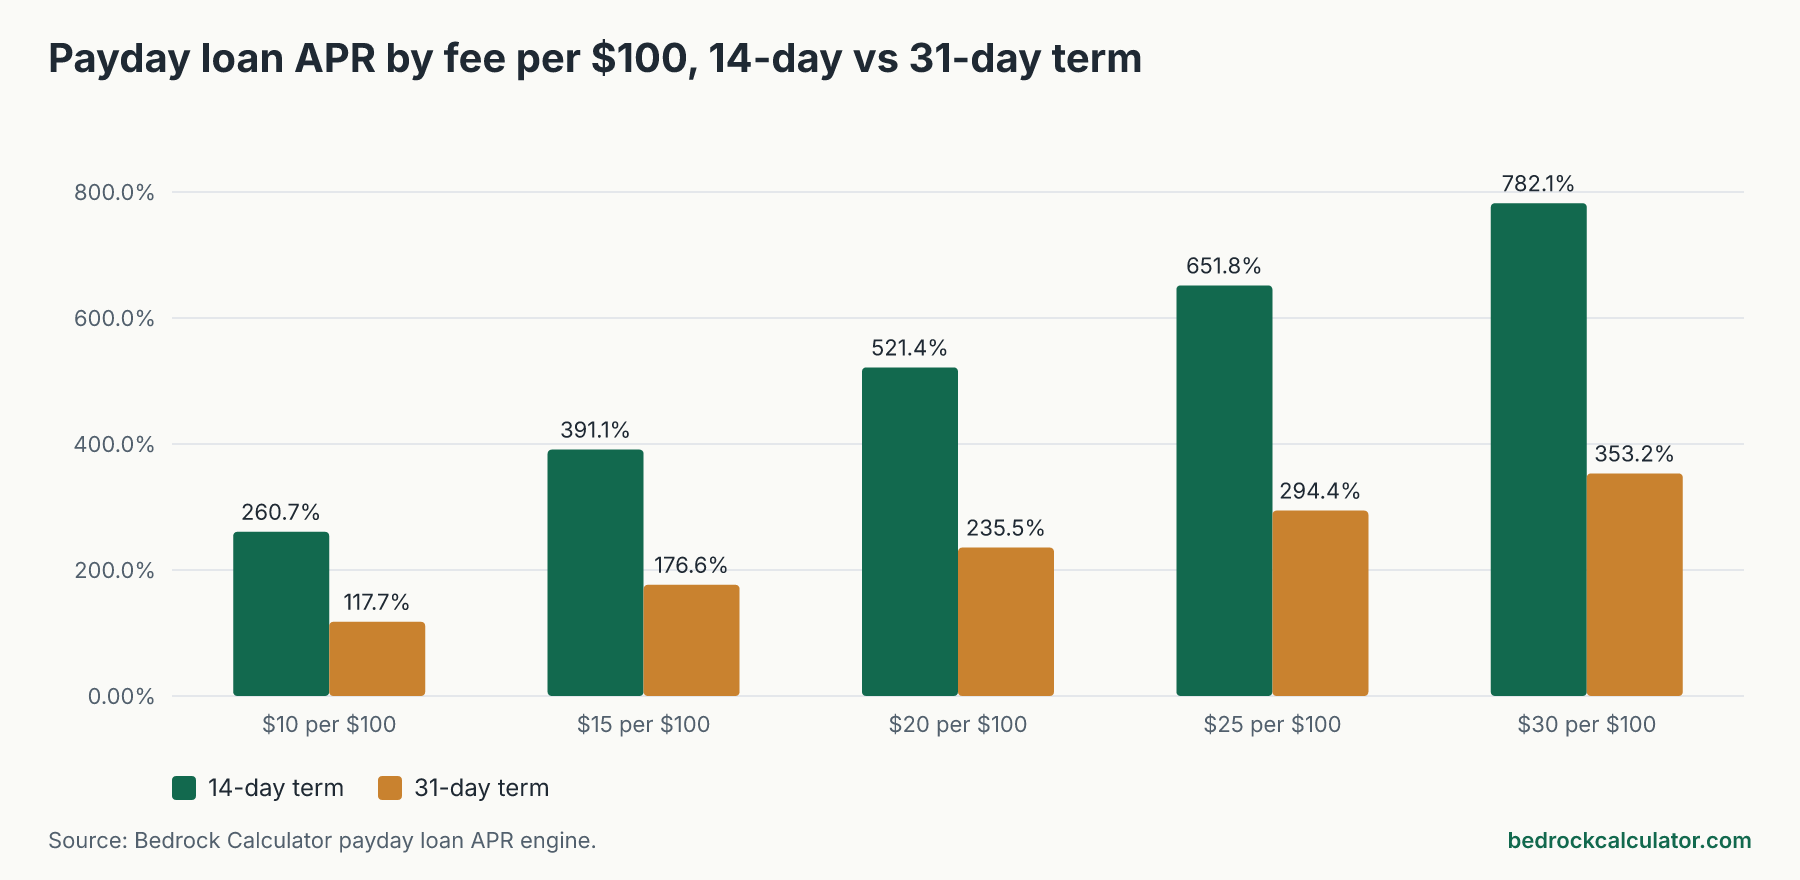
Payday loan APR by fee per $100 and loan length ($400 advance)
Download CSVAPR = fee divided by amount borrowed, times 365 divided by the days in the term. The last column compounds the same loan if it were rolled over back to back for a year.
| $10 | 31 | $40.00 | $440.00 | 117.74% | 207.16% |
| $15 | 31 | $60.00 | $460.00 | 176.61% | 418.40% |
| $20 | 31 | $80.00 | $480.00 | 235.48% | 755.65% |
| $10 | 14 | $40.00 | $440.00 | 260.71% | 1099.96% |
| $25 | 31 | $100.00 | $500.00 | 294.35% | 1283.69% |
| $30 | 31 | $120.00 | $520.00 | 353.23% | 2095.79% |
| $15 | 14 | $60.00 | $460.00 | 391.07% | 3723.66% |
| $20 | 14 | $80.00 | $480.00 | 521.43% | 11497.60% |
| $25 | 14 | $100.00 | $500.00 | 651.79% | 33518.82% |
| $30 | 14 | $120.00 | $520.00 | 782.14% | 93368.65% |
The fee is the same whether you borrow for 14 days or 31. On $400 at $15 per $100 it's $60.00 either way. What changes is how long you have the money, and that's why the APR on the 14-day loan (391.07%) is more than twice the 31-day one (176.61%). The shorter the term, the higher the annual rate the same fee implies.
Why payday APRs are so high
A $60.00 fee on $400 doesn't feel like much. But you're paying it for two weeks of borrowing. Repeat that 26 times a year and you'd pay far more than the amount you borrowed. That's what an APR of 391.07% means.
The last column in the table goes one step further. It shows what happens if you roll the loan over every two weeks for a full year, paying a new fee each time on a growing amount. At $15 per $100 that compounds to 3723.66%. Few people roll over for a whole year, but repeat borrowing is common, and every rollover adds another fee.
Car title loans: what renewals cost
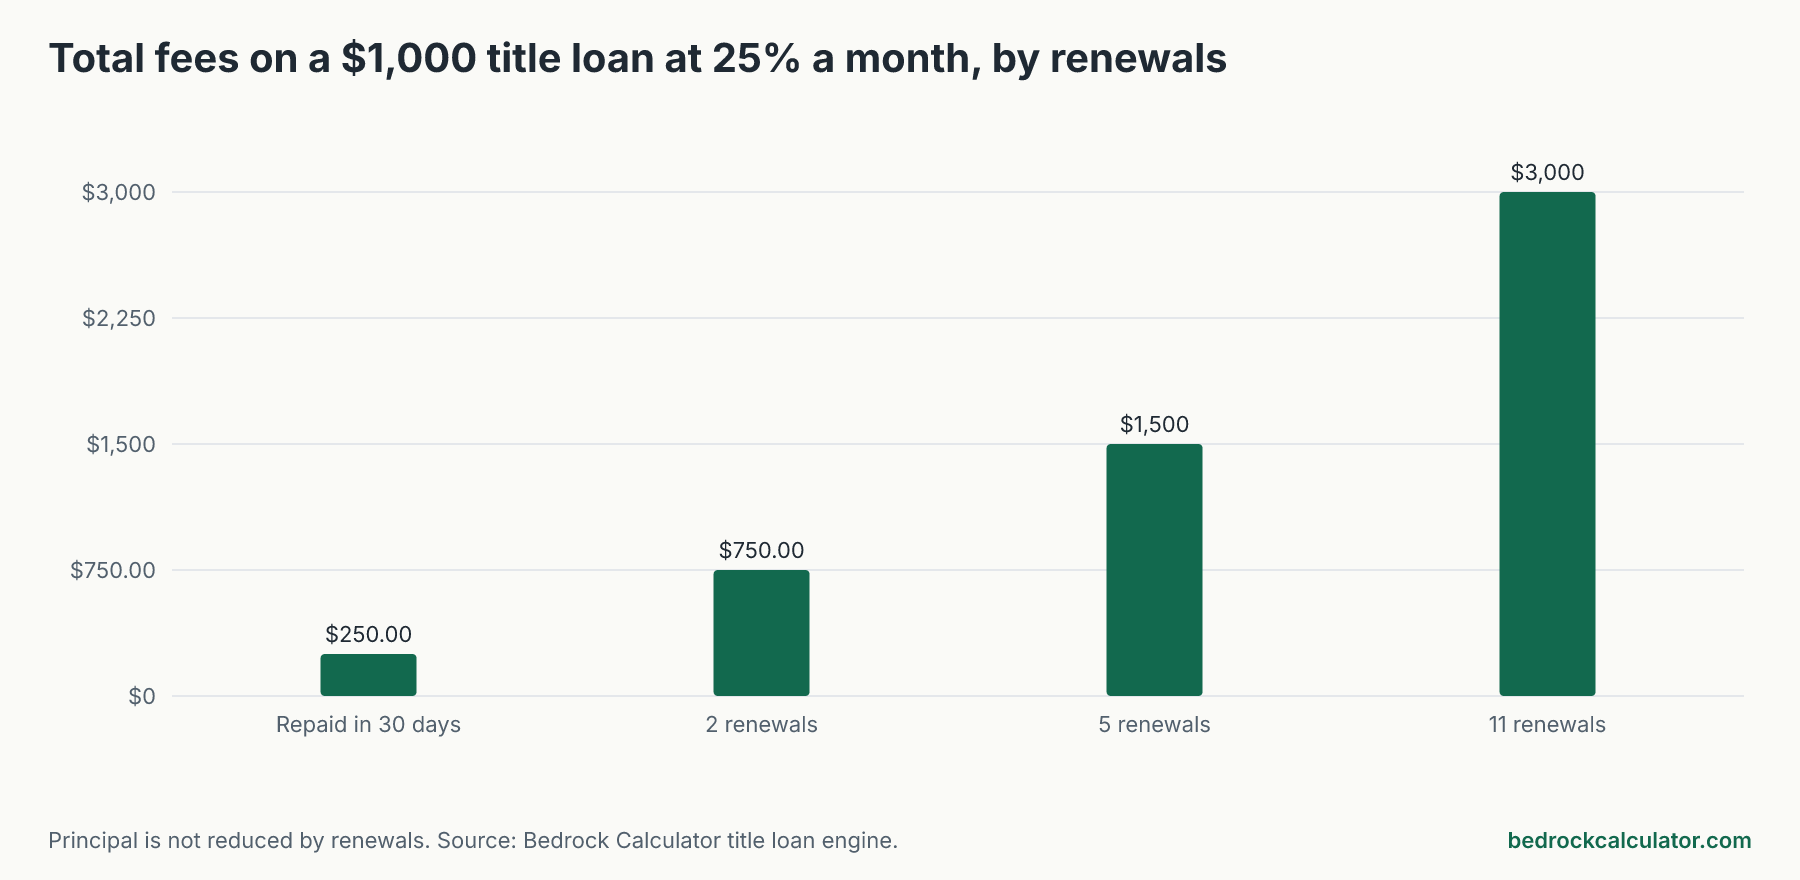
Car title loan cost on $1,000 by monthly rate and renewals
Download CSVFlat monthly finance charge on the full amount; each 30-day renewal charges it again with no principal repaid.
| 10% | 120.00% | $100.00 | $300.00 | $600.00 | $1,200.00 |
| 15% | 180.00% | $150.00 | $450.00 | $900.00 | $1,800.00 |
| 20% | 240.00% | $200.00 | $600.00 | $1,200.00 | $2,400.00 |
| 25% | 300.00% | $250.00 | $750.00 | $1,500.00 | $3,000.00 |
A title loan's monthly rate looks smaller than a payday fee, but it runs on a full month and is often renewed. At 25% a month, one month on $1,000 costs $250.00. Two renewals bring the total to $750.00. Five renewals cost $1,500.00, more than the loan itself.
And because the car is the collateral, falling behind can mean losing it. That's a cost no APR captures.
How these compare with other credit
For scale, the CFPB notes that credit card APRs are a small fraction of typical payday rates. Even at the bottom of the ranges here, $10 per $100 for 31 days, the payday APR is 117.74%. A title loan at 10% a month is 120.00%.
If you're short on cash, it's worth checking options before a payday or title loan: a payment plan with the bill you can't cover, a credit union small-dollar loan, or an advance from your employer. Our credit card payoff timelines show what card debt costs at typical rates.
What this leaves out
- State law. Many states cap payday fees, limit rollovers or ban these loans outright, and title lending rules vary even more. The calculators don't apply any state's rules.
- Extra fees. Late fees, returned-payment fees, processing or document fees and repossession costs aren't included.
- Paying down principal. Some title lenders let or make you repay part of the principal at each renewal, which lowers later fees. The title loan calculator assumes interest-only renewals.
- The simple APR. The APR here is the standard simple annualized rate used in disclosures. The title loan figure is twelve times the monthly rate, with no compounding.
Run your own numbers
Enter the exact fee and due date from your loan offer in the payday loan APR calculator, or the amount, monthly rate and expected renewals in the title loan calculator. To compare with a fixed-rate installment loan, the personal loan calculator shows the payment and total interest. Our guide to APR vs interest rate explains what the annual rate does and doesn't include.