How much do you need to pay each month to clear a credit card?
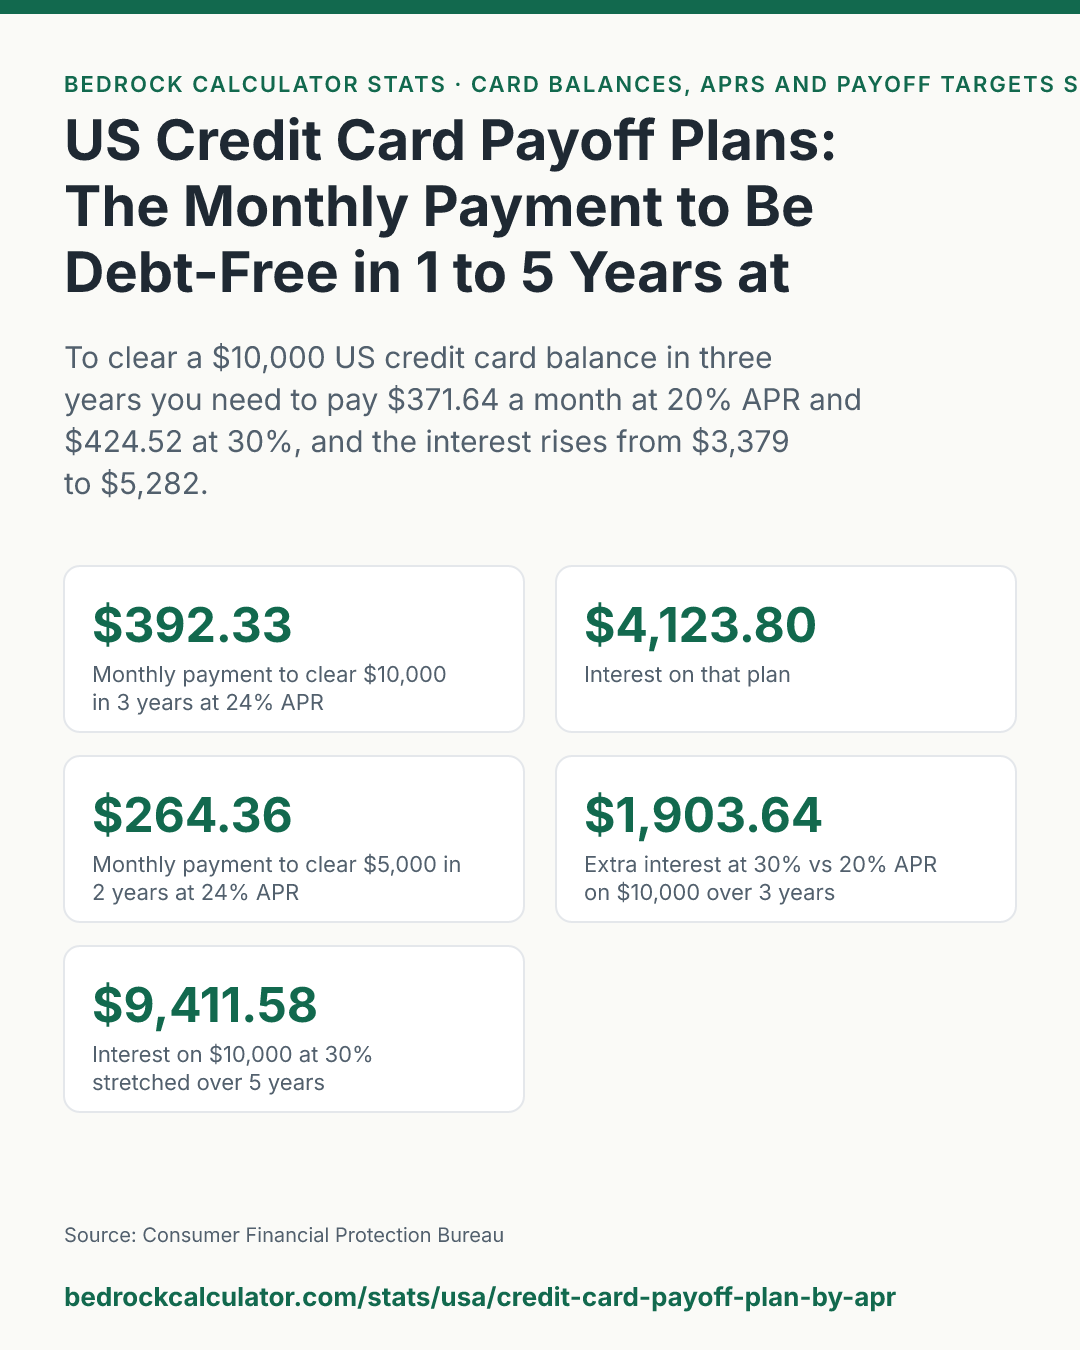
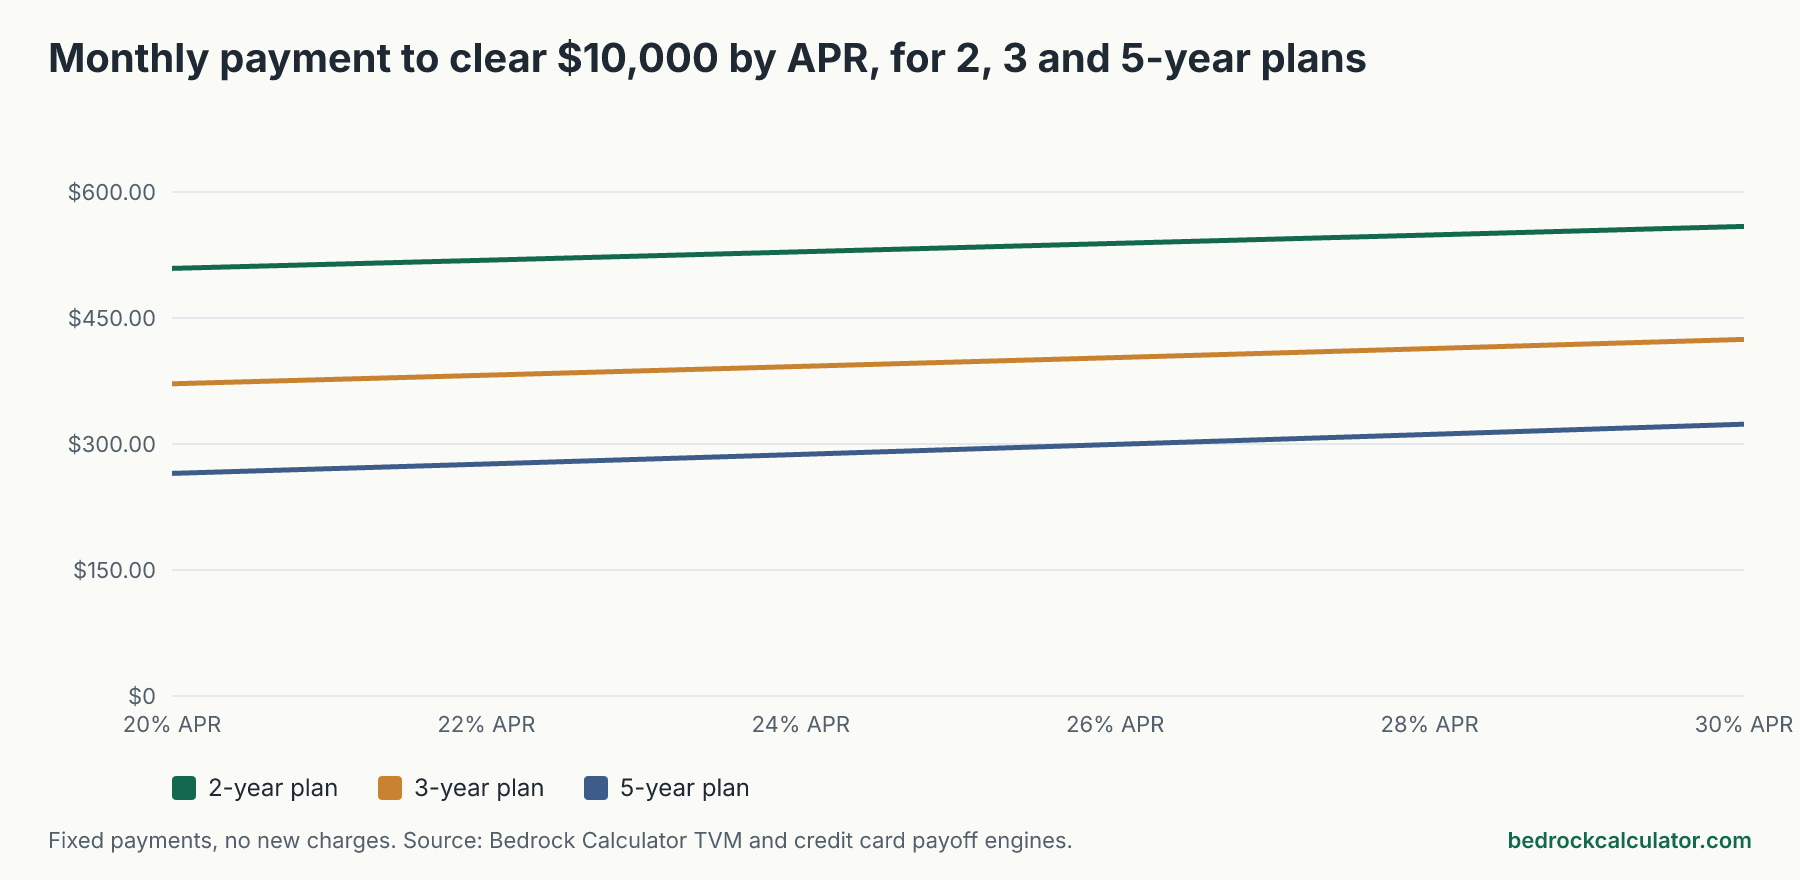
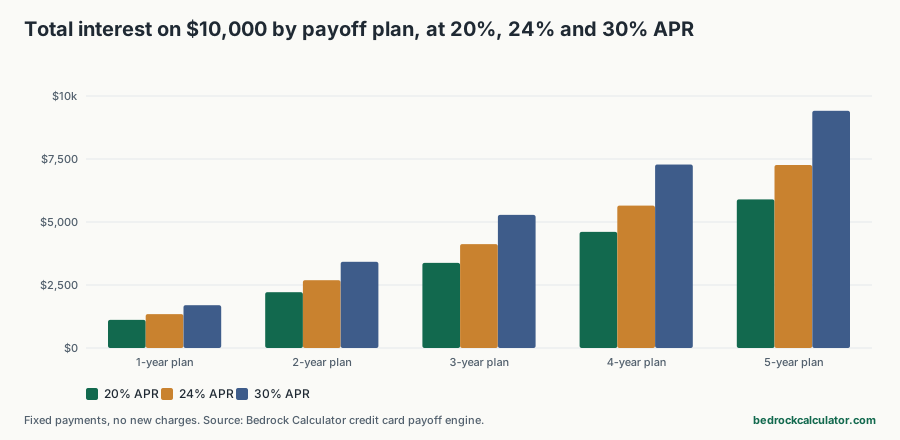
Pick a date to be debt-free and the math tells you the payment. To clear a $10,000 US credit card balance in three years, you need $371.64 a month at 20% APR, $392.33 at 24% and $424.52 at 30%. Over those three years the interest comes to $3,378.84, $4,123.80 and $5,282.48.
On $5,000 the payments halve. Two years at 24% APR takes $264.36 a month and costs $1,344.50 in interest.
Why start from a deadline
Most payoff advice starts with the payment you can afford and asks how long it'll take. Our page on credit card payoff time and minimum payments does exactly that. This page runs it the other way. You choose a finish line, one to five years out, and we show the fixed payment that gets you there and what it costs.
That framing is useful because a deadline is something you can plan a budget around. "Pay $528.72 a month for two years" is a concrete instruction. "Pay what you can" tends to slide toward the minimum, which is where card debt lasts for decades.
How we worked out these numbers
For each balance, APR and deadline, we worked out the fixed monthly payment with the standard loan payment formula from the site's engine, using the APR divided by 12 as the monthly rate, and rounded it up to the next cent. Then we ran that payment through the credit card payoff calculator and recorded the months and total interest it returned. Every plan paid off right on its deadline.
The calculator charges interest each month on the remaining balance, subtracts your payment, and repeats. It assumes:
- the APR stays fixed for the whole plan
- you make no new purchases on the card
- there are no fees, penalty rates or promotional rates
Every plan, side by side
Sort by any column. Each balance has 30 plans: six APRs from 20% to 30%, and five deadlines from one year to five.
Monthly payment and interest to pay off a credit card by a deadline, 20% to 30% APR
Download CSVFixed payment every month, no new purchases or fees, interest at APR divided by 12. Payment rounded up to the cent; months and interest from the credit card payoff calculator.
| $5,000 | 20% | 1 year | $463.18 | 12 | $558.06 |
| $5,000 | 20% | 2 years | $254.48 | 24 | $1,107.49 |
| $5,000 | 20% | 3 years | $185.82 | 36 | $1,689.42 |
| $5,000 | 20% | 4 years | $152.16 | 48 | $2,303.09 |
| $5,000 | 20% | 5 years | $132.47 | 60 | $2,948.14 |
| $5,000 | 22% | 1 year | $467.98 | 12 | $615.65 |
| $5,000 | 22% | 2 years | $259.40 | 24 | $1,225.32 |
| $5,000 | 22% | 3 years | $190.96 | 36 | $1,874.17 |
| $5,000 | 22% | 4 years | $157.54 | 48 | $2,561.19 |
| $5,000 | 22% | 5 years | $138.10 | 60 | $3,285.41 |
| $5,000 | 24% | 1 year | $472.80 | 12 | $673.57 |
| $5,000 | 24% | 2 years | $264.36 | 24 | $1,344.50 |
| $5,000 | 24% | 3 years | $196.17 | 36 | $2,061.82 |
| $5,000 | 24% | 4 years | $163.01 | 48 | $2,824.41 |
| $5,000 | 24% | 5 years | $143.84 | 60 | $3,630.38 |
| $5,000 | 26% | 1 year | $477.66 | 12 | $731.79 |
| $5,000 | 26% | 2 years | $269.38 | 24 | $1,464.90 |
| $5,000 | 26% | 3 years | $201.46 | 36 | $2,252.19 |
| $5,000 | 26% | 4 years | $168.59 | 48 | $3,092.03 |
| $5,000 | 26% | 5 years | $149.71 | 60 | $3,981.67 |
| $5,000 | 28% | 1 year | $482.53 | 12 | $790.36 |
| $5,000 | 28% | 2 years | $274.45 | 24 | $1,586.56 |
| $5,000 | 28% | 3 years | $206.82 | 36 | $2,445.41 |
| $5,000 | 28% | 4 years | $174.27 | 48 | $3,364.16 |
| $5,000 | 28% | 5 years | $155.68 | 60 | $4,340.69 |
| $5,000 | 30% | 1 year | $487.44 | 12 | $849.22 |
| $5,000 | 30% | 2 years | $279.57 | 24 | $1,709.49 |
| $5,000 | 30% | 3 years | $212.26 | 36 | $2,641.24 |
| $5,000 | 30% | 4 years | $180.03 | 48 | $3,641.44 |
| $5,000 | 30% | 5 years | $161.77 | 60 | $4,705.79 |
| $10,000 | 20% | 1 year | $926.35 | 12 | $1,116.13 |
| $10,000 | 20% | 2 years | $508.96 | 24 | $2,214.98 |
| $10,000 | 20% | 3 years | $371.64 | 36 | $3,378.84 |
| $10,000 | 20% | 4 years | $304.31 | 48 | $4,606.42 |
| $10,000 | 20% | 5 years | $264.94 | 60 | $5,896.28 |
| $10,000 | 22% | 1 year | $935.95 | 12 | $1,231.32 |
| $10,000 | 22% | 2 years | $518.79 | 24 | $2,450.71 |
| $10,000 | 22% | 3 years | $381.91 | 36 | $3,748.48 |
| $10,000 | 22% | 4 years | $315.07 | 48 | $5,122.66 |
| $10,000 | 22% | 5 years | $276.19 | 60 | $6,571.31 |
| $10,000 | 24% | 1 year | $945.60 | 12 | $1,347.15 |
| $10,000 | 24% | 2 years | $528.72 | 24 | $2,689.01 |
| $10,000 | 24% | 3 years | $392.33 | 36 | $4,123.80 |
| $10,000 | 24% | 4 years | $326.02 | 48 | $5,648.83 |
| $10,000 | 24% | 5 years | $287.68 | 60 | $7,260.76 |
| $10,000 | 26% | 1 year | $955.31 | 12 | $1,463.60 |
| $10,000 | 26% | 2 years | $538.75 | 24 | $2,929.87 |
| $10,000 | 26% | 3 years | $402.91 | 36 | $4,504.56 |
| $10,000 | 26% | 4 years | $337.18 | 48 | $6,184.06 |
| $10,000 | 26% | 5 years | $299.41 | 60 | $7,963.96 |
| $10,000 | 28% | 1 year | $965.06 | 12 | $1,580.72 |
| $10,000 | 28% | 2 years | $548.89 | 24 | $3,173.20 |
| $10,000 | 28% | 3 years | $413.64 | 36 | $4,890.81 |
| $10,000 | 28% | 4 years | $348.53 | 48 | $6,728.70 |
| $10,000 | 28% | 5 years | $311.36 | 60 | $8,681.37 |
| $10,000 | 30% | 1 year | $974.88 | 12 | $1,698.44 |
| $10,000 | 30% | 2 years | $559.13 | 24 | $3,419.06 |
| $10,000 | 30% | 3 years | $424.52 | 36 | $5,282.48 |
| $10,000 | 30% | 4 years | $360.06 | 48 | $7,282.87 |
| $10,000 | 30% | 5 years | $323.54 | 60 | $9,411.58 |
Faster plans cost more a month and far less in total
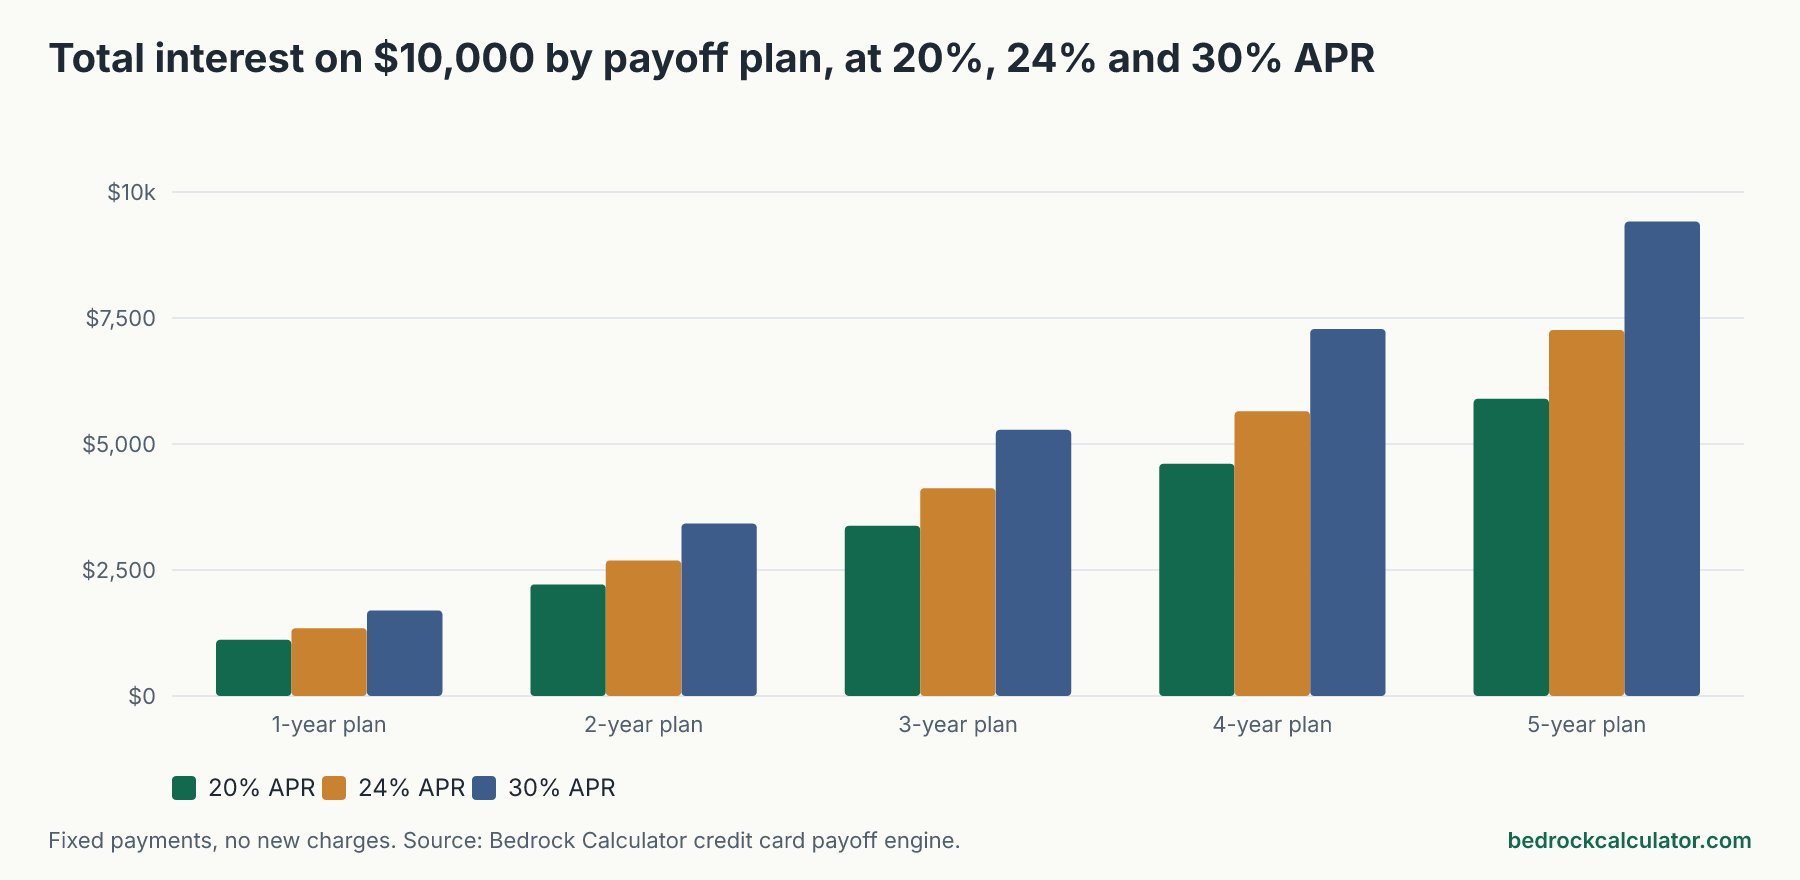
Stretching a plan out lowers the payment, but the savings shrink as you go and the interest keeps climbing. On $10,000 at 24% APR:
- a 1-year plan is $945.60 a month with $1,347.15 of interest
- a 2-year plan is $528.72 a month with $2,689.01
- a 3-year plan is $392.33 a month with $4,123.80
- a 5-year plan is $287.68 a month with $7,260.76
Going from five years to two raises the payment by $241.04 a month and saves $4,571.75 of interest. At 30% APR, the five-year plan's interest is 94.1% of the original balance. A one-year plan at 20% costs 11.2%.
How much the APR matters
At a fixed deadline, the APR changes both what you pay each month and the total. On a three-year plan for $10,000, going from 20% to 30% APR adds $52.88 to the monthly payment and $1,903.64 to the interest. That's about $190.36 for every percentage point. Over five years the same ten-point gap costs $3,515.30.
The first month shows why. At 30% APR on $10,000, interest in month one is $250.00. On the three-year plan, only $174.52 of the first payment goes to the balance. The split improves every month as the balance falls, which is the reason a fixed payment works: it stays the same while the interest shrinks.
That's why it's worth trying to get the rate down before you start. Calling your issuer, moving the balance to a lower-rate card, or refinancing with a fixed-rate personal loan can all help, as long as you keep the payment where it is and don't run the card back up. If you'd pay a transfer fee, add it to the balance before you compare.
Picking a plan you'll stick with
A plan only works if the payment fits. A few ways to choose:
- Start with the shortest plan you can afford. Find your balance and APR in the table and pick the shortest deadline whose payment you can make every month without new card spending.
- Treat the payment as fixed. When your card's minimum falls, keep paying the plan amount. Letting the payment drop is what turns a three-year plan into a ten-year one.
- Put windfalls on top. A tax refund or bonus paid on top of the plan brings the finish line forward.
- More than one card? Paying the highest-rate card first saves the most interest. Our debt snowball vs avalanche example compares the two orders.
What this leaves out
These limits come from the calculator.
- Variable APRs. Most card rates move with the prime rate. A rise during your plan adds months unless you raise the payment.
- New purchases. Any new spending on the card pushes the deadline back.
- Daily interest. Many issuers charge interest on the average daily balance. The calculator uses the APR divided by 12 on each month's balance, which is close but not identical.
- Fees and promotional rates. Annual fees, late fees, penalty APRs, zero-interest offers and transfer fees aren't modeled.
Run your own numbers
Enter your balance, APR and a payment in the credit card payoff calculator to see your exact months and interest, then nudge the payment until the months match your deadline. With several debts, the debt payoff calculator and the debt snowball vs avalanche calculator work through them together. If you're weighing a consolidation loan, the loan payoff calculator shows its payment and interest.