Which costs less on a $400,000 home, an FHA, VA or conventional loan?
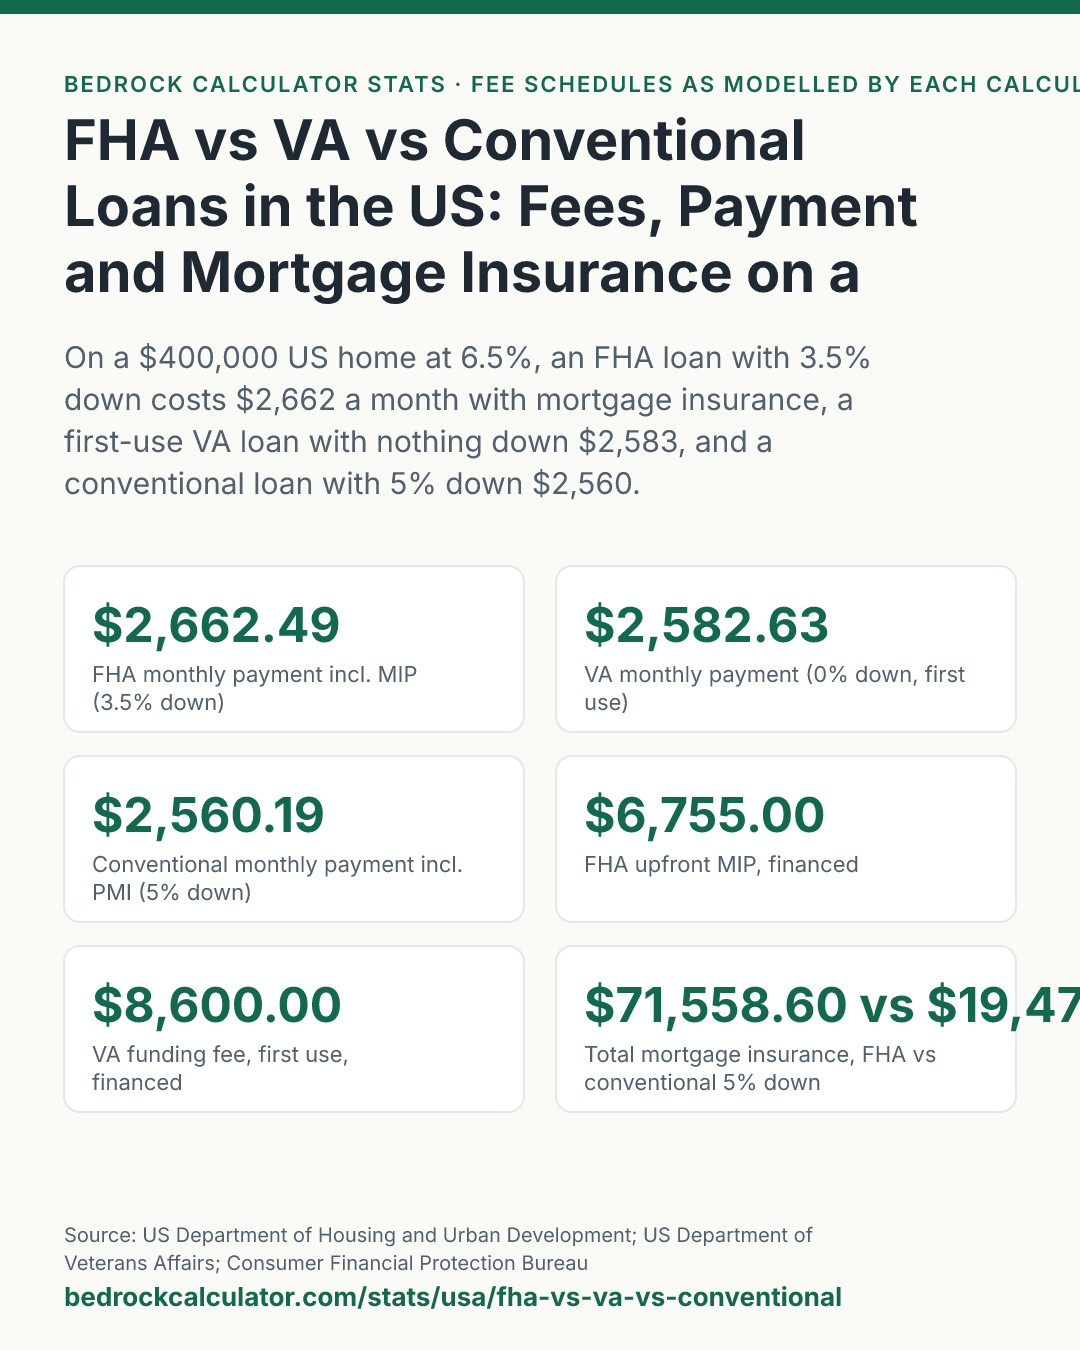
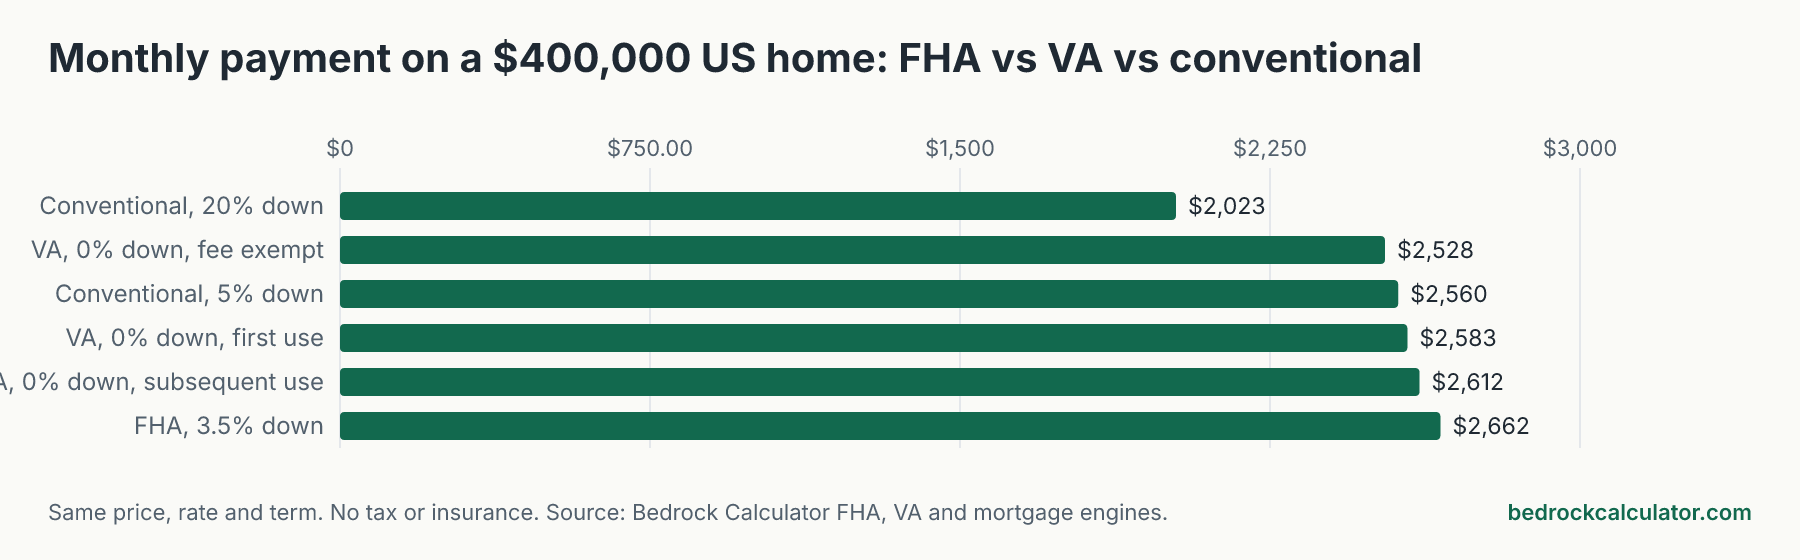
Put the same $400,000 US home and the same 6.5% rate through three kinds of loan and the monthly payment barely moves, but the fees and the lifetime cost do. With mortgage insurance included, FHA with 3.5% down costs $2,662.49 a month, a first-use VA loan with nothing down costs $2,582.63, and a conventional loan with 5% down costs $2,560.19.
Where they really split is how long the insurance lasts. Conventional PMI in this example stops after 123 payments. FHA's annual premium runs for all 30 years, so over the full term FHA costs $68,352.61 more than the conventional loan.
The three loans in plain terms
FHA loans are insured by the federal government and let you buy with as little as 3.5% down. In return you pay mortgage insurance twice: an upfront premium of 1.75% of the loan, usually added to the balance, and an annual premium paid monthly. With less than 10% down, that annual premium stays for the life of the loan.
VA loans are for eligible veterans, service members and some surviving spouses. They need no down payment and carry no monthly mortgage insurance. Instead there's a one-time funding fee, 2.15% of the loan on first use with less than 5% down and 3.30% on later use. Veterans who receive VA disability compensation don't pay it.
Conventional loans aren't government-backed. With less than 20% down you pay private mortgage insurance, PMI, but it comes off once you've paid the balance down far enough. With 20% down there's none.
How we worked out these numbers
Each loan came from its own calculator on this site: the FHA loan calculator, the VA loan calculator and the mortgage calculator for conventional loans. Every one used a $400,000 price, a fixed 6.5% rate and a 30-year term, so the loan type is the only thing that changes.
The insurance rates are each calculator's defaults. FHA annual MIP is 0.55% of the loan a year, the standard rate for a 30-year FHA loan with less than 5% down. Conventional PMI is 0.5% of the loan a year, charged until the balance on the original schedule reaches 80% of the price. Both the FHA upfront premium and the VA funding fee are financed, which is how most borrowers pay them.
This comparison covers only the fees these calculators model. Be clear about what's not here:
- Different rates. In practice FHA and VA rates are often a bit lower than conventional rates, and conventional rates depend heavily on credit score. We held the rate equal to isolate the fees.
- PMI pricing. Real PMI premiums vary with your credit score and down payment. A borrower with a high score may pay less than 0.5%; one with a lower score may pay much more.
- FHA MIP on a falling balance. HUD bases the annual premium on the average balance each year, so it drifts down slowly. The FHA calculator holds the monthly premium fixed on the original loan, which slightly overstates total FHA insurance.
- Closing costs, lender fees, property tax and homeowners insurance. None are included. Every loan type has closing costs, and tax and insurance would add the same amount to each monthly payment.
- Refinancing. Many FHA borrowers refinance into a conventional loan once they have enough equity, which ends the MIP. The totals here assume every loan runs its full term.
Monthly payment and upfront fees side by side
FHA vs VA vs conventional on a $400,000 home at 6.5% over 30 years
Download CSVPrincipal, interest and mortgage insurance only. Upfront fees are financed into the loan. No property tax, homeowners insurance, lender fees or closing costs.
| Conventional, 20% down | $80,000.00 | $0.00 | $320,000.00 | $2,022.62 | $0.00 | $2,022.62 |
| VA, 0% down, fee exempt | $0.00 | $0.00 | $400,000.00 | $2,528.27 | $0.00 | $2,528.27 |
| Conventional, 5% down | $20,000.00 | $0.00 | $380,000.00 | $2,401.86 | $158.33 | $2,560.19 |
| VA, 0% down, first use | $0.00 | $8,600.00 | $408,600.00 | $2,582.63 | $0.00 | $2,582.63 |
| VA, 0% down, subsequent use | $0.00 | $13,200.00 | $413,200.00 | $2,611.71 | $0.00 | $2,611.71 |
| FHA, 3.5% down | $14,000.00 | $6,755.00 | $392,755.00 | $2,482.48 | $180.01 | $2,662.49 |
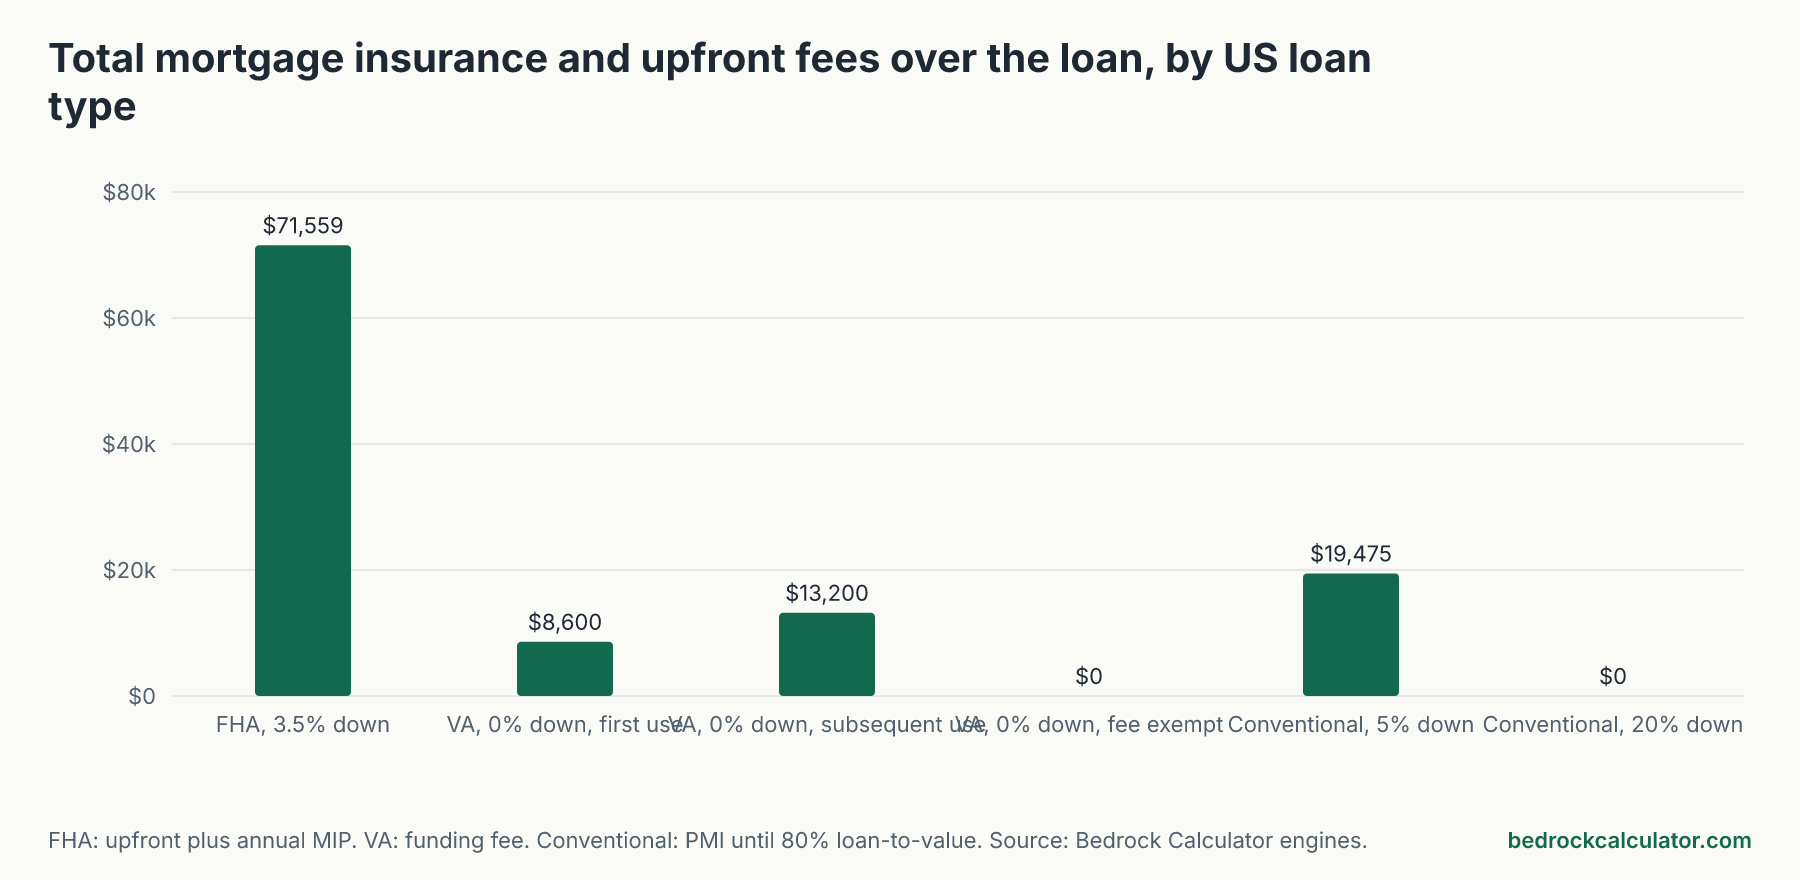
The VA funding fee is the biggest upfront charge here: $8,600.00 on first use, or $13,200.00 on later use. FHA's upfront premium is $6,755.00. Conventional loans have no comparable government fee, though lenders charge their own closing costs on every loan type.
Because those fees are financed, they raise the amount you borrow and therefore the principal and interest. A first-use VA borrower borrows $408,600.00 to buy a $400,000 home, while a VA borrower who's exempt from the fee borrows exactly the price and pays $2,528.27 a month.
A first-use VA loan costs $79.86 a month less than FHA, even with nothing down, because it has no monthly insurance. Conventional with 5% down beats FHA by $102.30 a month. And putting 20% down on a conventional loan drops the payment to $2,022.62, $537.57 less than with 5% down.
FHA MIP vs conventional PMI over the life of the loan
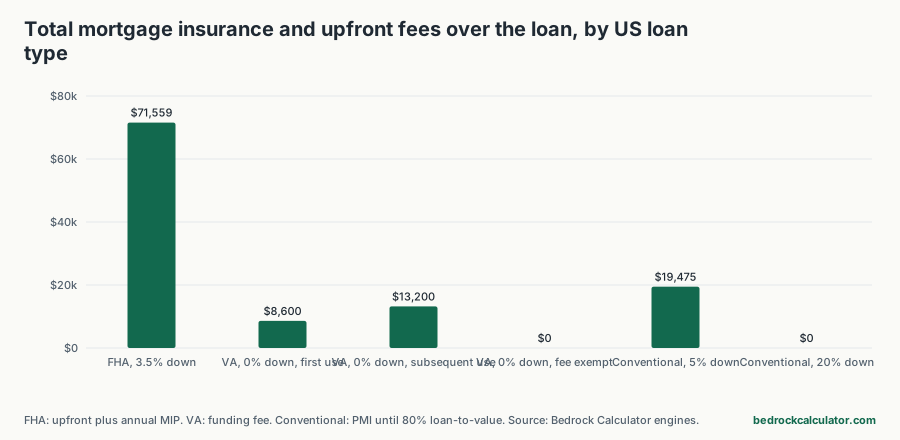
This is the number that tends to decide between FHA and conventional for borrowers who qualify for both. FHA's upfront and annual premiums add up to $71,558.60 if you keep the loan the full 30 years. Conventional PMI on 5% down adds up to $19,474.59, because it ends after 10.25 years. That's a $52,084.01 difference in insurance alone.
Lifetime cost of each loan on a $400,000 home
Download CSVTotal paid = down payment + every principal and interest payment + every monthly mortgage insurance payment, if the loan runs the full term.
| Conventional, 20% down | 0 | $0.00 | $408,140.64 | $808,140.64 |
| Conventional, 5% down | 123 | $19,474.59 | $484,667.97 | $904,142.56 |
| VA, 0% down, fee exempt | 0 | $0.00 | $510,179.81 | $910,179.81 |
| VA, 0% down, first use | 0 | $8,600.00 | $521,146.81 | $929,746.81 |
| VA, 0% down, subsequent use | 0 | $13,200.00 | $527,010.19 | $940,210.19 |
| FHA, 3.5% down | 360 | $71,558.60 | $500,936.57 | $972,495.17 |
The lifetime table adds the down payment, every principal and interest payment and every monthly insurance payment. FHA's total is $972,495.17, against $904,142.56 for conventional with 5% down and $929,746.81 for a first-use VA loan. FHA can still be the right choice. Its credit score requirements are looser, and if your score would put you in an expensive PMI tier, the comparison can flip. Our page on PMI cost by down payment shows how much PMI varies.
Which loan makes sense for you
If you're eligible for a VA loan, it's usually the cheapest way to buy with little or nothing down, and if you're exempt from the funding fee, it's cheaper still. If you have a solid credit score and at least 5% down, a conventional loan usually wins on lifetime cost because PMI ends. FHA is often the best route when your credit score is lower or your debts are higher than conventional lenders will accept. Our page on debt-to-income limits shows how much debt lenders allow at each income.
To compare your own options, run your price and rate through the FHA loan calculator, the VA loan calculator and the mortgage calculator, and check your ratios in the debt-to-income ratio calculator. If rates have moved, our table of mortgage payments at every rate shows how much a quarter point changes the payment.